Optical Networking And Communications Market
Optical Networking And Communications Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711943 | Published On : November 22, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Optical Networking And Communications Market Size
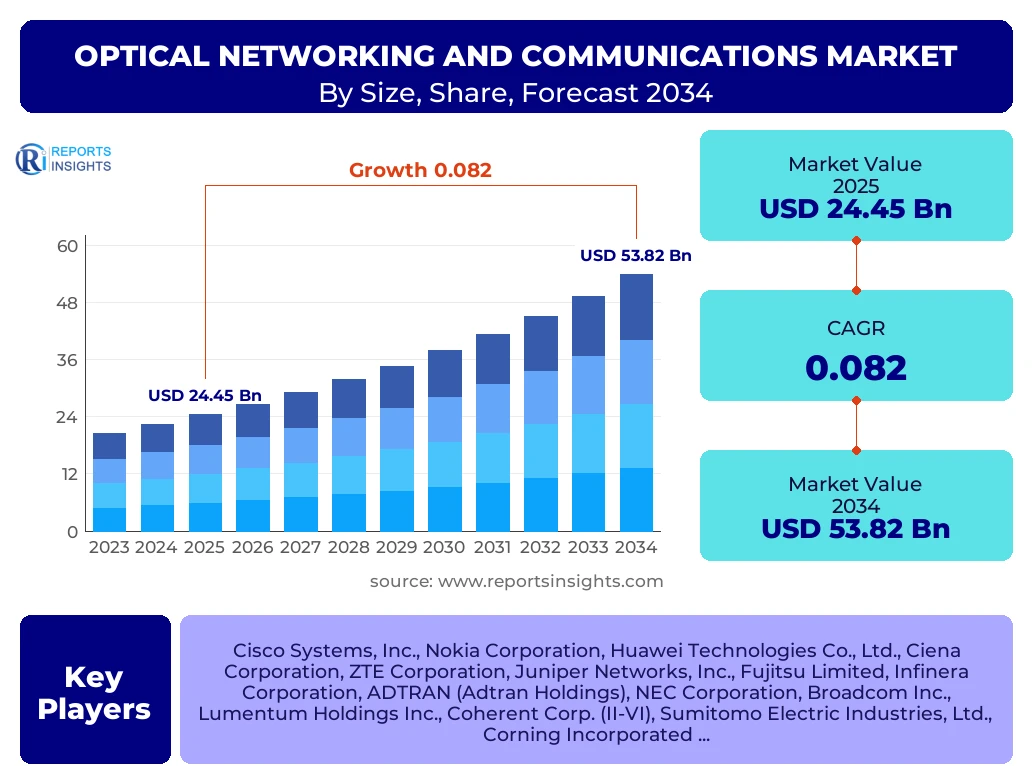
According to Reports Insights Consulting Pvt Ltd, The Optical Networking And Communications Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.2% between 2025 and 2034. The market is estimated at USD 26.45 Billion in 2026 and is projected to reach USD 53.82 Billion by the end of the forecast period in 2034.
Key Optical Networking And Communications Market Trends & Insights
The global optical networking and communications landscape is undergoing a radical transformation driven by the escalating demand for high-speed data transmission and the transition toward 5G and 6G infrastructures. Regional insights indicate that the Asia-Pacific region is currently the epicenter of growth, fueled by aggressive investments in telecommunication infrastructure in China and India. Competitive benchmarking reveals that industry leaders are pivoting toward software-defined networking (SDN) and network functions virtualization (NFV) to enhance operational efficiency. Users frequently inquire about the integration of artificial intelligence in optical layer management, which is emerging as a critical trend to optimize bandwidth allocation and predictive maintenance in dense wavelength division multiplexing systems.
- Asia-Pacific is the fastest-growing region due to rapid digital transformation and massive fiber-to-the-home (FTTH) deployments.
- North America remains the largest region in terms of market share, driven by the presence of major hyperscale data centers and early 5G adoption.
- The Wavelength Division Multiplexing (WDM) segment is the largest technology segment, holding over 45% of the market share.
- Increasing adoption of 400G and 800G optical transceivers is a dominant trend in data center interconnect applications.
- The shift toward Open Optical Networking is gaining momentum, allowing operators to avoid vendor lock-in and foster innovation.
Key Takeaways Optical Networking And Communications Market Size & Forecast
The market size and forecast analysis suggest a robust trajectory underpinned by the proliferation of Internet of Things (IoT) devices and the surging consumption of video-on-demand services. Stakeholders are particularly focused on the reduction of power consumption per bit and the miniaturization of optical components. The transition from 100G to 400G and eventually 800G and 1.2T systems is expected to be a primary revenue driver through 2034. Strategic questions regarding the resilience of optical supply chains and the impact of geopolitical trade policies on semiconductor components for optical modules are currently at the forefront of market discussions.
- The United States is the leading country in high-capacity optical infrastructure investment, particularly in the cloud service provider segment.
- China is the largest consumer of fiber optic cables and passive optical network (PON) equipment globally.
- Enterprise adoption of private 5G networks is creating secondary demand for short-reach optical interconnects.
- Energy-efficient coherent optics are becoming a mandatory requirement for sustainable data center operations.
- The integration of quantum key distribution (QKD) within optical networks is emerging as a vital security consideration for government and financial sectors.
Optical Networking And Communications Market Drivers Analysis
The market is primarily propelled by the exponential growth in global IP traffic and the necessity for low-latency communication networks to support emerging technologies like autonomous vehicles and augmented reality. As enterprises migrate their workloads to the cloud, the pressure on backhaul and metro networks has increased significantly, necessitating hardware upgrades. Furthermore, government initiatives aimed at bridging the digital divide through rural broadband expansion projects provide a sustained tailwind for the deployment of long-haul and access optical networks.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| 5G and 6G Infrastructure Expansion | +2.8% | Global (Strongest in APAC) | 2025 - 2034 |
| Hyperscale Data Center Proliferation | +2.1% | North America and Europe | 2025 - 2030 |
| Rural Broadband and FTTH Initiatives | +1.5% | India, Brazil, Southeast Asia | 2025 - 2034 |
| Growth in High-Definition Video Streaming | +1.2% | Developed Economies | 2025 - 2028 |
Optical Networking And Communications Market Restraints Analysis
Despite the positive growth outlook, the market faces significant hurdles related to the high initial capital expenditure (CAPEX) required for laying physical fiber infrastructure, particularly in geographically challenging terrains. Additionally, the complexity of managing heterogeneous network environments where legacy equipment must coexist with modern high-speed optical systems can slow down the adoption of newer technologies. Regulatory constraints and long lead times for obtaining rights-of-way for fiber installation also act as significant barriers to rapid market expansion.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial CAPEX for Fiber Deployment | -1.4% | Emerging Markets | 2025 - 2034 |
| Geopolitical Trade Tensions & Supply Chain Disruptions | -0.9% | US, China, Europe | 2025 - 2027 |
| Legacy Infrastructure Integration Challenges | -0.5% | Global | 2025 - 2029 |
Optical Networking And Communications Market Opportunities Analysis
The market presents substantial opportunities in the realm of Coherent Optical Technology and the development of pluggable modules that can be integrated directly into switches and routers. This "IP-over-DWDM" approach reduces the need for separate transponder shelves, lowering both cost and power consumption. Additionally, the rise of edge computing creates a need for distributed optical nodes closer to the end-user, while the underwater (submarine) cable market remains a critical frontier for connecting continents and expanding the global internet backbone.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of 800G and 1.2T Technologies | +3.2% | Japan, US, South Korea | 2027 - 2034 |
| Submarine Cable Network Projects | +1.8% | Coastal Regions (MEA, APAC) | 2025 - 2034 |
| Open RAN and Open Optical Disaggregation | +1.4% | Europe and North America | 2026 - 2032 |
Optical Networking And Communications Market Challenges Impact Analysis
A major challenge in the industry is the shortage of skilled technical labor capable of designing and maintaining advanced photonic systems. Moreover, the increasing heat dissipation requirements of high-speed transceivers pose significant thermal management challenges for hardware manufacturers. Rapid technological obsolescence also means that companies must continuously invest in research and development to remain competitive, which can strain the margins of smaller players in the ecosystem.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Photonics Engineers | -0.8% | Global | 2025 - 2034 |
| Thermal Management in High-Speed Modules | -0.6% | Hardware OEMs | 2026 - 2030 |
| Standardization Issues in Interoperability | -0.4% | Global | 2025 - 2028 |
Optical Networking And Communications Market - Updated Report Scope
The scope of this report encompasses a detailed quantitative and qualitative analysis of the global optical networking and communications market across various technology, component, and application segments. It provides a granular view of the competitive landscape, highlighting strategic initiatives such as mergers, acquisitions, and product innovations. The analysis covers the entire value chain, from raw material suppliers of optical fibers to the end-users in telecommunications and enterprise sectors, ensuring a holistic understanding of the market dynamics over the forecast period.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 24.45 Billion |
| Market Forecast in 2034 | USD 53.82 Billion |
| Growth Rate | 8.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Cisco Systems, Inc., Nokia Corporation, Huawei Technologies Co., Ltd., Ciena Corporation, ZTE Corporation, Juniper Networks, Inc., Fujitsu Limited, Infinera Corporation, ADTRAN (Adtran Holdings), NEC Corporation, Broadcom Inc., Lumentum Holdings Inc., Coherent Corp. (II-VI), Sumitomo Electric Industries, Ltd., Corning Incorporated, Ribbon Communications, Mitsubishi Electric, FiberHome Telecommunication Technologies. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the optical networking and communications market reveals diverse growth patterns across different technological layers and end-use categories. The component segment is particularly dynamic, with transceivers evolving rapidly to accommodate higher data rates and smaller form factors. Meanwhile, the WDM technology segment remains the backbone of long-haul and metro networks due to its ability to maximize the capacity of existing fiber assets. End-user analysis shows that while telecommunications remains the primary revenue contributor, the data center segment is experiencing the highest growth rate as cloud giants build massive interconnected facilities.
- By Technology: Wavelength Division Multiplexing (WDM) dominates, with Dense WDM (DWDM) being critical for long-distance transport. SONET/SDH is gradually being phased out in favor of Packet Optical Transport.
- By Component: Optical Transceivers represent the highest value component, with a shift toward 400G and 800G modules. Optical Fiber remains a steady growth area driven by global FTTH rollouts.
- By End-User: The IT & Telecom sector accounts for the largest share, followed by the rapidly expanding Data Center segment. Healthcare and BFSI are emerging as significant consumers of high-security optical links.
- By Application: Metro networks are seeing increased investment to handle localized data traffic from 5G cells, while long-haul networks are being upgraded with coherent technology.
Regional Highlights
- Asia Pacific (APAC): The largest and fastest-growing market. China leads in fiber production and deployment, while India’s "Digital India" initiative is accelerating broadband penetration in semi-urban and rural areas.
- North America: A mature market characterized by the presence of major cloud service providers like Amazon, Google, and Microsoft, who are primary drivers of the 800G transceiver market.
- Europe: Growth is focused on the modernization of existing copper networks to fiber and the deployment of 5G across major economies like Germany, France, and the UK.
- Middle East and Africa (MEA): Emerging as a hub for international submarine cable landings, connecting Europe and Asia, which spurs local terrestrial optical network investments.
- Latin America: Market growth is driven by Brazil and Mexico, where privatization of the telecom sector has led to increased competition and infrastructure investment.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Optical Networking And Communications Market.- Cisco Systems, Inc.
- Nokia Corporation
- Huawei Technologies Co., Ltd.
- Ciena Corporation
- ZTE Corporation
- Juniper Networks, Inc.
- Fujitsu Limited
- Infinera Corporation
- ADTRAN (Adtran Holdings)
- NEC Corporation
- Broadcom Inc.
- Lumentum Holdings Inc.
- Coherent Corp. (II-VI Incorporated)
- Sumitomo Electric Industries, Ltd.
- Corning Incorporated
- Ribbon Communications
- Mitsubishi Electric Corporation
- FiberHome Telecommunication Technologies Co., Ltd.
- HFR Inc.
- Smartoptics
Frequently Asked Questions
What is the current market size and projected growth of the Optical Networking and Communications market?
The market is valued at approximately USD 24.45 Billion in 2025 and is projected to grow at a CAGR of 8.2%, reaching USD 53.82 Billion by 2034. This growth is primarily driven by 5G expansion and hyperscale data center demands.
Which technology is leading the Optical Networking market?
Wavelength Division Multiplexing (WDM), specifically Dense WDM (DWDM), is the leading technology. It allows multiple data streams to be sent simultaneously over a single optical fiber, making it essential for high-capacity long-haul and metro networks.
Who are the key players in the global optical communications industry?
Major industry leaders include Cisco, Huawei, Nokia, Ciena, and ZTE. These companies focus on providing end-to-end optical transport solutions, including transponders, switches, and network management software.
How does the adoption of 5G affect the optical networking market?
5G requires a significantly denser network of base stations, all of which need high-capacity optical fiber for backhaul and fronthaul. This has led to a surge in demand for optical transceivers and fiber optic cables to support the low-latency requirements of 5G.
What are the main challenges facing the optical networking market?
The main challenges include high capital costs for infrastructure deployment, complex integration with legacy systems, geopolitical trade restrictions on key semiconductor components, and a shortage of specialized photonic engineering talent.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
