Office Real Estate Market
Office Real Estate Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711663 | Published On : November 11, 2026 |
Format : 


 | Author : Ridam Bhatt
Office Real Estate Market Size
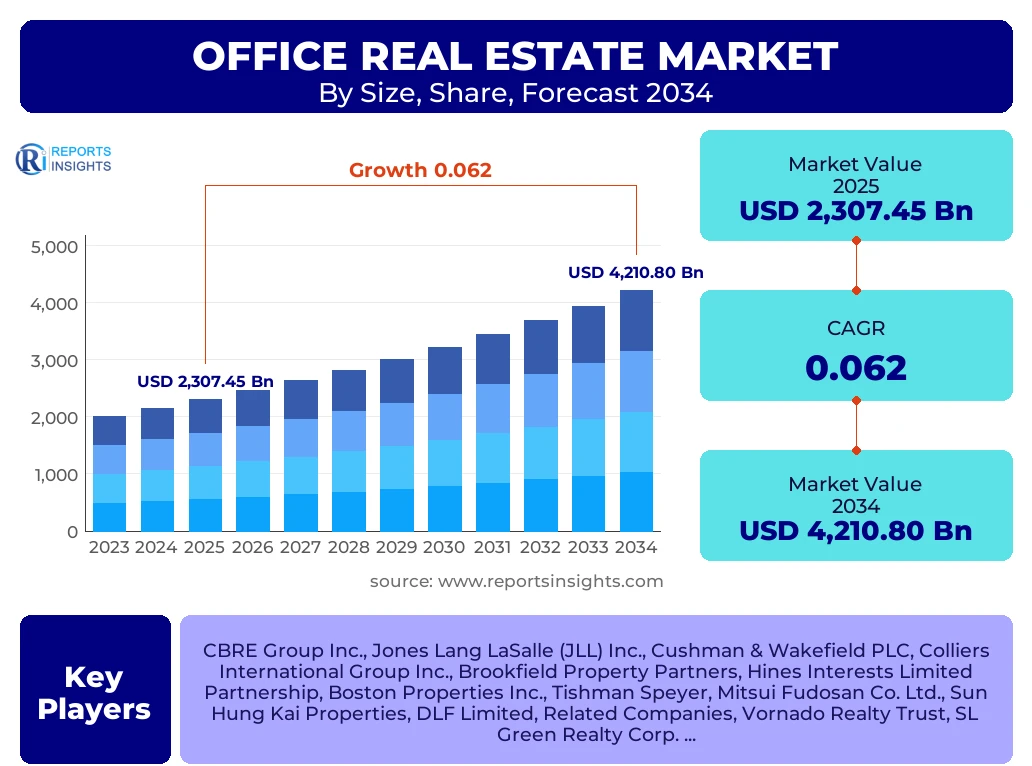
According to Reports Insights Consulting Pvt Ltd, The Office Real Estate Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 2,450.50 Billion in 2026 and is projected to reach USD 4,210.80 Billion by the end of the forecast period in 2034.
Key Office Real Estate Market Trends & Insights
The global office real estate sector is undergoing a profound structural transformation, driven by the permanent integration of hybrid work models and a significant "flight to quality" among corporate tenants. Regional insights indicate that while North America remains the largest market by value, the Asia-Pacific region is emerging as the fastest-growing hub due to rapid urbanization and the expansion of the outsourcing sector. Market benchmarking reveals that Class A properties, particularly those with high environmental certifications, are outperforming older inventory in both occupancy rates and rental premiums. Competitive dynamics are shifting toward "Office-as-a-Service," where landlords provide flexible, high-amenity environments to attract top-tier talent in a competitive labor market.
- North America currently stands as the largest regional market, bolstered by high concentrations of corporate headquarters and advanced PropTech integration.
- Asia-Pacific is the fastest-growing region, fueled by rising demand in secondary cities and massive investments in commercial infrastructure in India and Southeast Asia.
- Class A Office Spaces represent the largest segment by value share, as enterprises prioritize premium locations to encourage employee return-to-office initiatives.
- The Flexible Workspace segment is recording the highest growth rate as corporate occupiers seek to mitigate long-term lease liabilities.
- ESG-compliant buildings are commanding a "green premium" in rental rates across major financial districts in Europe and North America.
Key Takeaways Office Real Estate Market Size & Forecast
The long-term outlook for the office real estate market remains cautiously optimistic, supported by the resilience of service-based economies and the necessity for physical collaboration hubs. Data suggests that while total floor area requirements may stabilize, the spend per square foot is increasing as tenants demand sophisticated technology and wellness-oriented features. The market forecast anticipates a significant surge in redevelopment projects as stakeholders look to repurpose underperforming Class B and C assets into mixed-use or modern collaborative environments. Strategically, the market is pivoting toward localized clusters that offer proximity to residential areas and lifestyle amenities, reflecting the decentralization of traditional business districts.
- The United States continues to be the leading country in terms of institutional investment volume and market maturity.
- India is emerging as a critical growth engine for the APAC region, driven by the global capability center (GCC) expansion and institutional REIT activity.
- Technological integration, including AI-driven building management systems, is becoming a non-negotiable requirement for prime office developments.
- The forecast period will see a notable shift toward modular office designs that allow for rapid reconfiguration based on team-specific needs.
- Sustainability mandates from regional governments, particularly in the European Union, are forcing a massive wave of retrofitting across the existing office stock.
Office Real Estate Market Drivers Analysis
The primary catalysts for growth in the office real estate sector include the rapid digital transformation of corporate operations and the persistent need for centralized hubs for innovation and corporate culture. As businesses compete for specialized talent, the office environment has transitioned from a simple utility to a strategic recruitment tool. Furthermore, the rise of institutional investment and the proliferation of Real Estate Investment Trusts (REITs) have provided the necessary liquidity for large-scale, high-quality developments across emerging markets.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Flight to Quality and Premium Amenities | +1.8% | Global (High in North America & Europe) | 2025 - 2034 |
| Expansion of Global Capability Centers (GCCs) | +1.5% | Asia Pacific (India, Philippines) | 2025 - 2030 |
| Green Building Mandates and ESG Compliance | +1.2% | European Union, UK | 2026 - 2034 |
| Urbanization and Infrastructure Development | +0.9% | China, Southeast Asia | 2025 - 2034 |
Office Real Estate Market Restraints Analysis
Market growth is currently tempered by high interest rates which have increased the cost of capital and complicated the refinancing of existing debt for many commercial property owners. Additionally, the widespread adoption of remote work has led to a significant percentage of sublease space hitting the market, putting downward pressure on rental growth in secondary and tertiary locations where demand is less concentrated.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Interest Rates and Cost of Capital | -1.1% | Global (High in United States) | 2025 - 2027 |
| Shadow Vacancy and Sublease Availability | -0.8% | Major Tech Hubs (San Francisco, London) | 2025 - 2028 |
| Stricter Lending Standards by Regional Banks | -0.5% | North America | 2025 - 2026 |
Office Real Estate Market Opportunities Analysis
The current market environment offers significant opportunities for the adaptive reuse of aging office structures into life sciences labs, healthcare facilities, or residential units. Moreover, the integration of PropTech and Internet of Things (IoT) sensors provides a lucrative avenue for landlords to offer enhanced data analytics to tenants, helping them optimize their space utilization and reduce operational costs, thereby justifying higher lease premiums.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adaptive Reuse and Conversion Projects | +1.4% | Urban Centers in USA and UK | 2026 - 2034 |
| Smart Building Technology Integration | +1.1% | Singapore, UAE, Japan | 2025 - 2034 |
| Suburban Satellite Office Development | +0.7% | Western Europe | 2027 - 2034 |
Office Real Estate Market Challenges Impact Analysis
One of the most persistent challenges facing the office real estate market is the discrepancy between tenant expectations for high-end, sustainable spaces and the high cost of construction and renovation. Furthermore, the volatility in corporate headcounts, particularly in the technology sector, makes long-term demand forecasting difficult for developers, often leading to a mismatch between supply and actual occupancy requirements.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Volatility for Construction Materials | -0.6% | Global | 2025 - 2029 |
| Evolving Zoning Regulations for Mixed-Use | -0.4% | Latin America, MEA | 2025 - 2030 |
Office Real Estate Market - Updated Report Scope
This report provides a granular analysis of the global office real estate ecosystem, examining the interplay between economic indicators, corporate occupancy trends, and technological advancements. It covers the full spectrum of office assets, from traditional Central Business Districts to emerging suburban tech parks. The scope includes a detailed evaluation of investment flows, tenant preferences across different industry verticals, and the impact of environmental regulations on asset valuation and liquidity.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2,307.45 Billion |
| Market Forecast in 2034 | USD 4,210.80 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | CBRE Group Inc., Jones Lang LaSalle (JLL) Inc., Cushman & Wakefield PLC, Colliers International Group Inc., Brookfield Property Partners, Hines Interests Limited Partnership, Boston Properties Inc., Tishman Speyer, Mitsui Fudosan Co. Ltd., Sun Hung Kai Properties, DLF Limited, Related Companies, Vornado Realty Trust, SL Green Realty Corp., Newmark Group Inc., Savills PLC, Knight Frank LLP, Alexandria Real Estate Equities Inc., Kilroy Realty Corporation, British Land Company PLC. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The office real estate market is segmented to reflect the diverse needs of modern organizations and the varying investment profiles of property owners. Property Class remains the dominant differentiator, as the performance gap between top-tier Class A assets and older inventory continues to widen. Geographically, the distinction between CBD and Suburban locations is evolving, with many organizations adopting a "hub-and-spoke" model that requires high-quality office footprints in both urban centers and professional residential suburbs.
- By Property Class:
- Class A: Premium spaces with high-end finishes, state-of-the-art systems, and prime locations.
- Class B: Functional spaces with average finishes, often in older buildings but well-maintained.
- Class C: Lower-cost options with basic amenities, typically targeted for redevelopment.
- By Location:
- Central Business District (CBD): Traditional economic centers with high density and transit connectivity.
- Suburban: Office parks and standalone buildings located outside major city cores.
- Urban Fringe: Emerging areas bordering CBDs offering a mix of accessibility and lower costs.
- By Ownership Type:
- REITs: Publicly traded entities providing high liquidity and professional management.
- Institutional Investors: Pension funds, sovereign wealth funds, and insurance companies focused on long-term yields.
- Private Ownership: Individual investors or family offices managing specific asset portfolios.
- By Industry Vertical:
- Banking, Financial Services, and Insurance (BFSI)
- Information Technology (IT) & Telecom
- Healthcare and Life Sciences
- Creative and Media Services
- Government and Non-Profit Organizations
Regional Highlights
North America remains the global leader in office real estate, driven by the maturity of its financial markets and the concentration of high-growth technology and financial firms. Within this region, the United States is the primary contributor, with a market characterized by high institutional participation and a rapid adoption of sustainable building practices. While major coastal cities have faced challenges due to shifting work patterns, secondary markets like Austin, Nashville, and Charlotte are seeing robust growth due to lower costs and talent migration.
The Asia-Pacific region is recognized as the fastest-growing market, with India and China at the forefront. India’s office market is exceptionally resilient, supported by the booming technology sector and the institutionalization of the market through several successful REIT listings. In Europe, the market is defined by stringent environmental regulations, where cities like London, Paris, and Frankfurt are leading the way in "green" office developments. The Middle East, particularly Dubai and Riyadh, is seeing significant investment in futuristic office districts as part of broader economic diversification initiatives.
- United States: Largest market globally with the highest volume of Class A office stock and REIT activity.
- India: Fastest-growing major market, particularly in cities like Bangalore, Hyderabad, and Mumbai, driven by global tech demand.
- United Kingdom: Key financial hub with London remaining a critical destination for international capital despite post-Brexit adjustments.
- China: Significant supply of new office space in Tier 1 cities, though currently balancing through a period of economic recalibration.
- Germany: Strong demand for high-quality office space in decentralized regional hubs such as Munich and Berlin.
- United Arab Emirates: Rapid expansion of luxury and tech-focused office spaces as part of the Dubai 2040 Urban Master Plan.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Office Real Estate Market.- CBRE Group Inc.
- Jones Lang LaSalle (JLL) Inc.
- Cushman & Wakefield PLC
- Colliers International Group Inc.
- Brookfield Property Partners
- Hines Interests Limited Partnership
- Boston Properties Inc.
- Tishman Speyer
- Mitsui Fudosan Co. Ltd.
- Sun Hung Kai Properties
- DLF Limited
- Related Companies
- Vornado Realty Trust
- SL Green Realty Corp.
- Newmark Group Inc.
- Savills PLC
- Knight Frank LLP
- Alexandria Real Estate Equities Inc.
- Kilroy Realty Corporation
- British Land Company PLC
Frequently Asked Questions
What is the current size and growth potential of the global office real estate market?
The market is estimated at USD 2,450.50 Billion in 2026 and is projected to reach USD 4,210.80 Billion by 2034, growing at a CAGR of 6.2%. This growth is driven by the demand for high-quality, tech-enabled, and sustainable workspaces despite the rise in remote work models.
How is the "Flight to Quality" trend impacting office rental rates?
The flight to quality has created a bifurcated market where Class A buildings with premium amenities and ESG certifications are seeing rental increases and high occupancy, while older, un-renovated Class B and C properties are experiencing higher vacancy and rental stagnation.
Which regions are expected to witness the highest growth in office real estate?
Asia-Pacific is expected to be the fastest-growing region, particularly India and Southeast Asia, due to expanding global capability centers. North America remains the largest region by market value, supported by deep institutional investment and technological innovation.
What role does ESG compliance play in the current office real estate market?
ESG compliance is now a critical factor in asset valuation. Tenants are increasingly demanding carbon-neutral buildings to meet their own corporate sustainability goals, and investors are prioritizing green-certified assets to mitigate future regulatory risks and secure lower financing rates.
How are hybrid work models changing office design and space requirements?
Hybrid work is shifting demand toward flexible layouts, "hot-desking" areas, and increased space for collaborative meetings rather than traditional individual cubicles. Occupiers are seeking shorter lease terms and "plug-and-play" environments that can scale with their workforce volatility.
Author
R
Ridam Bhatt is a Manger Consumer Goods Research with over 6+ years of experience in the Consumer Goods Industry. He specializes in consumer market intelligence, demand forecasting, category performance analysis, competitive benchmarking, pricing strategy, retail and distribution assessment, consumer purchasing behavior, product portfolio evaluation, and market trend analysis across fast-moving and durable consumer goods segments. His research delivers actionable, data-driven insights that help organizations make strategic business decisions, identify growth opportunities, optimize operational performance, understand evolving consumer trends, and strengthen their competitive positioning in global consumer goods markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
