Non Pvc Iv Bags Market
Non Pvc Iv Bags Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711094 | Published On : October 06, 2026 |
Format : 


 | Author : Erika Grotto
Non Pvc Iv Bags Market Size
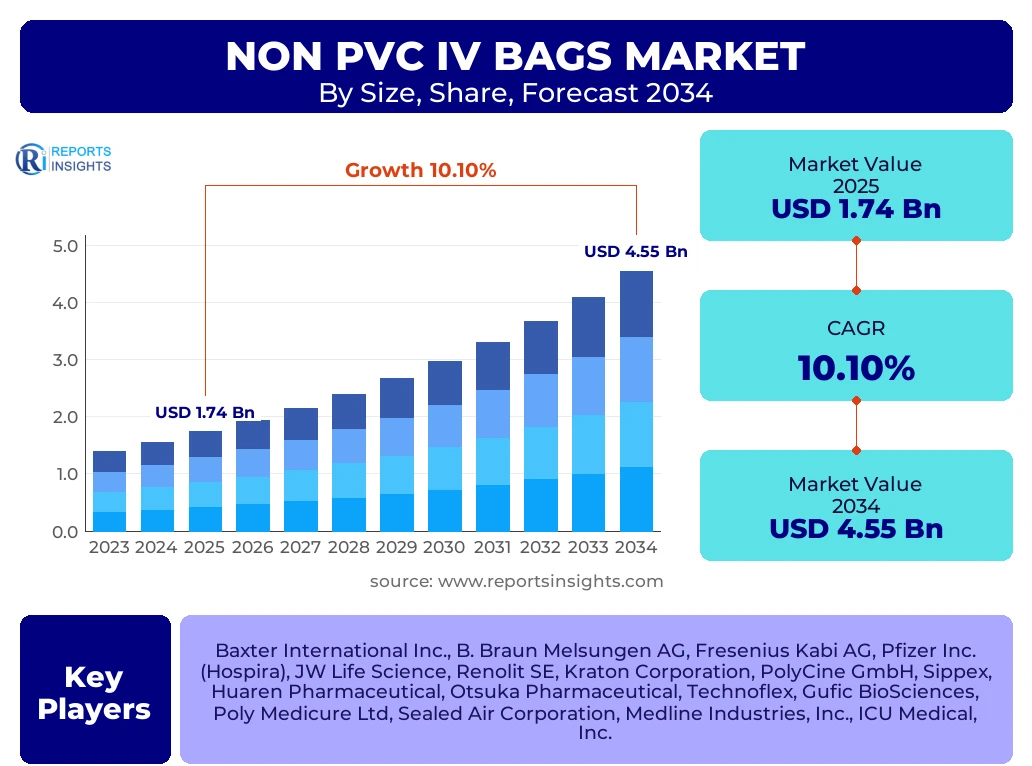
According to Reports Insights Consulting Pvt Ltd, The Non Pvc Iv Bags Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 10.1% between 2025 and 2034. The market is estimated at USD 1.92 Billion in 2026 and is projected to reach USD 4.55 Billion by the end of the forecast period in 2034.
Key Non Pvc Iv Bags Market Trends & Insights
The Non-PVC IV bags market is undergoing a significant transformation driven by the global healthcare sector’s shift toward safer, more eco-friendly medical consumables. The primary catalyst is the increasing awareness of the health risks associated with Diethylhexyl Phthalate (DEHP) and Polyvinyl Chloride (PVC) materials, which are known to leach harmful chemicals into the intravenous fluids. Consequently, regulatory bodies across North America and Europe have implemented stringent guidelines favoring non-PVC alternatives. Furthermore, the rise in chronic diseases requiring long-term parenteral nutrition and chemotherapy is pushing hospitals and clinics to adopt multi-chamber non-PVC bags that offer superior chemical compatibility and reduced risk of drug adsorption. Manufacturers are focusing on advanced polymer blends, such as ethylene vinyl acetate (EVA) and polypropylene, to ensure high transparency, durability, and flexibility, which are critical for clinical efficiency and patient safety.
- Largest Region: North America currently holds the largest market share, driven by advanced healthcare infrastructure and strict FDA regulations regarding medical device materials.
- Fastest Growing Region: Asia Pacific is the fastest-growing region due to expanding healthcare access, rising geriatric populations, and increasing medical tourism in countries like China, India, and Japan.
- Largest Segment by Share: Multi-chamber non-PVC bags are the leading segment in terms of market share, particularly due to their high utility in complex drug delivery and clinical nutrition.
- Material Trend: Polypropylene (PP) based bags are seeing the highest adoption rates due to their excellent heat resistance and recyclability.
Key Takeaways Non Pvc Iv Bags Market Size & Forecast
The forecast period from 2025 to 2034 indicates a robust expansion for the non-PVC IV bags market, characterized by technological innovations in material science and a global push for sustainable medical practices. Strategic partnerships between polymer manufacturers and medical device companies are expected to streamline the supply chain and reduce the price gap between traditional PVC bags and their non-PVC counterparts. Additionally, the increasing preference for outpatient care and home-based infusion therapies is creating a significant demand for portable and durable IV bag systems. Stakeholders are also observing a shift in hospital procurement policies where ESG (Environmental, Social, and Governance) scores are becoming a deciding factor, further favoring the adoption of recyclable non-PVC materials.
- Leading Country: The United States remains the dominant force in the global market, accounting for a significant portion of the North American revenue due to high healthcare spending.
- High Demand Sector: Hospitals and emergency clinics are the primary end-users, but the home care setting is projected to show the highest growth rate during the forecast period.
- Innovation Focus: Development of PVC-free, latex-free, and DEHP-free bags that can withstand sterilization temperatures up to 121 degrees Celsius.
- Forecast Stability: The market is expected to remain resilient despite economic fluctuations due to the essential nature of intravenous therapy in modern medicine.
Non Pvc Iv Bags Market Drivers Analysis
Market drivers for non-PVC IV bags are primarily centered on clinical safety and regulatory mandates. The transition from legacy PVC systems to non-toxic alternatives is no longer optional in many developed healthcare systems, as the risk of leaching endocrine-disrupting chemicals into patient bloodstreams poses significant legal and health risks. Furthermore, the increasing complexity of modern pharmaceuticals, including biologics and oncology drugs, requires inert packaging materials that do not interact with the active ingredients.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Regulatory Bans on DEHP and PVC | +3.2% | European Union & United States | 2025 - 2034 |
| Rising Prevalence of Chronic Diseases | +2.8% | Global | 2025 - 2034 |
| Growth in Parenteral Nutrition Demand | +2.5% | Asia Pacific & North America | 2026 - 2030 |
| Shift Towards Green Healthcare Practices | +1.6% | Global | 2027 - 2034 |
Non Pvc Iv Bags Market Restraints Analysis
The primary restraint facing the non-PVC IV bags market is the higher cost of production compared to traditional PVC bags. The specialized polymer resins required for non-PVC bags are more expensive to source and process, which can be a deterrent for healthcare providers in emerging economies with limited budgets. Additionally, the technical challenges in manufacturing bags that match the flexibility and clarity of PVC without using plasticizers can sometimes lead to supply chain bottlenecks.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Higher Cost of Non-PVC Materials | -1.5% | Developing Markets (Africa/SEA) | 2025 - 2034 |
| Technical Complexity in Sealing and Manufacturing | -0.8% | Global | 2025 - 2028 |
Non Pvc Iv Bags Market Opportunities Analysis
Significant opportunities exist in the expansion of healthcare infrastructure in emerging markets such as India, Brazil, and Southeast Asia. As these regions modernize their clinical protocols, they are increasingly skipping the transition phases and moving directly to non-PVC standards. Moreover, the development of customized IV bags for specialized applications like cell therapy and high-potency drugs offers a high-margin niche for manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion in Emerging Economies | +3.5% | India, China, Brazil | 2026 - 2034 |
| Development of Specialty Bags for Oncology | +2.2% | Global | 2025 - 2034 |
| Rise of Home Healthcare and Self-Infusion | +1.9% | Japan & Western Europe | 2026 - 2032 |
Non Pvc Iv Bags Market Challenges Impact Analysis
The market faces challenges regarding the disposal and recycling infrastructure for non-PVC materials. While they are more eco-friendly than PVC, the lack of standardized medical waste recycling programs in many regions limits the full realization of their environmental benefits. Additionally, maintaining the physical integrity of these bags under extreme temperatures during transport remains a logistical hurdle.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lack of Specialized Recycling Infrastructure | -1.2% | Global | 2025 - 2034 |
| Raw Material Price Volatility | -0.7% | Global | 2025 - 2030 |
Non Pvc Iv Bags Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global non-PVC IV bags market, segmented by product type, material, content, and end-user. It provides historical data and future projections to help stakeholders identify investment opportunities and competitive threats across different geographical landscapes.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.74 Billion |
| Market Forecast in 2034 | USD 4.55 Billion |
| Growth Rate | 10.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Baxter International Inc., B. Braun Melsungen AG, Fresenius Kabi AG, Pfizer Inc. (Hospira), JW Life Science, Renolit SE, Kraton Corporation, PolyCine GmbH, Sippex, Huaren Pharmaceutical, Otsuka Pharmaceutical, Technoflex, Gufic BioSciences, Poly Medicure Ltd, Sealed Air Corporation, Medline Industries, Inc., ICU Medical, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the non-PVC IV bags market highlights the diverse applications and material requirements across the healthcare spectrum. By dividing the market into specific product and material categories, stakeholders can pinpoint high-growth areas such as multi-chamber bags used in parenteral nutrition or EVA-based bags for low-temperature storage of specialized medications.
- Product Type: Single-chamber bags remain common for standard saline and glucose delivery, while multi-chamber bags are surging in popularity for complex drug mixing and nutrition.
- Material: Polypropylene (PP) is favored for its thermal stability and clarity. EVA is increasingly used for frozen contents due to its flexibility at low temperatures.
- Content: Liquid content bags dominate the volume, but frozen content bags are gaining ground in the biologics and cell therapy sectors.
- End-User: Hospitals are the primary revenue generator, but the home care setting is the most dynamic segment due to the rise in aging populations and outpatient treatment trends.
Regional Highlights
- North America: Holds the largest market share (approx 38%) due to early adoption of non-PVC mandates and high concentration of leading market players in the United States.
- Asia Pacific: The fastest-growing region with a projected CAGR of over 11.5%, fueled by massive healthcare infrastructure projects in China and India and rising awareness of patient safety.
- Europe: A mature market characterized by strict sustainability standards and extensive use of multi-chamber bags in public healthcare systems.
- Latin America & MEA: Steady growth regions where market penetration is increasing as global manufacturers establish local production facilities to reduce costs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Non Pvc Iv Bags Market.- Baxter International Inc.
- B. Braun Melsungen AG
- Fresenius Kabi AG
- Pfizer Inc. (Hospira)
- JW Life Science
- Renolit SE
- Kraton Corporation
- PolyCine GmbH
- Sippex
- Huaren Pharmaceutical
- Otsuka Pharmaceutical
- Technoflex
- Gufic BioSciences
- Poly Medicure Ltd
- Sealed Air Corporation
- Medline Industries, Inc.
- ICU Medical, Inc.
- Sichuan Kelun Pharmaceutical
Frequently Asked Questions
What is the primary reason for the shift from PVC to Non-PVC IV bags?
The primary reason is the health risk associated with DEHP, a plasticizer used in PVC that can leach into the IV fluid, potentially causing endocrine disruption and other toxic effects. Non-PVC bags provide a safer, inert alternative for drug delivery.
Which material is most commonly used in the production of Non-PVC IV bags?
Polypropylene (PP) is the most common material due to its excellent transparency, chemical resistance, and ability to withstand high-temperature sterilization processes like autoclaving.
What is the projected market growth for Non-PVC IV bags by 2034?
The market is projected to reach USD 4.55 Billion by 2034, growing at a steady CAGR of 10.1% as healthcare providers worldwide phase out hazardous PVC materials.
Are multi-chamber Non-PVC bags better than single-chamber bags?
Multi-chamber bags offer the advantage of keeping incompatible drugs or nutrients separate until the point of administration, which reduces the risk of contamination and simplifies the workflow for healthcare professionals.
Which region offers the most significant growth opportunities for manufacturers?
The Asia Pacific region offers the highest growth opportunities due to rapid healthcare modernization, increasing hospital investments, and a large patient pool requiring intravenous therapies.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
