Microprocessor Market
Microprocessor Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_704028 | Published On : September 09, 2026 |
Format : 


 | Author : Shamin Verma
Microprocessor Market Size
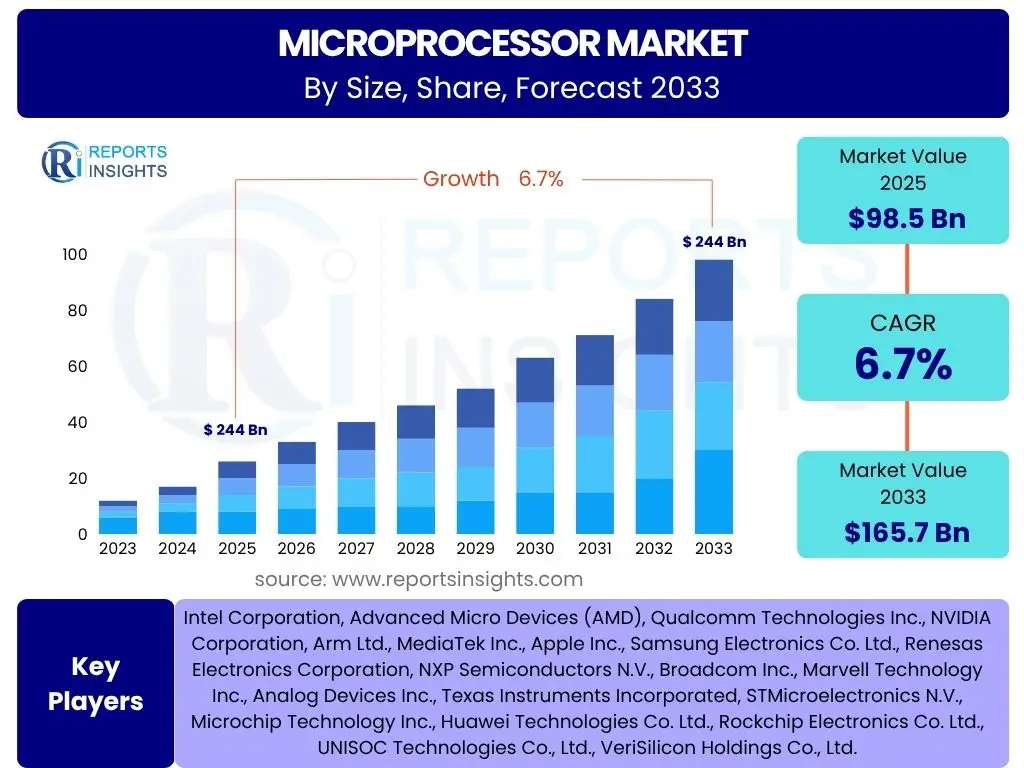
According to Reports Insights Consulting Pvt Ltd, The Microprocessor Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2026 and 2034. The market is estimated at USD 118.4 Billion in 2026 and is projected to reach USD 200.2 Billion by the end of the forecast period in 2034.
Key Microprocessor Market Trends & Insights
The global microprocessor landscape is undergoing a fundamental shift characterized by the decentralization of processing power and the integration of artificial intelligence (AI) directly into the silicon architecture. Current market intelligence indicates a significant pivot toward custom silicon solutions as major hyperscalers and consumer electronics giants seek to optimize performance-per-watt for specific workloads. The rise of the RISC-V architecture as a viable open-source alternative to proprietary instruction sets is disrupting traditional market hierarchies, particularly in regional markets aiming for technological sovereignty. Furthermore, the transition toward 3nm and 2nm process nodes, facilitated by Extreme Ultraviolet (EUV) lithography, is enabling unprecedented transistor density, which is essential for the next generation of high-performance computing (HPC) and autonomous systems.
- Largest Region: Asia Pacific remains the dominant regional market, accounting for over 45% of the global share due to its massive electronics manufacturing ecosystem and rapid data center expansion.
- Fastest Growing Region: North America is projected to witness the highest growth rate during the forecast period, driven by intensive R&D in AI hardware and the domestic fabrication initiatives spurred by the CHIPS Act.
- Largest Segment by Technology: The x86 architecture continues to hold the largest market share in terms of revenue, primarily sustained by the established server and personal computing sectors.
- Fastest Growing Segment: The ARM-based microprocessor segment is experiencing accelerated growth, fueled by its dominance in mobile devices and increasing adoption in the laptop and automotive markets.
- Key Trend: The adoption of Chiplet technology is revolutionizing manufacturing, allowing companies to combine specialized silicon components from different process nodes into a single package to reduce costs and improve yields.
Key Takeaways Microprocessor Market Size & Forecast
The microprocessor market is entering a super-cycle driven by the pervasive integration of Generative AI and the proliferation of the Internet of Things (IoT). Analysis suggests that while traditional PC and smartphone markets provide a stable foundation, the incremental growth is largely derived from the automotive and industrial automation sectors. The forecast period will see a strategic focus on heterogeneous computing, where microprocessors are increasingly paired with integrated neural processing units (NPUs) to handle localized machine learning tasks. Stakeholders are shifting their focus toward supply chain resilience and multi-sourcing strategies to mitigate the risks associated with geopolitical tensions and concentrated manufacturing hubs.
- The Cloud Service Provider (CSP) segment is becoming a primary driver for high-end server microprocessors as the demand for AI training and inference skyrockets.
- Automotive microprocessors are expected to witness a double-digit CAGR as vehicles transition toward Software-Defined Vehicle (SDV) architectures and Level 4/5 autonomy.
- The move toward sustainable computing is pushing manufacturers to prioritize energy efficiency, leading to the development of ultra-low-power microprocessors for edge devices.
- The United States, China, and Taiwan remain the most critical nodes in the global microprocessor value chain, dictating the pace of innovation and supply.
- Heterogeneous integration and advanced 3D packaging technologies are becoming as important as lithography in determining the competitive edge of market leaders.
Microprocessor Market Drivers Analysis
The primary catalysts for the microprocessor market include the exponential growth of data traffic and the subsequent need for high-density server infrastructure. As enterprises migrate to hybrid cloud environments, the demand for processors capable of handling complex multithreaded applications has reached an all-time high. Additionally, the rapid electrification and digitalization of the automotive industry require sophisticated microprocessors for advanced driver assistance systems (ADAS) and infotainment units.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in AI and Machine Learning Workloads | +2.4% | Global (USA and China focus) | 2025 - 2034 |
| Automotive Digitalization and ADAS Integration | +1.5% | Germany, Japan, South Korea | 2026 - 2030 |
| Expansion of 5G and Edge Computing Networks | +1.2% | APAC and North America | 2025 - 2029 |
| IoT Proliferation in Industrial Industry 4.0 | +0.9% | Western Europe and China | 2025 - 2034 |
Microprocessor Market Restraints Analysis
The market faces significant headwinds from the escalating costs associated with sub-5nm fabrication and the physical limitations of silicon-based architectures. Geopolitical trade restrictions and export controls on high-end semiconductor technology also pose a substantial threat to the seamless flow of components across international borders, potentially leading to market fragmentation.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Escalating R&D and Fabrication Costs | -1.1% | Taiwan, South Korea, USA | 2025 - 2034 |
| Geopolitical Trade Barriers and Export Controls | -0.8% | USA-China Trade Corridor | 2025 - 2030 |
| Supply Chain Vulnerabilities and Lead Time Fluctuations | -0.5% | Global | 2025 - 2027 |
Microprocessor Market Opportunities Analysis
The emergence of the RISC-V ecosystem offers a unique opportunity for new entrants and developing nations to build custom, royalty-free processor architectures tailored to specific local needs. Furthermore, the development of gallium nitride (GaN) and silicon carbide (SiC) integration within microprocessor ecosystems presents opportunities for enhanced power management in high-performance applications.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of RISC-V Open Architecture | +1.8% | India, China, European Union | 2026 - 2034 |
| Growth in Wearable Healthcare Devices | +1.1% | North America and Japan | 2025 - 2032 |
| Quantum Computing Hybrid Architectures | +0.6% | USA, Germany, Canada | 2030 - 2034 |
Microprocessor Market Challenges Impact Analysis
Addressing the thermal management of high-density chips remains a critical challenge as power leakage and heat dissipation become major bottlenecks for performance scaling. Additionally, the industry must navigate a complex landscape of cybersecurity threats, requiring the implementation of hardware-level security features within the microprocessor design to protect against sophisticated side-channel attacks.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Thermal Dissipation and Power Density Limits | -0.9% | Global (HPC Segment) | 2025 - 2034 |
| Hardware-Level Cybersecurity Vulnerabilities | -0.7% | North America and Europe | 2025 - 2034 |
| Talent Shortage in VLSI Design | -0.4% | Global | 2025 - 2030 |
Microprocessor Market - Updated Report Scope
This report provides a granular analysis of the global microprocessor market, encompassing architectural shifts, application-specific growth drivers, and a detailed assessment of the competitive landscape across five major geographic regions. The scope includes an evaluation of both general-purpose microprocessors and specialized application-specific integrated circuits (ASICs) that perform microprocessor functions within the broader semiconductor ecosystem.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 110.8 Billion |
| Market Forecast in 2034 | USD 200.2 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Intel Corporation, Advanced Micro Devices (AMD), NVIDIA Corporation, Apple Inc., Qualcomm Technologies, Inc., Samsung Electronics Co., Ltd., Taiwan Semiconductor Manufacturing Company (TSMC), Broadcom Inc., MediaTek Inc., Texas Instruments Incorporated, NXP Semiconductors, STMicroelectronics, IBM Corporation, Renesas Electronics, Arm Holdings (Softbank), Marvell Technology, Inc., Microchip Technology Inc., Infineon Technologies AG, Unisoc, Ampere Computing |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The microprocessor market is segmented based on technology, architecture, core count, and end-user application to provide a comprehensive view of the diverse processing requirements across industries. The transition from general-purpose CPUs to domain-specific architectures is the most significant structural change observed across all segments.
- By Technology: Includes CISC (Complex Instruction Set Computing) dominated by legacy systems, RISC (Reduced Instruction Set Computing) which is the standard for mobile and modern cloud, and specialized ASIC-based processors.
- By Architecture: Features the dominant x86 ecosystem for PCs/Servers, the ubiquitous ARM architecture for mobile/embedded, and the rising RISC-V open-standard architecture.
- By Number of Cores: Ranges from single-core units used in simple embedded systems to many-core processors (64+ cores) utilized in high-performance computing and data centers.
- By Application: Spans Consumer Electronics (Smartphones, Laptops), IT & Telecom (Cloud Servers), Automotive (Infotainment, Autonomous driving), Industrial (Robotics, Control systems), and Defense/Aerospace (Ruggedized processing).
Regional Highlights
- Asia Pacific: Holds the largest market share, driven by the presence of major semiconductor foundries in Taiwan and South Korea, and a massive consumer electronics manufacturing base in China and Southeast Asia.
- North America: The fastest-growing region, characterized by significant investments in AI data centers and the repatriation of semiconductor manufacturing to ensure supply chain security.
- Europe: A critical hub for automotive microprocessors, with Germany and the Netherlands leading in the development of processors for industrial automation and high-end automotive safety systems.
- Latin America & MEA: Emerging markets with increasing demand for entry-level smartphones and digital infrastructure, although growth is moderated by economic volatility and infrastructure gaps.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Microprocessor Market.- Intel Corporation
- Advanced Micro Devices (AMD)
- NVIDIA Corporation
- Apple Inc.
- Qualcomm Technologies, Inc.
- Samsung Electronics Co., Ltd.
- Taiwan Semiconductor Manufacturing Company (TSMC)
- Broadcom Inc.
- MediaTek Inc.
- Texas Instruments Incorporated
- NXP Semiconductors
- STMicroelectronics
- IBM Corporation
- Renesas Electronics
- Arm Holdings
- Marvell Technology, Inc.
- Microchip Technology Inc.
- Infineon Technologies AG
- Unisoc
- Ampere Computing
Frequently Asked Questions
What is the current market size of the global Microprocessor industry?
As of 2025, the market is valued at approximately USD 110.8 Billion, with a projected increase to USD 200.2 Billion by 2034, growing at a CAGR of 6.8%.
Which architecture is expected to grow the fastest during the forecast period?
The ARM architecture and the open-source RISC-V architecture are expected to experience the highest growth rates due to their energy efficiency and customization capabilities for mobile, IoT, and automotive applications.
What are the primary drivers for the Microprocessor market growth?
The main drivers include the rapid adoption of Artificial Intelligence (AI) in data centers, the transition to 5G networks, and the increasing electronic content in modern vehicles (ADAS and Infotainment).
How is the "Chiplet" trend affecting the Microprocessor market?
Chiplet technology allows manufacturers to mix and match components from different process nodes, which optimizes yields, reduces manufacturing costs, and enables more modular and powerful processor designs.
Which region holds the largest share of the Microprocessor market?
The Asia Pacific region currently holds the largest share (over 45%), fueled by dominant manufacturing hubs in Taiwan and South Korea and the vast consumer electronics market in China.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
