Metalworking Equipment Market
Metalworking Equipment Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711752 | Published On : November 15, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Metalworking Equipment Market Size
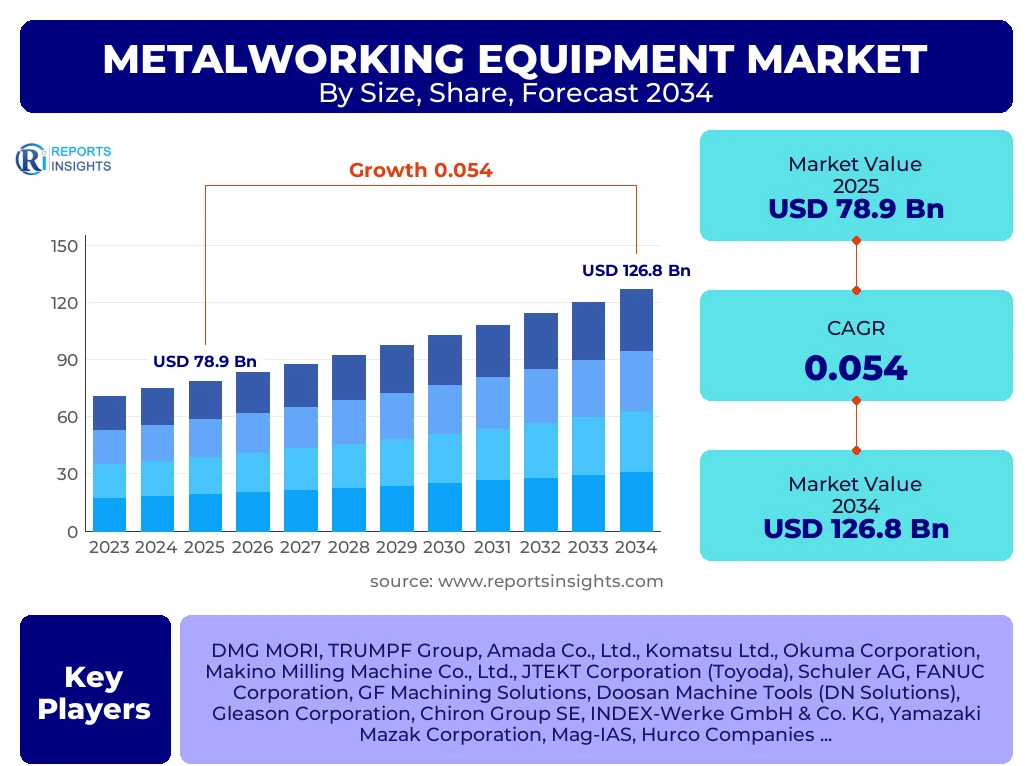
According to Reports Insights Consulting Pvt Ltd, The Metalworking Equipment Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 83.2 Billion in 2026 and is projected to reach USD 126.8 Billion by the end of the forecast period in 2034.
Key Metalworking Equipment Market Trends & Insights
The global metalworking equipment sector is undergoing a profound transformation driven by the integration of Industry 4.0 protocols and the shift toward autonomous manufacturing environments. Analytical data indicates a significant surge in demand for Computer Numerical Control (CNC) machinery that offers multi-axis capabilities, allowing for the fabrication of complex geometries with minimal human intervention. Furthermore, the rise of additive manufacturing, particularly hybrid systems that combine subtractive and additive processes, is redefining production workflows. Market intelligence suggests that sustainability is no longer a peripheral concern but a core strategic pillar, with manufacturers increasingly adopting energy-efficient servo-driven systems and closed-loop coolant recycling technologies to meet stringent environmental regulations and reduce operational expenditures. The competitive landscape is characterized by a move toward software-defined manufacturing, where digital twins and predictive maintenance algorithms enhance equipment longevity and uptime.
- Largest Region: Asia-Pacific remains the dominant global powerhouse, accounting for over 45% of total market revenue due to massive industrial expansion in China, India, and Southeast Asia.
- Fastest Growing Region: South Asia and parts of Latin America are witnessing the highest CAGR, spurred by localized manufacturing incentives and foreign direct investment in the automotive and aerospace sectors.
- Largest Segment by Product: Metal cutting machinery continues to hold the largest market share, driven by the precision requirements of the high-tech electronics and medical device industries.
- Leading Technology Trend: The adoption of Artificial Intelligence (AI) in machine monitoring and real-time tool path optimization is the primary catalyst for modernizing brownfield manufacturing sites.
- Material Innovation: Increasing utilization of high-strength alloys and composites in aerospace is necessitating the development of ultra-rigid, high-torque metalworking equipment.
Key Takeaways Metalworking Equipment Market Size & Forecast
Market projections indicate a robust recovery and expansion phase through 2034, underpinned by the modernization of aging industrial infrastructure in North America and Western Europe. Investors and stakeholders are prioritizing scalability and flexibility in equipment design to accommodate the rapid product lifecycles seen in consumer electronics and electric vehicle (EV) components. The forecast highlights a strategic pivot toward modular machine architectures that allow manufacturers to upgrade specific components without replacing entire systems. Regionally, the emphasis is on "reshoring" and "near-shoring" initiatives, which are creating localized demand for advanced fabrication units. The synergy between high-speed machining and cloud-based data analytics is expected to be the primary revenue driver, facilitating a shift from mass production to mass customization.
- China’s Industrial Dominance: China continues to be the largest single-country consumer and producer of metalworking equipment, supported by the "Made in China 2025" initiative.
- EV Battery Enclosures: The transition to electric mobility is creating a massive requirement for large-scale aluminum extrusion and precision milling equipment for battery housings.
- Decarbonization Impact: Equipment manufacturers are prioritizing the reduction of the carbon footprint of the machines themselves, focusing on reduced material waste and lower energy consumption during operation.
- Labor Shortage Mitigation: The chronic shortage of skilled machinists globally is accelerating the deployment of collaborative robots (cobots) integrated directly into metalworking cells.
- Aerospace Resurgence: Post-pandemic recovery in commercial aviation is fueling orders for high-precision, large-format milling and turning centers.
Metalworking Equipment Market Drivers Analysis
The upward trajectory of the metalworking equipment market is fueled by a confluence of macroeconomic factors and sector-specific technological advancements. High-precision manufacturing requirements in the medical and aerospace fields demand equipment that can operate within sub-micron tolerances, pushing the limits of traditional mechanical engineering. Additionally, the global push for infrastructure modernization—ranging from high-speed rail to renewable energy installations—requires massive quantities of structural metal components, thereby stimulating the demand for heavy-duty metal forming and cutting tools. Government subsidies and tax incentives for digital manufacturing adoption are also playing a critical role in shortening the ROI period for small and medium-sized enterprises (SMEs) investing in high-end CNC systems.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Industry 4.0 and Smart Factory Initiatives | +1.8% | Germany, USA, Japan | 2025-2034 |
| Expansion of the Electric Vehicle (EV) Ecosystem | +1.5% | China, South Korea, Germany | 2026-2030 |
| Growth in Medical Device Manufacturing Precision | +0.9% | Switzerland, USA, Ireland | 2025-2034 |
| Infrastructure Development in Emerging Economies | +1.2% | India, Vietnam, Brazil | 2027-2034 |
Metalworking Equipment Market Restraints Analysis
Despite the optimistic growth outlook, the market faces significant headwinds, primarily related to the high capital expenditure (CAPEX) required for state-of-the-art machinery. Small-scale fabricators often struggle to secure the financing necessary for full-scale automation, leading to a fragmented market where technological laggards face obsolescence. Furthermore, the volatility in raw material prices, particularly for high-grade steel and rare earth elements used in high-efficiency motors, creates pricing pressures for equipment manufacturers. Geopolitical tensions and trade protectionism also disrupt the global flow of critical components, such as semiconductors and precision bearings, leading to extended lead times for new equipment deliveries.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Investment and Maintenance Costs | -1.1% | Global (Specifically SMEs) | 2025-2034 |
| Shortage of Highly Skilled Technical Operators | -0.8% | North America, Western Europe | 2025-2030 |
| Raw Material Price Fluctuations | -0.6% | Global | Short-term (2025-2027) |
Metalworking Equipment Market Opportunities Analysis
The convergence of digital and physical manufacturing presents lucrative opportunities for players who can integrate software-as-a-service (SaaS) models into their equipment offerings. Providing "Machining as a Service" (MaaS) or subscription-based predictive maintenance programs allows manufacturers to build recurring revenue streams while offering customers lower entry barriers. Additionally, the burgeoning green energy sector, specifically the manufacturing of wind turbine components and hydrogen fuel cells, requires specialized large-scale metalworking solutions. The integration of 5G connectivity into factory floors will further enable real-time, low-latency control of remote metalworking fleets, opening doors for decentralized manufacturing hubs.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Hybrid Manufacturing (Additive + Subtractive) | +1.4% | Japan, Germany, USA | 2026-2034 |
| Renewable Energy Component Fabrication | +1.1% | Nordic Countries, China, USA | 2025-2034 |
| Service-Based Business Models (MaaS) | +0.7% | Western Europe, North America | 2027-2034 |
Metalworking Equipment Market Challenges Impact Analysis
The primary challenge lies in the rapid pace of technological obsolescence. As software capabilities evolve faster than mechanical hardware, manufacturers must design equipment that is easily upgradable to prevent systems from becoming redundant within a few years. Environmental compliance also poses a significant hurdle, as governments mandate stricter controls on waste disposal, noise levels, and energy consumption. Furthermore, the cyber-security of connected machine tools has become a critical concern; as equipment becomes more integrated with the cloud, the risk of intellectual property theft and operational sabotage increases, requiring robust digital defense mechanisms within the equipment's architecture.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Risks in Connected Machinery | -0.5% | High-Tech Hubs (USA, Japan, South Korea) | 2025-2034 |
| Stringent Environmental and Emission Regulations | -0.4% | European Union | 2026-2034 |
| Rapid Technological Obsolescence Cycles | -0.7% | Global | 2025-2034 |
Metalworking Equipment Market - Updated Report Scope
The scope of this market analysis covers the entire value chain of metalworking machinery, from primary metal forming to advanced precision finishing. This report provides a granular examination of the shift from manual to fully automated systems, with a particular focus on the integration of digital tools and robotics. The research encompasses diverse industry verticals including automotive, aerospace, heavy machinery, and consumer electronics, analyzing how specific material trends like the shift to aluminum and high-strength titanium are influencing machine design. Strategic insights are provided for both established players seeking to maintain market share and new entrants looking to capitalize on niche technological advancements.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 78.9 Billion |
| Market Forecast in 2034 | USD 126.8 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | DMG MORI, TRUMPF Group, Amada Co., Ltd., Komatsu Ltd., Okuma Corporation, Makino Milling Machine Co., Ltd., JTEKT Corporation (Toyoda), Schuler AG, FANUC Corporation, GF Machining Solutions, Doosan Machine Tools (DN Solutions), Gleason Corporation, Chiron Group SE, INDEX-Werke GmbH & Co. KG, Yamazaki Mazak Corporation, Mag-IAS, Hurco Companies, Inc., Hardinge Inc., Tornos SA. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The metalworking equipment market is segmented by product type, technology, application, and region, reflecting the diverse industrial requirements across global markets. Metal cutting remains the dominant product segment, categorized by its versatility in producing components ranging from micro-electronics to massive engine blocks. Metal forming is seeing a resurgence in demand, particularly for high-speed stamping and precision bending used in the mass production of consumer appliances and EV components. The technological split between CNC and manual machinery is narrowing in favor of CNC, as the cost of automated systems decreases and the demand for repeatable precision increases. Industry-specific applications, particularly in the aerospace and healthcare sectors, are driving the development of specialized niche machinery capable of handling exotic materials like Inconel and medical-grade titanium.
- Metal Cutting Machinery: Includes milling machines, lathes, and grinding units. This segment is bolstered by the demand for high-speed machining and multi-tasking centers that combine several operations into a single setup.
- Metal Forming Machinery: Encompasses presses, shears, and bending machines. Advancements in servo-press technology are enhancing energy efficiency and stroke control in this segment.
- CNC Technology: The standard for modern manufacturing, providing the foundation for automated production lines and integration with CAD/CAM software.
- Automotive Application: The largest end-user segment, transitioning from ICE engine components to EV drivetrain and battery structural elements.
- Aerospace Application: Characterized by high-value, low-volume production requiring extreme precision and the ability to machine hard-to-cut alloys.
- General Machinery: A broad segment covering the production of industrial tools, agricultural equipment, and construction machinery.
Regional Highlights
- Asia-Pacific (APAC): The global epicenter of metalworking equipment, driven by China’s massive domestic manufacturing base and Japan’s leadership in high-end machine tool technology. India is emerging as a high-growth corridor due to the "Make in India" initiative and increasing investments in the defense and railway sectors.
- Europe: A hub for innovation and high-precision machinery, with Germany leading in the production of complex, multi-axis CNC centers. The region is heavily focused on the "Green Deal," pushing for the highest standards of energy efficiency in industrial equipment.
- North America: Market growth is characterized by the modernization of the aerospace and defense sectors and a revitalized interest in domestic semiconductor manufacturing, creating demand for ultra-precise metalworking solutions.
- Latin America: Growth is primarily centered in Mexico and Brazil, serving as regional manufacturing hubs for global automotive OEMs, which drive the demand for standardized metal forming and cutting equipment.
- Middle East & Africa: Emerging demand is tied to economic diversification projects, particularly in Saudi Arabia and the UAE, where investment in localized industrial production is increasing.

Top Key Players
The market research report includes a detailed profile of leading top-wise companies in the Metalworking Equipment Market, focusing on their technological innovations, strategic partnerships, and global market positioning.
- DMG MORI
- TRUMPF Group
- Amada Co., Ltd.
- Komatsu Ltd.
- Okuma Corporation
- Makino Milling Machine Co., Ltd.
- JTEKT Corporation (Toyoda)
- Schuler AG
- FANUC Corporation
- GF Machining Solutions
- DN Solutions (formerly Doosan Machine Tools)
- Gleason Corporation
- Chiron Group SE
- INDEX-Werke GmbH & Co. KG
- Yamazaki Mazak Corporation
- Mag-IAS
- Hurco Companies, Inc.
- Hardinge Inc.
- Tornos SA
- United Grinding Group
Frequently Asked Questions
What is the current market size and projected growth of the metalworking equipment industry?
The global metalworking equipment market is estimated at USD 83.2 Billion in 2026 and is expected to grow at a CAGR of 5.4%, reaching approximately USD 126.8 Billion by 2034. This growth is driven by automation, EV manufacturing, and infrastructure projects.
Which region is leading the metalworking equipment market, and why?
The Asia-Pacific region is the market leader, currently holding over 45% of the global share. This dominance is attributed to the presence of large-scale manufacturing hubs in China and Japan, coupled with rapid industrialization in India and Southeast Asia.
How is Industry 4.0 impacting the design of metalworking machinery?
Industry 4.0 is integrating IoT, AI, and big data into metalworking equipment. This enables real-time monitoring, predictive maintenance, and autonomous operation, significantly reducing downtime and improving the precision of manufacturing processes.
What are the key differences between metal cutting and metal forming equipment?
Metal cutting equipment removes material to create a shape (e.g., milling, turning), while metal forming equipment reshapes material through force without removing it (e.g., bending, pressing). Cutting tools are vital for precision, while forming tools are essential for high-volume structural components.
What are the primary challenges facing manufacturers in this sector?
The major challenges include high capital investment costs, a global shortage of skilled labor, and the need to comply with increasingly stringent environmental and energy-efficiency regulations across different jurisdictions.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
