Metal Powder Market
Metal Powder Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711785 | Published On : November 16, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Metal Powder Market Size
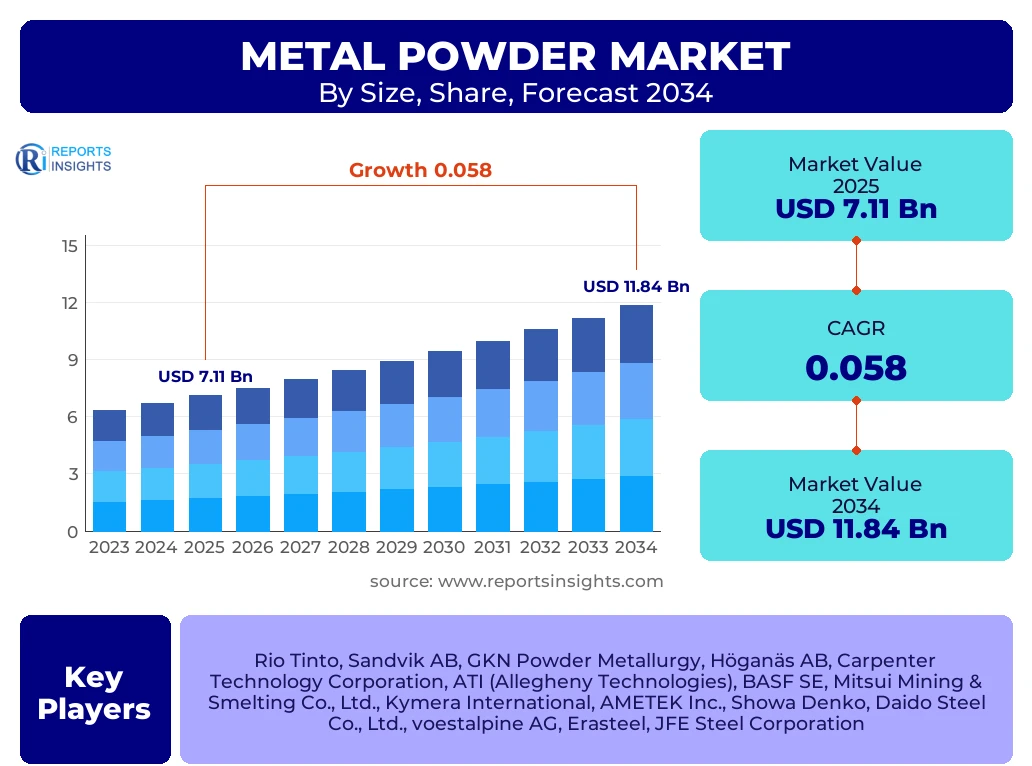
According to Reports Insights Consulting Pvt Ltd, The Metal Powder Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 7.52 Billion in 2026 and is projected to reach USD 11.84 Billion by the end of the forecast period in 2034.
The global valuation of the metal powder industry is increasingly influenced by the convergence of advanced metallurgical techniques and the escalating demand for high-precision components across the automotive and aerospace sectors. As manufacturers pivot toward sustainable production methods, powder metallurgy offers a distinct advantage by reducing material waste compared to traditional subtractive manufacturing processes. This economic and environmental efficiency is a primary catalyst driving the capital investment into atomization technologies and specialized alloy development.
In the coming decade, the integration of additive manufacturing (AM) within industrial supply chains is expected to redefine the volume requirements for spherical powders. While ferrous powders continue to dominate the volume share due to their extensive use in automotive transmission parts and structural components, the high-value segment is rapidly shifting toward non-ferrous and superalloy powders. These materials, including titanium, nickel-based alloys, and aluminum, are critical for the next generation of electric vehicle (EV) batteries, lightweight structural frames, and bio-compatible medical implants, ensuring a robust revenue trajectory through 2034.
Key Metal Powder Market Trends & Insights
The modern metal powder landscape is characterized by a significant shift toward specialization and localized supply chain resilience. Analysts observe that the market is moving away from generic commodity powders toward highly engineered, application-specific materials. This transition is largely dictated by the stringent requirements of 3D printing and laser powder bed fusion (LPBF) technologies, which demand precise particle size distributions and high purity levels to ensure structural integrity in mission-critical applications. Furthermore, regional industrial policies, such as the push for domestic semiconductor and aerospace manufacturing in North America and Asia-Pacific, are reshaping trade flows and production hubs for critical metal precursors.
- Asia-Pacific remains the largest regional market, driven by massive automotive production volumes in China and India.
- North America is the fastest-growing region for high-value specialty powders, particularly titanium and nickel-based alloys for defense and aerospace.
- The Ferrous Metal Powder segment maintains the largest market share by volume, supporting global infrastructure and traditional automotive manufacturing.
- Additive Manufacturing (AM) is the fastest-growing end-use segment, projected to significantly disrupt traditional casting and forging sectors.
- Increasing adoption of green atomization processes using renewable energy to reduce the carbon footprint of powder production is a major corporate ESG trend.
Key Takeaways Metal Powder Market Size & Forecast
The forecast period from 2025 to 2034 highlights a transformative phase where technological maturity in powder production will meet mass-market adoption in the EV and renewable energy sectors. The market is expected to witness a consolidation of players as large-scale chemical and mining conglomerates acquire specialized powder startups to gain a foothold in the high-margin additive manufacturing space. Strategic emphasis is being placed on the circular economy, with significant investments in metal scrap recycling technologies to produce high-quality powder from secondary sources, thereby mitigating the volatility of raw material prices.
- The global market will see a valuation increase of over USD 4 billion between 2026 and 2034, reflecting a stable long-term growth outlook.
- China and the United States are the primary engines of demand, representing nearly 50% of the total market value.
- Automotive remains the dominant end-use industry, although its share is evolving from ICE-engine components to EV drivetrain and thermal management parts.
- Advancements in water and gas atomization are lowering the cost of production, making metal powder solutions more competitive against traditional metalworking.
- Medical technology is emerging as a high-growth niche, specifically for personalized orthopedic implants using titanium powders.
Metal Powder Market Drivers Analysis
The primary driver for the metal powder market is the accelerating transition toward lightweighting in the transportation sector. As global emission standards become more stringent, automotive and aerospace OEMs are compelled to reduce vehicle weight without compromising safety or performance. Metal powder metallurgy allows for the creation of complex, high-strength parts that are significantly lighter than their cast or forged counterparts. Additionally, the rise of the electric vehicle (EV) market has created a new demand stream for specialized copper and cobalt powders used in battery anodes, cathodes, and high-efficiency electric motors.
Furthermore, the industrialization of Additive Manufacturing (AM) is transforming the manufacturing landscape. No longer limited to prototyping, AM is being utilized for serial production of fuel nozzles, heat exchangers, and customized medical tools. This shift requires a consistent and scalable supply of high-quality metal powders. The inherent sustainability of powder-based manufacturing—characterized by near-zero waste and reduced energy consumption during component fabrication—aligns with the global corporate shift toward net-zero targets, providing a long-term macro-economic tailwind for the industry.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Accelerated Adoption of Additive Manufacturing | +1.5% | Global (Strongest in US & Germany) | 2025-2034 |
| EV Battery and Motor Component Demand | +1.2% | China, South Korea, Japan | 2026-2032 |
| Lightweighting Trends in Aerospace | +0.9% | North America, France | 2025-2034 |
| Expansion of Medical Implant Customization | +0.7% | Europe and North America | 2027-2034 |
Metal Powder Market Restraints Analysis
One of the most significant restraints in the metal powder market is the high cost of production associated with specialized powders. Producing spherical, high-purity powders via gas atomization requires substantial capital expenditure and high energy inputs. This makes the final product considerably more expensive than traditional metal forms, limiting its adoption in cost-sensitive industries. Furthermore, the volatility of raw material prices, such as nickel, cobalt, and molybdenum, introduces financial risk for powder producers who must maintain thin margins in a competitive global landscape.
Technical limitations also present challenges to market expansion. The handling and storage of fine metal powders involve significant safety risks, including dust explosions and oxidation, necessitating specialized facilities and strict regulatory compliance. Additionally, the lack of standardized global certifications for 3D-printed metal parts in safety-critical sectors like commercial aviation or nuclear energy can slow down the adoption of powder-based components. These factors combined can act as a bottleneck for small and medium-sized enterprises (SMEs) looking to enter the advanced metallurgy space.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Production Costs of Gas Atomization | -0.6% | Global | 2025-2030 |
| Raw Material Price Volatility (Nickel/Cobalt) | -0.4% | Africa, Latin America | 2025-2029 |
| Strict Safety and Regulatory Standards | -0.3% | EU (REACH Regulations) | 2025-2034 |
Metal Powder Market Opportunities Analysis
The emergence of 4D printing and smart materials represents a burgeoning opportunity for the metal powder market. By utilizing shape-memory alloy powders, manufacturers can create components that react to external stimuli like temperature or pressure. This technology is expected to find applications in advanced robotics, aerospace actuators, and minimally invasive surgical tools. As R&D in this field matures, the demand for high-purity nitinol and other functional alloy powders is expected to surge, offering high-margin opportunities for specialized producers.
Another significant opportunity lies in the "Green Steel" initiative and the decarbonization of the metallurgical industry. Governments are providing subsidies for companies that utilize hydrogen-based reduction of iron ores, which often results in high-quality iron powder as an intermediate or final product. This shift not only aligns with environmental goals but also opens new supply channels for the automotive and construction sectors. Additionally, the expansion of the commercial space sector—led by private entities—creates a steady demand for high-temperature superalloys that can only be effectively processed through powder metallurgy and AM.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Shape Memory Alloys (4D Printing) | +0.8% | United States, Japan | 2028-2034 |
| Hydrogen-Reduced Iron Powder Production | +0.5% | Europe (Sweden, Germany) | 2026-2034 |
| Commercial Space Exploration Components | +0.6% | United States (SpaceX/Blue Origin ecosystem) | 2025-2034 |
| Recycling of E-Waste for Rare Earth Powders | +0.4% | Asia-Pacific, EU | 2027-2034 |
Metal Powder Market Challenges Impact Analysis
Supply chain vulnerability remains a critical challenge, particularly regarding the sourcing of rare earth and refractory metals. Geopolitical tensions can disrupt the supply of materials like tungsten, titanium, and cobalt, leading to sudden price spikes and production delays. Companies are increasingly forced to seek alternative sourcing strategies or invest in vertical integration to secure their supply lines. This geopolitical risk is a constant variable that complicates long-term strategic planning for global metal powder distributors.
Furthermore, the skills gap in advanced metallurgy and additive manufacturing poses a challenge to the widespread adoption of these technologies. Operating sophisticated atomization equipment and optimizing parameters for 3D printing requires a highly specialized workforce. In many regions, the education system has not kept pace with the rapid technological advancements in powder metallurgy, leading to a shortage of qualified engineers and technicians. This human capital bottleneck can hinder the ability of manufacturing firms to scale their powder-based production lines effectively.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Geopolitical Supply Chain Disruptions | -0.5% | Russia, China, Africa | 2025-2028 |
| Shortage of Skilled Metallurgical Personnel | -0.3% | North America, Europe | 2025-2034 |
| Integration Issues with Legacy Manufacturing | -0.2% | Global | 2025-2030 |
Metal Powder Market - Updated Report Scope
The scope of this report encompasses a granular analysis of the global metal powder ecosystem, covering the entire value chain from raw material extraction to end-user applications. The research provides historical data (2020–2024) to establish baseline trends and offers a forward-looking forecast until 2034. It categorizes the market by material type, including ferrous and non-ferrous metals, and by production technology, such as atomization, solid-state reduction, and electrolysis. The report also evaluates the competitive landscape, highlighting the strategic maneuvers of top-tier companies and the emergence of disruptive startups in the additive manufacturing space.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 7.11 Billion |
| Market Forecast in 2034 | USD 11.84 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Rio Tinto, Sandvik AB, GKN Powder Metallurgy, Höganäs AB, Carpenter Technology Corporation, ATI (Allegheny Technologies), BASF SE, Mitsui Mining & Smelting Co., Ltd., Kymera International, AMETEK Inc., Showa Denko, Daido Steel Co., Ltd., voestalpine AG, Erasteel, JFE Steel Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The metal powder market is segmented to provide a comprehensive understanding of the diverse factors influencing growth. Material segmentation reveals a dominant share for ferrous powders, which are essential for structural components in massive industries like construction and traditional automotive. However, non-ferrous powders, particularly titanium and aluminum, are seeing exponential growth in high-tech sectors due to their strength-to-weight ratios. Technology-wise, gas atomization is becoming the gold standard for high-purity spherical powders required in the aerospace industry, while water atomization remains the cost-effective choice for general industrial applications.
- By Material Type:
- Ferrous Metals: Iron, Stainless Steel, Alloy Steel
- Non-Ferrous Metals: Aluminum, Copper, Titanium, Nickel, Cobalt, Tungsten
- By Production Process:
- Physical: Gas Atomization, Water Atomization, Centrifugal Atomization
- Chemical: Solid-State Reduction, Carbonyl Decomposition
- Electrochemical: Electrolysis
- By End-Use Industry:
- Automotive: Transmission parts, engine components, EV motors
- Aerospace & Defense: Turbine blades, structural frames, rocket nozzles
- Healthcare: Orthopedic implants, dental prosthetics
- Electronics: Solder pastes, magnetic cores, heat sinks
- Additive Manufacturing: Prototyping and serial industrial production
Regional Highlights
The Asia-Pacific region continues to lead the global metal powder market, accounting for a significant portion of both production and consumption. China’s role as the "world's factory" ensures a massive demand for iron and steel powders used in the automotive and consumer electronics sectors. Furthermore, India’s burgeoning aerospace sector and government-led infrastructure projects are creating new avenues for market expansion. The presence of major manufacturing hubs and the rapid adoption of new technologies make APAC a central focus for global investors.
In contrast, North America and Europe are pivoting toward high-value, research-intensive segments. The United States is a leader in the development of specialized powders for the defense and space industries, supported by a mature ecosystem of additive manufacturing startups and established aerospace giants. Germany, as the industrial heart of Europe, is driving innovation in automotive powder metallurgy and the transition to green manufacturing processes. These regions are also characterized by strict environmental regulations, which are pushing manufacturers toward more sustainable powder production methods.
- North America: Largest hub for aerospace-grade titanium powder and specialized superalloys.
- Europe: Leading the world in the adoption of green metallurgy and 3D printing standards.
- Asia-Pacific: Fastest-growing market for EV battery materials and traditional iron powders.
- Latin America: Growing demand in the automotive assembly and mining machinery sectors.
- Middle East & Africa: Emerging as a strategic location for metal ore processing and primary powder production.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Metal Powder Market.- Rio Tinto
- Sandvik AB
- GKN Powder Metallurgy
- Höganäs AB
- Carpenter Technology Corporation
- ATI (Allegheny Technologies)
- BASF SE
- Mitsui Mining & Smelting Co., Ltd.
- Kymera International
- AMETEK Inc.
- Showa Denko K.K.
- Daido Steel Co., Ltd.
- voestalpine AG
- Erasteel (Eramet Group)
- JFE Steel Corporation
- Pometon S.p.A.
- Makin Metal Powders
- American Axle & Manufacturing, Inc.
- Carl Schlenk AG
Frequently Asked Questions
What is the current market size of the global metal powder industry?
The global metal powder market is estimated to be worth USD 7.52 Billion in 2026 and is projected to expand at a CAGR of 5.8%, reaching USD 11.84 Billion by 2034. This growth is fueled by advancements in additive manufacturing and the rise of electric vehicles.
Which material segment holds the largest share in the metal powder market?
Ferrous metal powders, including iron and steel, currently hold the largest market share by volume. This is due to their extensive and long-standing use in the automotive, construction, and general engineering sectors for producing high-strength structural parts.
How is Additive Manufacturing impacting the demand for metal powders?
Additive Manufacturing (AM) is a significant growth driver, creating a high-margin demand for spherical, high-purity powders. AM allows for the production of complex geometries that are impossible with traditional methods, leading to increased adoption in aerospace, medical, and high-end automotive sectors.
Which region is expected to grow the fastest in the metal powder market?
While Asia-Pacific remains the largest market by volume, North America is expected to show the fastest growth in terms of market value. This is driven by the rapid industrialization of 3D printing and the heavy presence of the aerospace and defense sectors in the United States.
What are the main production methods used for metal powders?
The primary production methods include water atomization, gas atomization, chemical reduction, and electrolysis. Gas atomization is the preferred method for producing the high-quality, spherical powders required for 3D printing, while water atomization is more commonly used for industrial iron and steel powders.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
