Metal Emblem Logos Market
Metal Emblem Logos Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710979 | Published On : September 24, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Metal Emblem Logos Market Size
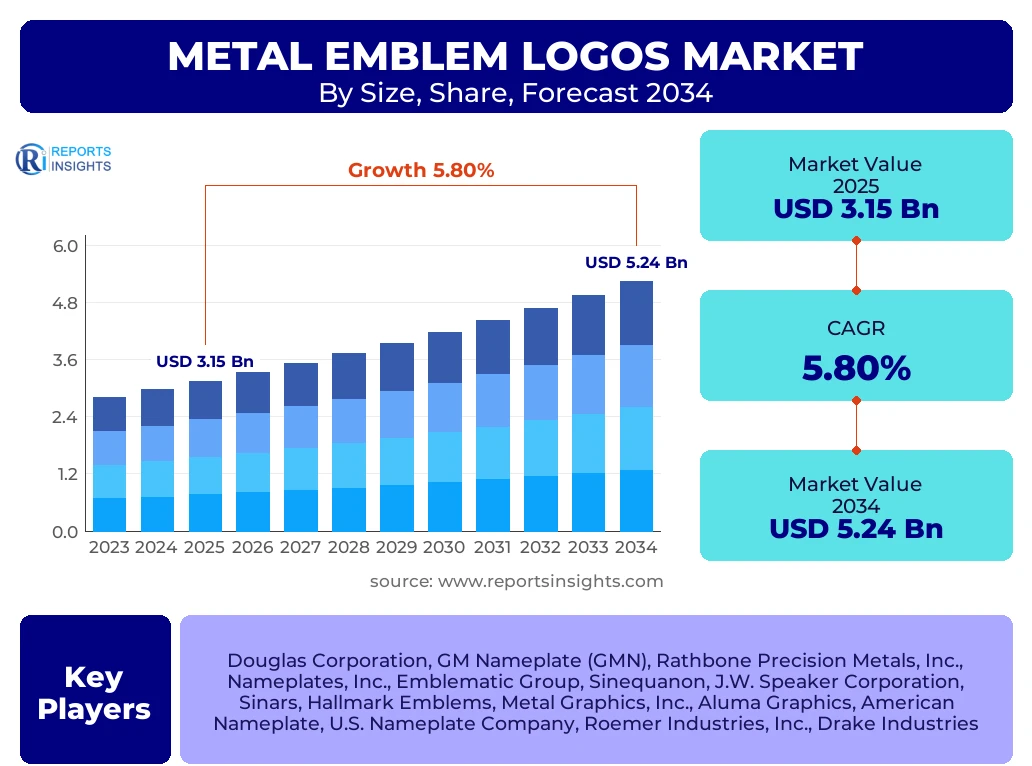
According to Reports Insights Consulting Pvt Ltd, The Metal Emblem Logos Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2026 and 2034. The market is estimated at USD 3.33 Billion in 2026 and is projected to reach USD 5.24 Billion by the end of the forecast period in 2034.
Key Metal Emblem Logos Market Trends & Insights
The global metal emblem logos market is undergoing a significant transformation driven by the rising demand for premium aesthetics in the automotive and consumer electronics sectors. Users and enterprise stakeholders are increasingly querying the shift toward sustainable manufacturing processes, specifically focusing on eco-friendly electroplating and the use of recycled aluminum. The market is witnessing a move from traditional stamping methods to high-precision CNC machining and 3D metal printing, which allows for more intricate designs and localized customization. Furthermore, the integration of smart technologies, such as NFC-enabled metal emblems for brand authentication and anti-counterfeiting, is emerging as a critical trend in the luxury goods segment.
- Largest Region: Asia-Pacific remains the largest market due to the concentration of automotive manufacturing and consumer electronics production in China, Japan, and South Korea.
- Fastest Growing Region: North America is expected to exhibit the fastest growth rate, fueled by the resurgence of domestic luxury manufacturing and the rapid expansion of the electric vehicle (EV) sector.
- Largest Segment by Material: Aluminum emblems currently hold the largest market share due to their lightweight properties, corrosion resistance, and cost-effectiveness.
- Leading End-Use Industry: The Automotive industry continues to dominate the market share, driven by the branding requirements of both traditional internal combustion engine vehicles and new-age electric mobility solutions.
Key Takeaways Metal Emblem Logos Market Size & Forecast
The forecast for the metal emblem logos market suggests a period of steady expansion as brands across various verticals seek to differentiate themselves through tactile, high-quality physical identifiers. Analysis of market data indicates that the shift toward premiumization in emerging economies is a primary catalyst for volume growth. Stakeholders are particularly focused on the durability and longevity of metal emblems compared to plastic alternatives, which aligns with the global trend toward high-quality, long-lasting consumer products. The forecast period will likely see a convergence of traditional metallurgy and digital manufacturing techniques to meet the increasing demand for short-run, customized emblem production.
- Growth Driver: The global luxury goods market expansion is a key pillar for the demand for high-end metal branding solutions.
- Dominant Material: Stainless steel is gaining traction in the luxury segment due to its superior finish and perceived value.
- Technological Shift: The adoption of Physical Vapor Deposition (PVD) coating is replacing traditional chrome plating to meet stringent environmental regulations.
- Strategic Market Focus: Key players are focusing on vertical integration to control the supply chain from raw material procurement to final finishing.
Metal Emblem Logos Market Drivers Analysis
The growth of the metal emblem logos market is primarily propelled by the automotive industry's focus on brand identity and the consumer electronics sector's drive for premiumization. As electric vehicles become more prevalent, manufacturers are utilizing illuminated and high-relief metal emblems to signal technological sophistication. Additionally, the rise of the luxury fashion and accessories market necessitates high-durability logos that can withstand environmental wear while maintaining aesthetic integrity. The psychological impact of metal as a "premium" material significantly influences consumer purchasing decisions in the appliance and hardware sectors.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Premiumization of Automotive Branding | +1.5% | Global (Strongest in Germany and USA) | 2025 - 2034 |
| Expansion of Electric Vehicle (EV) Sector | +1.2% | China, USA, and Norway | 2026 - 2032 |
| Demand for Sustainable & Recyclable Materials | +0.8% | European Union | 2025 - 2030 |
Metal Emblem Logos Market Restraints Analysis
While the market is growing, it faces challenges from the volatility of raw material prices, particularly for nickel, chromium, and aluminum. Strict environmental regulations regarding electroplating and chemical waste management in developed regions are forcing manufacturers to invest heavily in cleaner technologies, which can increase production costs. Furthermore, the rising popularity of digital branding and minimalist design trends in certain consumer tech segments may reduce the physical size or frequency of metal emblem usage in some product categories.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -0.6% | Global | Short to Medium Term |
| Stringent Environmental Regulations | -0.4% | Europe and North America | 2025 - 2034 |
Metal Emblem Logos Market Opportunities Analysis
There are significant opportunities in the development of "smart emblems" that incorporate NFC or RFID chips for brand verification and consumer interaction. This technology is particularly valuable for the high-end spirits and luxury handbag markets to combat counterfeiting. Another opportunity lies in the advancement of additive manufacturing (3D printing) for metal emblems, allowing for rapid prototyping and the production of highly complex, low-volume custom designs for the aftermarket automotive and bespoke luxury segments.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Smart Emblems (NFC/RFID Integration) | +0.9% | France, Italy, and USA | 2027 - 2034 |
| 3D Printing for Customization | +0.7% | Global | 2026 - 2034 |
Metal Emblem Logos Market Challenges Impact Analysis
The primary challenge for the metal emblem logos market is the competition from high-quality plastic composites and metallized polymers that offer similar aesthetics at a lower cost. Additionally, maintaining color consistency and adhesive durability across diverse environmental conditions (e.g., extreme heat, salt spray) remains a technical hurdle for manufacturers catering to the global automotive and marine industries. Supply chain disruptions for specialized coating chemicals also pose a risk to production timelines.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Metallized Plastics | -0.5% | Global | 2025 - 2034 |
| Adhesion and Longevity in Extreme Climates | -0.3% | Middle East and Nordic Regions | Ongoing |
Metal Emblem Logos Market - Updated Report Scope
This comprehensive market research report provides an in-depth analysis of the metal emblem logos industry, covering the global landscape across multiple dimensions including material type, manufacturing process, and end-use applications. The scope encompasses the entire value chain from raw material suppliers to specialized finishing houses and end-market distributors. The report offers a granular look at the competitive dynamics, regulatory environment, and technological advancements that are shaping the future of branding hardware. By analyzing historical data from 2020 to 2024, the report establishes a robust baseline for the forecast period ending in 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.15 Billion |
| Market Forecast in 2034 | USD 5.24 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Douglas Corporation, GM Nameplate (GMN), Rathbone Precision Metals, Inc., Nameplates, Inc., Emblematic Group, Sinequanon, J.W. Speaker Corporation, Sinars, Hallmark Emblems, Metal Graphics, Inc., Aluma Graphics, American Nameplate, U.S. Nameplate Company, Roemer Industries, Inc., Drake Industries |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The metal emblem logos market is segmented based on material, production process, and end-user application to provide a detailed understanding of the market dynamics. Material selection is critical, with aluminum leading the volume market while stainless steel and brass target the premium and luxury tiers. The production process segment reveals a shift toward die-casting for high-volume automotive parts, whereas etching and electroforming are preferred for the high-detail requirements of consumer electronics and luxury accessories. End-use segmentation highlights the dominance of the automotive sector, followed by the rapid growth in home appliances and personal electronics.
- By Material Type:
- Aluminum: Highly favored for its light weight and versatility in the automotive and appliance sectors.
- Stainless Steel: Preferred for high-durability and premium aesthetic applications in luxury branding.
- Zinc Alloy: Commonly used for die-cast emblems requiring complex 3D shapes.
- Brass & Copper: Used primarily in heritage branding and high-end fashion accessories.
- By Manufacturing Process:
- Die-Casting: The standard for large-scale, durable 3D emblems.
- Stamping: Cost-effective for high-volume, flat or semi-3D metal logos.
- Chemical Etching: Ideal for ultra-thin, highly detailed logos used in electronics.
- Electroforming: Used for high-precision, intricate logos with a premium metallic finish.
- By End-Use Industry:
- Automotive: Exterior and interior branding for passenger and commercial vehicles.
- Consumer Electronics: Logos for laptops, smartphones, and premium audio equipment.
- Household Appliances: Branding for refrigerators, ovens, and luxury kitchen gadgets.
- Fashion & Luxury Goods: Emblems for handbags, footwear, and premium luggage.
Regional Highlights
- Asia-Pacific: Dominates the global market with over 40% share, driven by massive manufacturing hubs in China and India and the presence of leading electronics giants in Japan and South Korea.
- North America: The fastest-growing region, supported by the premiumization of the automotive sector and a surge in luxury consumer goods startups focusing on high-quality hardware.
- Europe: Holds a significant market position due to the presence of luxury automotive brands (e.g., BMW, Mercedes-Benz, Ferrari) and high-end fashion houses in Italy and France that demand top-tier metal emblems.
- Middle East & Africa: Emerging as a growth pocket for luxury branding in the construction and hospitality hardware sectors, as well as the bespoke automotive aftermarket.
- Latin America: Showing steady growth in the household appliance and automotive assembly sectors, particularly in Brazil and Mexico.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Metal Emblem Logos Market.- Douglas Corporation
- GM Nameplate (GMN)
- Rathbone Precision Metals, Inc.
- Nameplates, Inc.
- Emblematic Group
- Sinequanon
- J.W. Speaker Corporation
- Sinars
- Hallmark Emblems
- Metal Graphics, Inc.
- Aluma Graphics
- American Nameplate
- U.S. Nameplate Company
- Roemer Industries, Inc.
- Drake Industries
- Durable Mevements Ltd.
- Nelson-Miller, Inc.
- McLoone
- Clarion Safety Systems
- Techno-Graphics
Frequently Asked Questions
What is driving the growth of the metal emblem logos market?
Growth is primarily driven by the "premiumization" trend across the automotive and consumer electronics sectors, where metal is preferred over plastic to convey quality, durability, and luxury. The rise of electric vehicles and smart branding also contributes significantly.
Which material is most commonly used for metal emblems?
Aluminum is the most commonly used material due to its excellent balance of weight, corrosion resistance, and cost-effectiveness, making it suitable for both high-volume automotive and consumer appliance applications.
How is environmental regulation affecting the market?
Environmental regulations are pushing manufacturers away from traditional chrome plating toward cleaner technologies like Physical Vapor Deposition (PVD) and eco-friendly electroplating to reduce chemical waste and toxic emissions.
What are "Smart Emblems"?
Smart emblems are metal logos integrated with NFC (Near Field Communication) or RFID chips, allowing consumers to verify product authenticity via smartphone and enabling brands to engage with customers through digital content.
Which region offers the most growth opportunities for manufacturers?
While Asia-Pacific is the largest producer, North America and Europe offer the most significant growth in high-margin luxury segments and advanced technological integrations, specifically for the EV and high-end electronics markets.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted