Medical Foods Market
Medical Foods Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711422 | Published On : November 01, 2026 |
Format : 


 | Author : Erika Grotto
Medical Foods Market Size
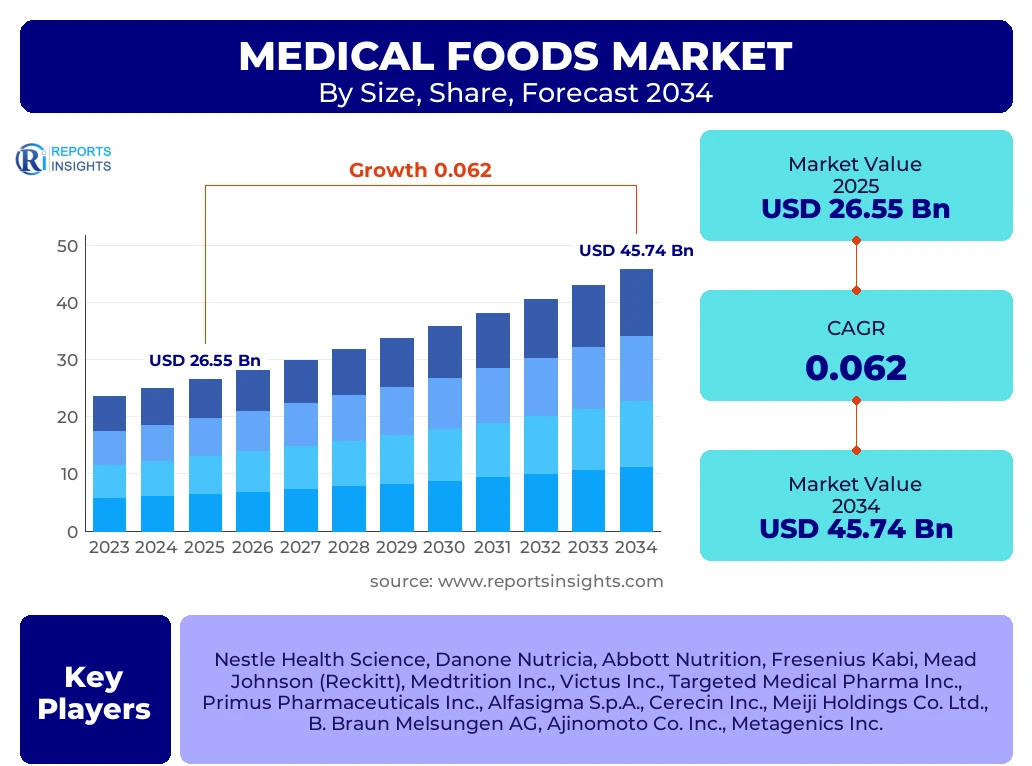
According to Reports Insights Consulting Pvt Ltd, The Medical Foods Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 28.20 Billion in 2026 and is projected to reach USD 45.74 Billion by the end of the forecast period in 2034.
Key Medical Foods Market Trends & Insights
The medical foods market is undergoing a significant transformation driven by the integration of personalized nutrition and the rising prevalence of chronic conditions requiring specialized dietary management. Stakeholders are increasingly focusing on clinical validation and the development of targeted formulations for metabolic disorders, neurological conditions, and oncology-related nutritional deficiencies. Market intelligence suggests that the shift from institutional care to home-based healthcare is a primary catalyst for growth in retail and e-commerce distribution channels. Furthermore, the convergence of biotechnology and food science is enabling the creation of more effective, palatable, and patient-specific medical foods that cater to diverse age groups and physiological needs.
- Largest Region: North America remains the dominant market owing to an established regulatory framework, high healthcare expenditure, and a proactive approach toward clinical nutrition.
- Fastest Growing Region: Asia-Pacific is expected to exhibit the highest CAGR due to a rapidly aging population, increasing awareness of chronic disease management, and expanding healthcare infrastructure in countries like China and India.
- Largest Segment: The metabolic disorders segment currently holds the largest market share, driven by the increasing incidence of inherited metabolic diseases and the mandatory clinical requirement for specialized nutrition in these patients.
- Emerging Trend: The adoption of enteral nutrition in home-care settings is gaining traction, reducing the burden on hospitals while ensuring continuous nutritional support for patients with chronic illnesses.
Key Takeaways Medical Foods Market Size & Forecast
The market trajectory for medical foods indicates a robust expansion phase as global healthcare systems pivot toward value-based care and preventative nutritional interventions. Advanced data analytics and genomic research are helping manufacturers identify specific nutrient gaps in patient populations, leading to the development of highly specialized products for conditions like Alzheimers disease and diabetic neuropathy. The forecast period anticipates a substantial increase in R&D investments aimed at improving the sensory profiles of medical foods, which has historically been a barrier to patient compliance. Strategic collaborations between pharmaceutical companies and nutrition experts are expected to redefine the competitive landscape, fostering innovation in delivery mechanisms and ingredient sourcing.
- Growth Driver: The global surge in the geriatric population is a critical factor, as elderly patients are more prone to chronic diseases requiring medical-grade nutritional support.
- Leading Country: The United States leads the global market in terms of value, supported by favorable reimbursement policies for enteral nutrition and a high concentration of key industry players.
- Product Dominance: Liquid and powder formulations continue to lead the market due to their ease of administration, particularly for patients with dysphagia or those requiring tube feeding.
- Strategic Shift: Companies are increasingly targeting the e-commerce sector to enhance accessibility for outpatients, bypassing traditional pharmacy constraints.
Medical Foods Market Drivers Analysis
The primary driver for the medical foods market is the escalating global burden of chronic diseases such as cancer, diabetes, and cardiovascular disorders. These conditions often lead to nutritional deficiencies that cannot be corrected through a standard diet alone. Medical foods are formulated to meet the specific nutritional requirements of patients under medical supervision, providing a clinical advantage in managing symptoms and improving overall health outcomes. As clinicians increasingly recognize the role of nutrition in therapy, the prescription rate for medical foods is witnessing a steady rise across both developed and developing economies.
Furthermore, the demographic shift toward an aging population significantly bolsters demand. Older adults frequently suffer from sarcopenia, malabsorption, and cognitive decline, all of which necessitate specialized dietary interventions. Technological advancements in food processing and the ability to isolate specific bio-active compounds have allowed for the creation of more potent and targeted medical food products. This technological evolution, combined with a supportive regulatory environment in regions like North America and Europe, provides a fertile ground for market expansion.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Chronic Diseases | +2.1% | Global | 2025-2034 |
| Expansion of the Geriatric Population | +1.8% | Europe and Japan | 2025-2034 |
| Advancements in Food Biotechnology | +1.2% | North America | 2026-2030 |
| Shift to Home Healthcare Models | +1.1% | USA and China | 2025-2034 |
Medical Foods Market Restraints Analysis
Despite the positive growth outlook, the medical foods market faces several restraints, most notably the high cost associated with specialized formulations. These products require extensive research, clinical trials, and high-quality raw materials, making them significantly more expensive than standard dietary supplements. In many developing regions, the lack of comprehensive insurance coverage or reimbursement for medical foods limits patient access and inhibits market penetration. This financial barrier is particularly acute for patients requiring long-term nutritional support for rare metabolic disorders.
Additionally, regulatory complexities present a significant hurdle for manufacturers. While medical foods are distinct from drugs and dietary supplements, the requirements for clinical evidence and labeling vary considerably across jurisdictions. Navigating these diverse regulatory landscapes can be time-consuming and costly, potentially delaying the launch of innovative products. Furthermore, a lack of awareness among both healthcare professionals and patients regarding the specific benefits and proper use of medical foods can lead to under-utilization in certain therapeutic areas.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Specialized Formulations | -1.3% | Emerging Markets | 2025-2034 |
| Stringent and Varied Regulatory Requirements | -0.9% | European Union | 2025-2030 |
| Limited Reimbursement Policies | -1.1% | Global | 2025-2034 |
Medical Foods Market Opportunities Analysis
The emergence of personalized medicine offers a massive opportunity for the medical foods market. Advances in nutrigenomics and metabolomics are enabling the development of products tailored to an individuals unique genetic makeup and metabolic needs. This shift toward precision nutrition allows for more effective management of complex diseases and offers a competitive edge to companies capable of integrating diagnostic tools with nutritional solutions. Strategic partnerships between food tech startups and established pharmaceutical firms are likely to accelerate this trend.
Furthermore, the rapid growth of digital health and e-commerce platforms provides a new frontier for distribution. Direct-to-consumer models allow manufacturers to educate patients and caregivers directly, improving brand loyalty and ensuring better compliance. Expansion into emerging economies in Southeast Asia and Latin America also presents significant potential, as rising middle-class incomes and improving healthcare standards increase the demand for high-quality clinical nutrition products.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Personalized and Precision Nutrition | +1.9% | USA and Germany | 2027-2034 |
| Growth of E-commerce Distribution | +1.4% | APAC Region | 2025-2034 |
| Emerging Market Expansion | +1.6% | Brazil and India | 2026-2034 |
Medical Foods Market Challenges Impact Analysis
One of the most persistent challenges in the medical foods market is the sensory appeal of specialized products. Many formulations, particularly those high in amino acids or specific fatty acids, have an unpleasant taste or texture, which can lead to poor patient adherence. Improving the organoleptic properties without compromising the therapeutic efficacy remains a major technical challenge for R&D teams. Additionally, the confusion between medical foods and dietary supplements in the minds of consumers and some healthcare providers can lead to the substitution of clinically validated products with less effective alternatives.
Supply chain stability for high-purity ingredients is another concern. The production of medical foods often relies on specific, high-grade components that are sensitive to market fluctuations and global trade disruptions. Ensuring a consistent supply of these ingredients while maintaining strict quality control standards is essential for market stability. Furthermore, the increasing competition from functional foods and specialized pharmaceuticals requires medical food manufacturers to continuously demonstrate the unique value proposition of their products through rigorous clinical evidence.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Palatability and Patient Compliance Issues | -0.7% | Global | 2025-2034 |
| Market Confusion with Dietary Supplements | -0.5% | Global | 2025-2030 |
| Supply Chain Volatility for Specialty Ingredients | -0.4% | Global | 2025-2028 |
Medical Foods Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global medical foods industry, covering various product forms, therapeutic applications, and administration routes. The study evaluates the market dynamics across major geographic regions, identifying key growth pockets and competitive pressures. By integrating historical data with current market trends, the report provides a comprehensive forecast of market value and CAGR through 2034, offering actionable insights for investors, manufacturers, and healthcare stakeholders. It also examines the impact of regulatory shifts and technological innovations on the future of clinical nutrition.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 26.55 Billion |
| Market Forecast in 2034 | USD 45.74 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Nestle Health Science, Danone Nutricia, Abbott Nutrition, Fresenius Kabi, Mead Johnson (Reckitt), Medtrition Inc., Victus Inc., Targeted Medical Pharma Inc., Primus Pharmaceuticals Inc., Alfasigma S.p.A., Cerecin Inc., Meiji Holdings Co. Ltd., B. Braun Melsungen AG, Ajinomoto Co. Inc., Metagenics Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The medical foods market is multifaceted, segmented primarily by product type, administration route, and therapeutic application. Powdered formulations represent a significant share due to their long shelf life and versatility in dosage adjustment. Liquid formulations are increasingly preferred for patients requiring enteral feeding or those with significant swallowing difficulties. The therapeutic segmentation highlights the dominance of metabolic and neurological disorders, where medical foods are often the primary mode of management. Recent trends suggest a growing share for oncology-related medical foods as healthcare providers focus on improving the quality of life and treatment tolerance for cancer patients through rigorous nutritional support.
- By Product Type:
- Powder
- Liquid
- Pills
- Semi-solid (Gels and Puddings)
- By Route of Administration:
- Oral
- Enteral (Tube Feeding)
- By Application:
- Chronic Kidney Disease (CKD)
- Inherited Metabolic Disorders (PKU, MSUD, etc.)
- Neurological Conditions (Alzheimer’s, Dementia)
- Diabetic Neuropathy
- Oncology Nutrition
- Gastrointestinal Disorders
- Other Chronic Conditions
- By Sales Channel:
- Institutional (Hospitals and Care Homes)
- Retail (Pharmacies and Health Stores)
- Online (E-commerce and Direct-to-Patient)
Regional Highlights
North America continues to be the largest market for medical foods, driven by a sophisticated healthcare ecosystem and high awareness among clinical practitioners. The presence of major industry leaders and a well-defined regulatory path provided by the FDA ensures a steady stream of new product launches. In the United States, the rising prevalence of obesity-linked chronic diseases and the aging baby boomer population are significant catalysts. Furthermore, the reimbursement for enteral nutrition under Medicare and private insurance provides a stable foundation for market growth.
The Asia-Pacific region is identified as the fastest-growing market. This growth is fueled by a massive demographic shift in countries like Japan and China, where the geriatric population is increasing at an unprecedented rate. Governments in this region are increasingly investing in healthcare infrastructure and promoting the use of specialized nutrition to reduce the overall burden on hospitals. In Europe, the market is characterized by stringent regulations and a strong emphasis on clinical evidence, with Germany, France, and the UK leading in research and development. Latin America and the MEA region are expected to show steady growth as medical awareness improves and healthcare spending increases.
- North America: Market leader with highest value share; driven by advanced clinical adoption and established insurance reimbursement frameworks.
- Europe: Focused on high-quality clinical validation and specialized products for rare metabolic diseases.
- Asia-Pacific: Highest growth potential due to aging populations in Japan/China and rising healthcare access in Southeast Asia.
- Latin America: Emerging market with increasing demand for pediatric and geriatric nutritional products.
- Middle East & Africa: Growing focus on managing metabolic disorders and chronic diseases in urban centers.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Medical Foods Market.- Nestle Health Science
- Danone Nutricia
- Abbott Nutrition
- Fresenius Kabi
- Mead Johnson (Reckitt)
- Medtrition Inc.
- Victus Inc.
- Targeted Medical Pharma Inc.
- Primus Pharmaceuticals Inc.
- Alfasigma S.p.A.
- Cerecin Inc.
- Meiji Holdings Co. Ltd.
- B. Braun Melsungen AG
- Ajinomoto Co. Inc.
- Metagenics Inc.
- Solace Nutrition
- Galen Limited
- Kate Farms
- Relief Therapeutics
Frequently Asked Questions
What exactly defines a product as a medical food?
A medical food is a product formulated to be consumed or administered enterally under the supervision of a physician and which is intended for the specific dietary management of a disease or condition for which distinctive nutritional requirements, based on recognized scientific principles, are established by medical evaluation.
How do medical foods differ from standard dietary supplements?
Unlike dietary supplements, which are intended for healthy individuals to supplement their diet, medical foods are specifically intended for the dietary management of a disease or condition. They require medical supervision and must be backed by clinical data demonstrating their effectiveness in meeting distinctive nutritional needs.
What are the key drivers for the medical foods market growth through 2034?
The primary drivers include the rising global incidence of chronic diseases, a growing geriatric population requiring specialized care, technological advancements in nutrient delivery, and a shift toward home-based healthcare services.
Is insurance reimbursement available for medical foods?
Reimbursement varies significantly by region and insurance provider. In many cases, enteral nutrition and certain medical foods for metabolic disorders are covered, but coverage for oral medical foods can be more limited and often requires specific clinical documentation.
Which therapeutic area holds the largest share of the medical foods market?
Metabolic disorders currently hold the largest share due to the lifelong necessity of specialized diets for conditions like Phenylketonuria (PKU). However, the oncology and neurological segments are growing rapidly as nutrition becomes a central part of holistic disease management.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
