Medical Equipment Maintenance Market
Medical Equipment Maintenance Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711338 | Published On : October 28, 2026 |
Format : 


 | Author : Erika Grotto
Medical Equipment Maintenance Market Size
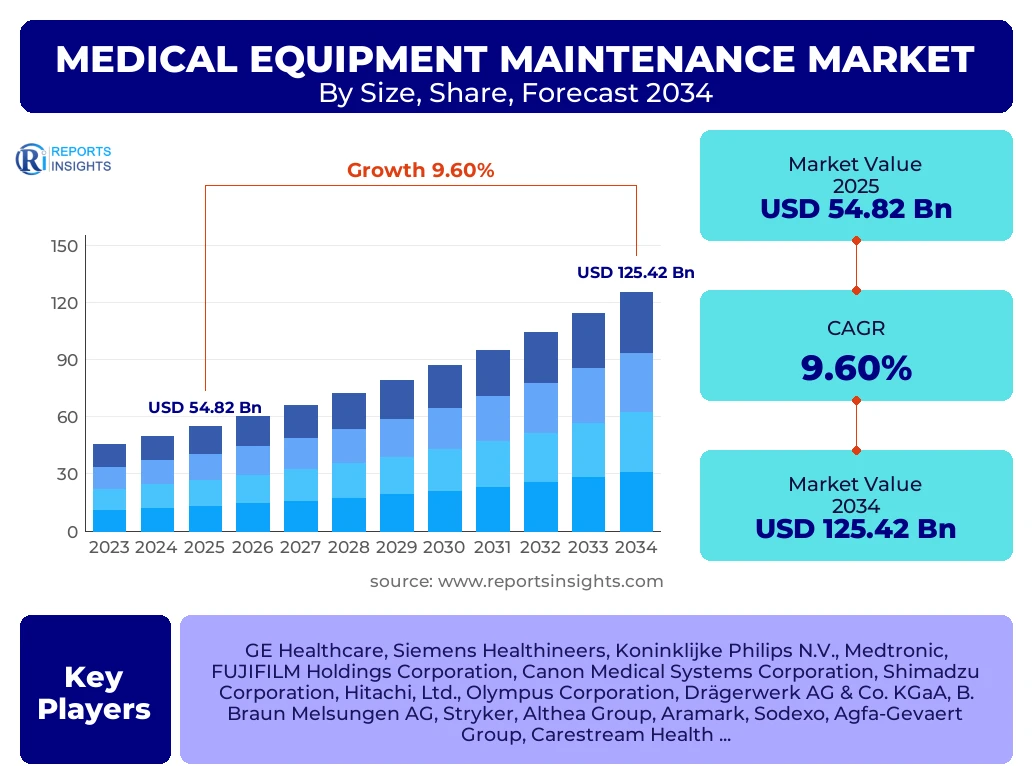
According to Reports Insights Consulting Pvt Ltd, The Medical Equipment Maintenance Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.6% between 2025 and 2034. The market is estimated at USD 60.08 Billion in 2026 and is projected to reach USD 125.42 Billion by the end of the forecast period in 2034.
Key Medical Equipment Maintenance Market Trends & Insights
The global medical equipment maintenance market is undergoing a significant transformation driven by the integration of advanced digital technologies and a shift in hospital procurement strategies. Modern healthcare facilities are increasingly moving away from reactive maintenance models toward proactive and predictive strategies enabled by the Internet of Medical Things (IoMT). By leveraging real-time data from connected devices, service providers can now identify potential failures before they occur, significantly reducing equipment downtime and improving patient safety. Furthermore, the rise of Independent Service Organizations (ISOs) is challenging the traditional dominance of Original Equipment Manufacturers (OEMs), as healthcare providers seek more cost-effective and flexible multi-vendor service contracts to manage diverse equipment fleets.
Regional variations in market dynamics are pronounced, with North America maintaining the largest market share due to its advanced healthcare infrastructure and stringent regulatory environment regarding equipment safety. Conversely, the Asia-Pacific region is emerging as the fastest-growing market, fueled by massive investments in healthcare facilities across China and India, alongside a growing awareness of the long-term cost benefits associated with regular equipment servicing. Strategic partnerships and acquisitions are also on the rise, as major players look to expand their service portfolios and geographic reach to cater to the increasing demand for specialized maintenance in high-end imaging and surgical equipment segments.
- North America is the largest regional market, supported by the presence of major medical device manufacturers and high healthcare expenditure.
- Asia-Pacific is the fastest-growing region, driven by rapid healthcare infrastructure expansion and a rising geriatric population.
- The Imaging Equipment segment holds the largest market share due to the high complexity and frequent maintenance requirements of MRI, CT, and X-ray systems.
- Preventive maintenance is the dominant service type as healthcare providers prioritize the longevity of expensive medical assets.
- Independent Service Organizations (ISOs) are gaining significant traction in the market due to their ability to offer lower-cost, multi-brand service solutions.
Key Takeaways Medical Equipment Maintenance Market Size & Forecast
The market trajectory for medical equipment maintenance is characterized by robust growth as healthcare systems worldwide face increasing pressure to optimize operational efficiency and maximize the lifecycle of high-cost capital equipment. The convergence of high-tech medical devices and the necessity for uninterrupted clinical workflows has made maintenance a critical component of healthcare management. As diagnostic imaging and surgical robotics become more prevalent, the demand for specialized technical expertise and precision calibration is expected to surge, further buoying the market valuation through 2034.
- The global market value is expected to more than double by 2034, reflecting the increasing reliance on complex medical technologies.
- The United States and Germany remain leading countries in terms of technical innovation and the adoption of advanced maintenance protocols.
- Predictive maintenance, powered by artificial intelligence, is set to become the industry standard, replacing older, less efficient corrective maintenance models.
- Hospitals remain the primary end-user segment, although diagnostic centers and ambulatory surgical centers are showing rapid growth in maintenance demand.
- Strict adherence to international quality standards such as ISO 13485 is a critical differentiator for service providers in a highly competitive landscape.
Medical Equipment Maintenance Market Drivers Analysis
The primary driver for the medical equipment maintenance market is the global increase in the volume of diagnostic procedures, particularly imaging. As the global population ages, there is a higher prevalence of chronic diseases requiring frequent monitoring and intervention. This necessitates the constant availability of functional medical equipment. Additionally, the rapid pace of technological innovation in medical devices means that systems are becoming more sensitive and complex, requiring specialized maintenance that only expert technicians can provide. Government regulations regarding the safety and efficacy of medical devices also mandate regular inspections, compelling healthcare facilities to invest in comprehensive maintenance contracts.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rise in Geriatric Population and Chronic Diseases | +2.8% | Global (Strongest in Japan & Europe) | 2025 - 2034 |
| Stringent Regulatory Standards for Patient Safety | +2.1% | North America & European Union | 2025 - 2030 |
| Adoption of AI-driven Predictive Maintenance | +2.4% | United States, China, South Korea | 2026 - 2034 |
| Growth in Multi-vendor Service Contracts | +1.8% | North America & Latin America | 2025 - 2032 |
Medical Equipment Maintenance Market Restraints Analysis
The high cost of maintenance services and specialized spare parts remains a significant barrier, particularly for small-scale clinics and hospitals in developing economies. Many facilities operate on tight budgets and may delay non-critical maintenance, which can lead to equipment failure and higher long-term costs. Furthermore, the lack of a standardized regulatory framework for Independent Service Organizations in certain regions can lead to concerns regarding the quality and reliability of third-party repairs. The complexity of modern medical software also creates barriers for non-OEM providers who may not have access to proprietary diagnostic tools or software updates.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Costs of Spare Parts and Labor | -1.5% | Global (High impact in MEA) | 2025 - 2034 |
| Limited Access to Proprietary OEM Software | -1.2% | Global | 2025 - 2030 |
| Shortage of Skilled Biomedical Engineers | -0.9% | Asia-Pacific & Latin America | 2026 - 2034 |
Medical Equipment Maintenance Market Opportunities Analysis
The expansion of healthcare infrastructure in emerging markets offers a fertile ground for maintenance service providers. As governments in the APAC and MEA regions increase their healthcare spending, new hospitals and diagnostic centers are being established, all requiring long-term maintenance support. There is also a massive opportunity in the refurbishment of medical equipment. As cost-conscious facilities look for alternatives to brand-new devices, the demand for high-quality refurbishment and subsequent maintenance of pre-owned equipment is rising. Additionally, the integration of remote diagnostic capabilities allows service providers to offer faster response times and reduce the need for on-site visits, opening new revenue streams in digital service delivery.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Emerging Markets (India, Brazil, Indonesia) | +3.2% | APAC, Latin America | 2026 - 2034 |
| Remote Service and Tele-maintenance Solutions | +2.5% | North America & Europe | 2025 - 2034 |
| Focus on Refurbished Medical Equipment Services | +1.9% | Global | 2025 - 2032 |
Medical Equipment Maintenance Market Challenges Impact Analysis
One of the most pressing challenges is the rapid rate of obsolescence in medical technology. Keeping technical staff trained on the latest iterations of complex systems like robotic surgical platforms or advanced molecular imaging is both time-consuming and expensive. Cybersecurity also presents a major challenge; as medical devices become more interconnected, maintenance protocols must include robust digital security measures to protect patient data and prevent unauthorized access to hospital networks. Furthermore, supply chain disruptions can delay the procurement of critical components, leading to extended equipment downtime and affecting clinical operations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Vulnerabilities in Connected Devices | -1.1% | United States & Europe | 2025 - 2034 |
| Supply Chain Volatility for Critical Components | -0.8% | Global | 2025 - 2028 |
| Keeping Pace with Rapid Technological Advancements | -1.0% | Global | 2025 - 2034 |
Medical Equipment Maintenance Market - Updated Report Scope
The scope of this report covers a comprehensive analysis of the global medical equipment maintenance landscape, including detailed evaluations of service types, device categories, and end-user requirements. The analysis integrates historical data with future projections to provide a clear roadmap for stakeholders, emphasizing the transition from traditional service models to digitally-enabled maintenance solutions. The report provides a granular look at regional trends, identifying the specific factors driving or hindering growth in various geographies, and profiles the strategies of the leading companies in the sector.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 54.82 Billion |
| Market Forecast in 2034 | USD 125.42 Billion |
| Growth Rate | 9.6% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Medtronic, FUJIFILM Holdings Corporation, Canon Medical Systems Corporation, Shimadzu Corporation, Hitachi, Ltd., Olympus Corporation, Drägerwerk AG & Co. KGaA, B. Braun Melsungen AG, Stryker, Althea Group, Aramark, Sodexo, Agfa-Gevaert Group, Carestream Health, BCAS Bio-Medical Services Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on the type of medical device, the service provider, the nature of the maintenance service, and the final end-user. Each segment is influenced by different clinical requirements and financial considerations. For instance, the imaging equipment segment requires highly specialized technicians and expensive parts, whereas the electromedical equipment segment involves a higher volume of standardized, routine check-ups. The choice between OEM and ISO service providers often depends on the hospital's budget and the technical complexity of the equipment fleet.
- By Device Type: Imaging Equipment remains the highest revenue contributor due to the critical nature of these machines and their high operational costs. Electromedical equipment and surgical instruments follow, driven by the increasing number of minimally invasive procedures.
- By Service Provider: OEMs still hold the majority share because of their proprietary technology and perceived reliability, but ISOs are growing rapidly as they offer cost-effective, comprehensive packages across multiple brands.
- By Service Type: Preventive maintenance is the fastest-growing sub-segment as it directly contributes to minimizing expensive emergency repairs and extending the usable life of clinical assets.
- By End-User: Hospitals are the primary consumers, although the trend of providing specialized care in outpatient settings is increasing the maintenance demand from diagnostic centers and clinics.
Regional Highlights
- North America: This region is the largest market, characterized by advanced medical facilities, high adoption of robotic surgery, and strict FDA regulations regarding equipment uptime and safety.
- Europe: A mature market with a heavy emphasis on public healthcare systems and standardized maintenance protocols across the EU. Germany, France, and the UK are the primary contributors.
- Asia-Pacific: The fastest-growing region. Rapid urbanization in China and India, coupled with massive government investments in hospital infrastructure, is creating an unprecedented demand for medical equipment and related services.
- Latin America: Showing steady growth, particularly in Brazil and Mexico, as private healthcare sectors expand and modernize their medical device fleets.
- Middle East & Africa: Growth is driven by the modernization of healthcare in Saudi Arabia and the UAE, though overall market penetration is currently lower than other regions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Medical Equipment Maintenance Market.- GE Healthcare
- Siemens Healthineers
- Koninklijke Philips N.V.
- Medtronic
- FUJIFILM Holdings Corporation
- Canon Medical Systems Corporation
- Shimadzu Corporation
- Hitachi, Ltd.
- Olympus Corporation
- Drägerwerk AG & Co. KGaA
- B. Braun Melsungen AG
- Stryker Corporation
- Althea Group
- Aramark
- Sodexo (Healthcare Services)
- Agfa-Gevaert Group
- Carestream Health
- BCAS Bio-Medical Services Ltd.
- Pantak (X-ray) Ltd.
- Crothall Healthcare
Frequently Asked Questions
What is the current global market size of the Medical Equipment Maintenance market?
The market is estimated to be worth approximately USD 54.82 billion in 2025 and is expected to grow steadily at a CAGR of 9.6% through 2034.
Which device segment dominates the maintenance market?
Imaging equipment, including MRI, CT scanners, and X-ray systems, holds the largest market share because of the complexity, high cost, and critical safety requirements associated with these devices.
Why is predictive maintenance becoming popular in healthcare?
Predictive maintenance uses IoT and AI to monitor equipment health in real-time, allowing technicians to fix issues before they cause system failures, thus reducing downtime and improving patient care delivery.
How do Independent Service Organizations (ISOs) compete with OEMs?
ISOs compete by offering multi-vendor service contracts, which are generally more cost-effective and provide a single point of contact for a hospital's entire range of medical equipment, regardless of the brand.
What region is expected to see the fastest growth in the next decade?
The Asia-Pacific region is projected to be the fastest-growing market due to rapid healthcare infrastructure development and increasing investments in medical technology in countries like China and India.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
