Medical Computer Workstation Market
Medical Computer Workstation Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710941 | Published On : September 19, 2026 |
Format : 


 | Author : Erika Grotto
Medical Computer Workstation Market Size
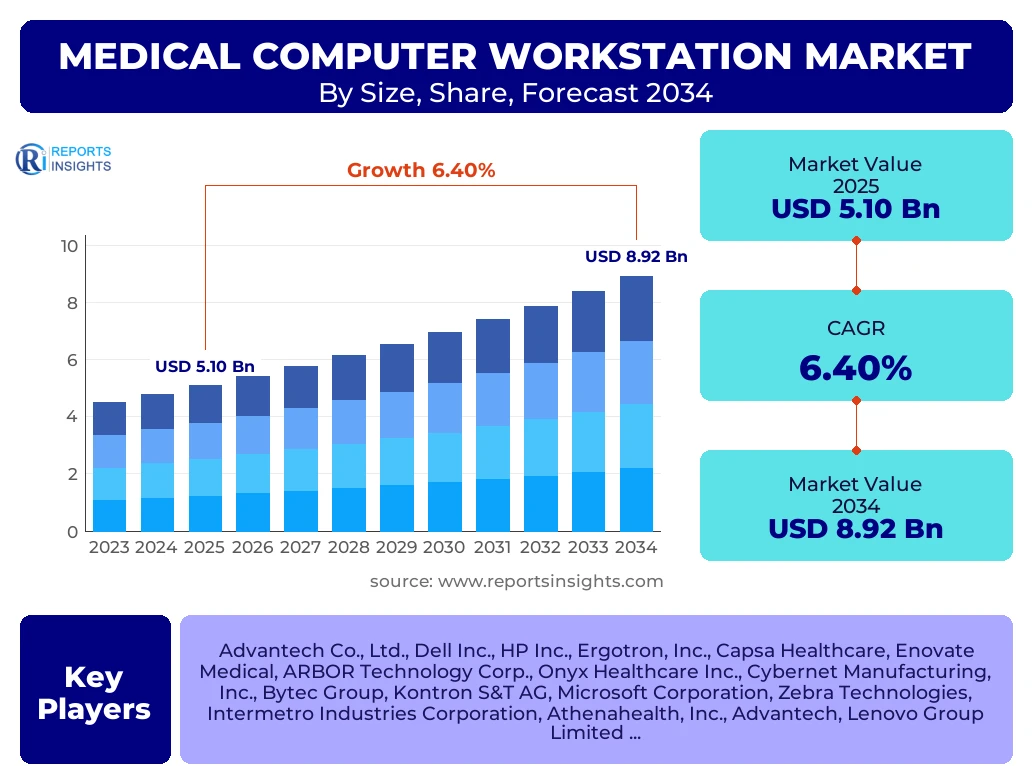
According to Reports Insights Consulting Pvt Ltd, The Medical Computer Workstation Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2026 and 2034. The market is estimated at USD 5.43 Billion in 2026 and is projected to reach USD 8.92 Billion by the end of the forecast period in 2034.
Key Medical Computer Workstation Market Trends & Insights
The global medical computer workstation landscape is undergoing a significant transformation driven by the intersection of high-performance computing and clinical necessity. Modern healthcare environments are increasingly moving toward point-of-care data accessibility, necessitating workstations that offer both mobility and high processing power. Analysts observe a sharp rise in the integration of Artificial Intelligence (AI) and Machine Learning (ML) capabilities directly into workstation hardware to support real-time diagnostic imaging and predictive analytics. This shift is accompanied by a heightened focus on ergonomic design and infection control, leading to the development of workstations with antimicrobial surfaces and fanless cooling systems to prevent the spread of pathogens in sterile environments. Furthermore, the decentralization of healthcare, characterized by the rise of ambulatory surgical centers and home-based clinical monitoring, is creating a demand for more compact, versatile, and energy-efficient computing solutions that can operate seamlessly outside traditional hospital settings.
From a competitive standpoint, benchmarking indicates that market leaders are pivoting toward "Workstation-as-a-Service" models, providing bundled hardware and software maintenance to reduce the capital expenditure burden on healthcare facilities. Regional insights suggest that while North America remains the primary hub for innovation and adoption, the Asia-Pacific region is experiencing the fastest growth due to rapid digital health infrastructure upgrades in China and India. The convergence of 5G technology and medical workstations is also a burgeoning trend, allowing for ultra-low latency in remote surgery and high-resolution teleconsultations, which further solidifies the role of these workstations as the central nervous system of modern clinical operations.
- Largest Region: North America remains the dominant market shareholder, accounting for over 38% of global revenue due to high EMR adoption and advanced healthcare infrastructure.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, fueled by government-led digital health initiatives.
- Largest Segment by Modality: Mobile Medical Workstations (Carts) lead the market as they facilitate bedside clinical documentation and patient engagement.
- Key Technological Trend: Transition to fanless, medical-grade PCs with IP65-rated enclosures for superior hygiene and durability in intensive care units.
- Rising Application: Surgical suites and diagnostic imaging centers are increasingly adopting high-resolution, multi-monitor workstations for precision medicine.
Key Takeaways Medical Computer Workstation Market Size & Forecast
The market trajectory for medical computer workstations reflects a broader institutional commitment to the "Quadruple Aim" of healthcare: improving patient experience, enhancing population health, reducing costs, and improving the work life of healthcare providers. As hospitals transition from legacy systems to integrated digital ecosystems, the workstation serves as the critical interface for Electronic Health Records (EHR) and Picture Archiving and Communication Systems (PACS). The forecast suggests a robust expansion as the replacement cycle for aging hardware coincides with the need for systems capable of handling massive genomic and longitudinal data sets. Investors and stakeholders should note that the market is no longer just about hardware; the value proposition has shifted toward interoperability, cybersecurity resilience, and long-term reliability in 24/7 operational environments.
- Sustained Market Expansion: The steady 6.4% CAGR is underpinned by the mandatory shift toward digitized patient records and the global rise in chronic disease management.
- Infrastructure Modernization: Developing economies are bypassing traditional paper-based systems for fully integrated digital workstations, creating a significant volume of new installations.
- Strategic Procurement: Large hospital chains are moving toward long-term procurement contracts with tier-1 manufacturers to ensure standardized maintenance and cybersecurity protocols.
- Focus on Mobile Health: The mobile workstation segment is expected to outpace fixed installations as nursing workflows prioritize flexibility and mobility.
- Regulatory Compliance: Growing emphasis on IEC 60601-1 certification for medical electrical equipment is a primary barrier to entry for non-specialized IT vendors.
Medical Computer Workstation Market Drivers Analysis
The primary catalysts for the medical computer workstation market include the global mandate for Electronic Health Record (EHR) implementation and the increasing complexity of medical imaging data. As healthcare providers strive for higher efficiency and reduced clinical errors, the demand for high-performance, medical-grade computing power at the point of care has become indispensable. Additionally, the rising elderly population and the subsequent increase in surgical procedures necessitate advanced intraoperative monitoring systems that rely on dedicated workstations.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Widespread EHR and PHR Adoption | +1.8% | Global (Primary: USA, Germany, UK) | 2025 - 2034 |
| Advancements in Medical Imaging (4K/8K Resolution) | +1.5% | Japan, South Korea, USA | 2026 - 2030 |
| Rising Telehealth and Remote Consultation Needs | +1.2% | China, India, Brazil | 2025 - 2028 |
| Shift Toward Point-of-Care Testing (POCT) | +0.9% | Europe, North America | 2025 - 2034 |
Medical Computer Workstation Market Restraints Analysis
Despite the positive growth outlook, the market faces significant headwinds from the high initial capital investment required for medical-grade hardware compared to standard commercial-grade PCs. Furthermore, the rigorous regulatory approval processes and the long lifecycles of medical equipment can slow down the adoption of the latest technological innovations. Cybersecurity concerns regarding the vulnerability of networked workstations to ransomware also act as a deterrent for rapid expansion in certain risk-averse institutions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Medical-Grade Certification | -0.8% | European Union (MDR Compliance) | 2025 - 2034 |
| Budgetary Constraints in Public Healthcare | -0.6% | Latin America, Africa | 2025 - 2030 |
| Cybersecurity Vulnerabilities and Data Privacy Risks | -0.5% | Global | 2026 - 2034 |
Medical Computer Workstation Market Opportunities Analysis
The integration of AI-driven diagnostic tools presents a massive growth frontier, as these tools require specialized GPU-intensive workstations for real-time data processing. Emerging markets in Southeast Asia and the Middle East offer untapped potential as they build "Smart Hospitals" from the ground up. Additionally, the development of eco-friendly and energy-efficient workstations aligns with the growing "Green Healthcare" initiatives globally, providing a competitive edge to sustainable manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI and Machine Learning Integration | +2.1% | USA, China, Israel | 2026 - 2034 |
| Expansion in Ambulatory Surgical Centers (ASCs) | +1.4% | USA, Canada | 2025 - 2034 |
| Development of Smart, IoT-Enabled Workstations | +1.0% | Japan, Germany, Singapore | 2027 - 2034 |
Medical Computer Workstation Market Challenges Impact Analysis
Technical challenges such as interoperability between different workstation brands and existing hospital information systems (HIS) remain a significant hurdle. The global semiconductor supply chain volatility also poses a risk to consistent production schedules and pricing stability. Moreover, training healthcare staff to use increasingly complex multi-functional workstations effectively is a persistent operational challenge for many hospital administrators.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Interoperability with Legacy Systems | -0.7% | Global | 2025 - 2034 |
| Supply Chain Disruptions for Specialized Components | -0.4% | Taiwan, South Korea (Supply side) | 2025 - 2027 |
| Rapid Technological Obsolescence | -0.3% | Global | 2028 - 2034 |
Medical Computer Workstation Market - Updated Report Scope
This report provides a comprehensive analysis of the global medical computer workstation market, covering various modalities, applications, and end-user requirements across six major geographic regions. The scope includes detailed competitive benchmarking, technology roadmaps, and regulatory landscape assessments to provide a 360-degree view of the industry. Special emphasis is placed on the transition from hardware-centric sales to integrated solutions involving software and professional services.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.10 Billion |
| Market Forecast in 2034 | USD 8.92 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Advantech Co., Ltd., Dell Inc., HP Inc., Ergotron, Inc., Capsa Healthcare, Enovate Medical, ARBOR Technology Corp., Onyx Healthcare Inc., Cybernet Manufacturing, Inc., Bytec Group, Kontron S&T AG, Microsoft Corporation, Zebra Technologies, Intermetro Industries Corporation, Athenahealth, Inc., Advantech, Lenovo Group Limited, Panasonic Holdings Corporation, Getac Technology Corp., Teguar Computers. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The medical computer workstation market is segmented based on modality, component, application, and end-user. Modality remains a key differentiator, with mobile workstations gaining traction due to the clinical shift toward bedside patient care. The component segment is increasingly influenced by the software-defined nature of modern medical equipment, where high-end hardware is optimized to run specialized diagnostic and administrative applications. Application-wise, clinical documentation remains the largest sub-segment, though surgical and imaging applications are the highest-value niches due to the precision required in those environments.
- By Modality:
- Mobile Medical Workstations (Carts/WOWs)
- Fixed/Desktop Medical Workstations
- Wall-Mounted Workstations
- All-in-One Medical PCs
- By Component:
- Hardware (Monitors, Keyboards, Internal Components)
- Software (EHR Integration, Diagnostic Tools)
- Services (Consulting, Support, Managed Services)
- By Application:
- Clinical Documentation & Administration
- Medical Imaging and Radiology
- Surgical and Operating Theater Support
- Telehealth and Remote Patient Monitoring
- Pharmacy and Laboratory Information Systems
- By End-User:
- Hospitals (Public and Private)
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers (ASCs)
- Specialized Medical Clinics
- Academic and Research Institutes
Regional Highlights
The regional distribution of the medical computer workstation market is heavily influenced by healthcare spending and the maturity of digital infrastructure. North America is the largest market, characterized by early adoption of EHR and a high density of specialized hospitals. Europe follows closely, with stringent medical device regulations (MDR) driving a market for high-quality, certified workstations. The Asia-Pacific region, however, is the growth engine of the market, where rapid urbanization and healthcare reforms in China and India are creating an immense demand for medical-grade IT infrastructure.
- North America: The United States leads globally due to the presence of major manufacturers and the widespread implementation of the HITECH Act, which incentivized digital health adoption.
- Europe: Germany and the UK are primary hubs, with a strong focus on data privacy (GDPR) and infection control standards, favoring premium, medical-grade hardware.
- Asia-Pacific: Expected to be the fastest-growing region through 2034, driven by the expansion of private hospital networks and government initiatives such as "Digital India" and "Healthy China 2030."
- Latin America: Countries like Brazil and Mexico are witnessing a gradual transition from manual to digital records, presenting long-term growth opportunities for mid-tier workstation providers.
- Middle East & Africa: Significant investment in "Medical Cities" and digital health infrastructure in Saudi Arabia and the UAE is driving the demand for high-end, mobile workstation solutions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Medical Computer Workstation Market.- Advantech Co., Ltd.
- Dell Inc.
- HP Inc.
- Ergotron, Inc.
- Capsa Healthcare
- Enovate Medical
- ARBOR Technology Corp.
- Onyx Healthcare Inc.
- Cybernet Manufacturing, Inc.
- Bytec Group
- Kontron S&T AG
- Microsoft Corporation
- Zebra Technologies
- Intermetro Industries Corporation
- Athenahealth, Inc.
- Lenovo Group Limited
- Panasonic Holdings Corporation
- Getac Technology Corp.
- Teguar Computers
- Tangent Medical
Frequently Asked Questions
Analyzing the most common inquiries regarding the Medical Computer Workstation market provides insights into the primary concerns of hospital IT administrators, procurement officers, and clinicians.
What is the current and projected size of the Medical Computer Workstation Market?
The market is estimated at USD 5.43 Billion in 2026 and is projected to reach USD 8.92 Billion by 2034, growing at a steady CAGR of 6.4%. This growth is driven by the global digitization of healthcare records and the integration of AI in diagnostics.
What are the key differences between a medical-grade workstation and a standard commercial PC?
Medical-grade workstations feature specialized power supplies to prevent electrical leakage (IEC 60601-1 certification), antimicrobial housings for infection control, fanless cooling to prevent pathogen circulation, and high-resolution displays calibrated for diagnostic imaging.
Which modality is leading the market, mobile or fixed workstations?
Mobile medical workstations (carts) currently hold a significant market share and are growing rapidly. They allow clinicians to bring the workstation directly to the patient's bedside, improving data accuracy and patient engagement compared to fixed desk-based systems.
How is AI impacting the development of medical computer workstations?
AI is driving the need for workstations with high-end GPUs and neural processing units. These "AI-ready" workstations enable real-time analysis of medical images and predictive patient monitoring, shifting the workstation from a simple data entry tool to a clinical decision support system.
What are the primary growth barriers in emerging markets?
The primary barriers include the high initial cost of investment, lack of standardized digital infrastructure, and a shortage of trained technical staff to maintain sophisticated workstation networks. However, these are being addressed by government subsidies and simplified managed service models.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted