Lung Cancer Screening Software Market
Lung Cancer Screening Software Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710976 | Published On : September 24, 2026 |
Format : 


 | Author : Erika Grotto
Lung Cancer Screening Software Market Size
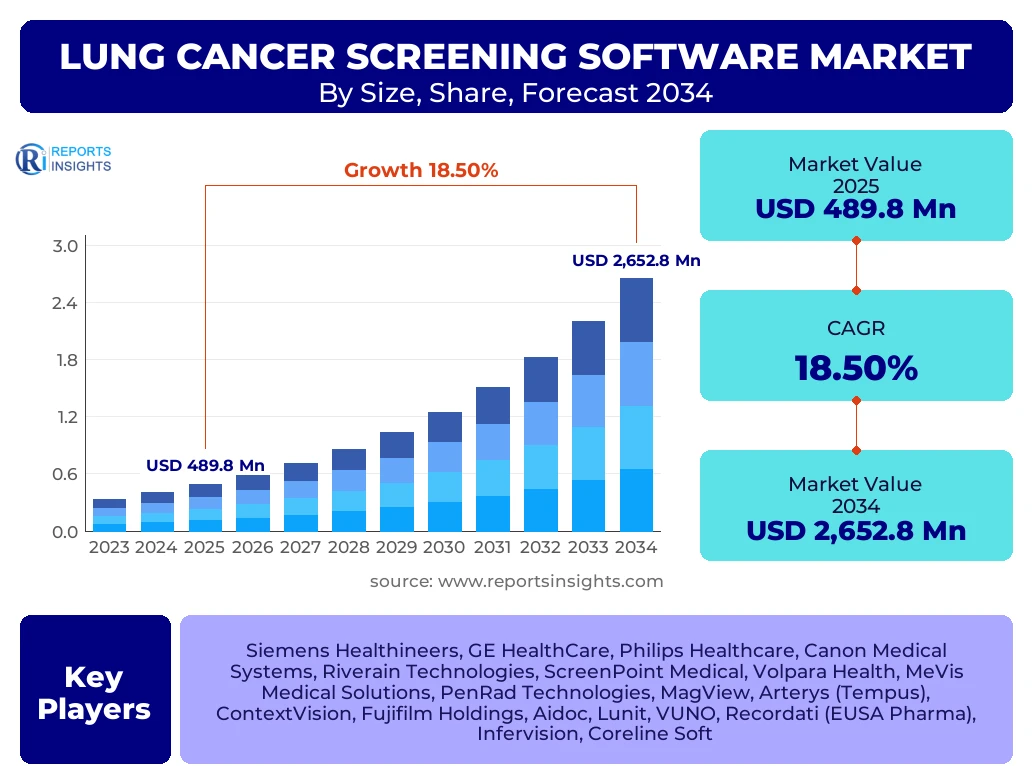
According to Reports Insights Consulting Pvt Ltd, The Lung Cancer Screening Software Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 18.5% between 2026 and 2034. The market is estimated at USD 580.4 Million in 2026 and is projected to reach USD 2,652.8 Million by the end of the forecast period in 2034.
Key Lung Cancer Screening Software Market Trends & Insights
The global Lung Cancer Screening Software market is undergoing a transformative shift driven by the integration of artificial intelligence (AI) and machine learning (ML) algorithms that enhance the precision of Low-Dose Computed Tomography (LDCT) scans. Current market trends indicate a move toward cloud-based, interoperable platforms that allow for seamless data sharing between radiologists, oncologists, and primary care providers. Users and stakeholders are increasingly prioritizing software that offers automated nodule detection, volumetric measurement, and longitudinal tracking to monitor changes over time. Competitive benchmarking reveals that market leaders are focusing on FDA-cleared AI tools that reduce false positives, thereby minimizing unnecessary biopsies and patient anxiety. Furthermore, regional insights suggest that as healthcare infrastructure modernizes in developing economies, the adoption of centralized screening registries is becoming a standard practice to manage high-risk populations effectively.
- North America currently holds the largest market share, driven by favorable reimbursement policies and established screening guidelines from the USPSTF.
- The Asia-Pacific region is the fastest-growing market due to rising smoking rates, increasing air pollution, and rapid healthcare digitization in China and India.
- The AI-integrated software segment represents the largest share in terms of value, as healthcare providers seek to improve diagnostic accuracy and clinical workflow efficiency.
- Predictive analytics for risk stratification is emerging as a critical sub-trend, allowing providers to identify high-risk individuals before symptomatic presentation.
Key Takeaways Lung Cancer Screening Software Market Size & Forecast
The market trajectory for lung cancer screening software is characterized by high-growth potential as global healthcare systems pivot from reactive to preventive care models. Market size and forecast data suggest that the increasing incidence of lung cancer globally, coupled with a growing elderly population, will sustain long-term demand. Stakeholders are focusing on the total cost of ownership and the clinical utility of these software solutions, ensuring they integrate into existing Picture Archiving and Communication Systems (PACS). The forecast period highlights a significant transition toward "Software as a Service" (SaaS) models, which lower the initial capital expenditure for smaller diagnostic centers and rural hospitals.
- The United States is the leading country in the global market, supported by the Lung Cancer Screening Registry and high awareness among the patient population.
- Cloud-based deployment models are expected to outperform on-premise installations due to lower maintenance costs and superior scalability.
- Integration with Electronic Health Records (EHR) is a critical success factor for vendors, as it ensures comprehensive patient management and follow-up tracking.
- Diagnostic accuracy improvements via deep learning are reducing radiologist burnout by automating the preliminary review of thousands of CT slices.
- The 18.5% CAGR reflects a robust adoption curve as national screening programs gain traction in European and Asian markets.
Lung Cancer Screening Software Market Drivers Analysis
The primary catalyst for the Lung Cancer Screening Software market is the global rise in lung cancer incidence, which remains the leading cause of cancer-related mortality worldwide. As health organizations emphasize early detection to improve survival rates, the volume of LDCT scans has increased exponentially, necessitating sophisticated software to manage and interpret data. Furthermore, significant advancements in Computer-Aided Detection (CAD) systems have enabled radiologists to identify pulmonary nodules with unprecedented sensitivity.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI and Deep Learning Algorithms | +4.2% | Global (High in North America & Europe) | 2025 - 2034 |
| Expansion of USPSTF Screening Guidelines | +3.8% | United States | 2025 - 2028 |
| Rise in Public Awareness & Preventive Healthcare | +2.5% | Asia-Pacific (China, Japan) | 2026 - 2034 |
| Increasing Government Funding for Cancer Research | +2.1% | United Kingdom, Germany | 2025 - 2030 |
Lung Cancer Screening Software Market Restraints Analysis
Despite strong growth drivers, the market faces restraints related to the high initial cost of implementing advanced AI-driven screening platforms. For many mid-sized and small healthcare facilities, the capital required for software licenses and hardware upgrades remains a significant barrier. Additionally, the lack of standardized protocols across different software vendors and imaging manufacturers can lead to interoperability challenges, complicating the workflow in multi-vendor environments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Implementation and Maintenance Costs | -1.5% | Latin America, SE Asia | 2025 - 2030 |
| Stringent Regulatory Approval Processes (FDA/CE) | -1.2% | Global | 2025 - 2034 |
| Data Privacy and Security Concerns | -0.8% | Europe (GDPR Compliance) | 2025 - 2034 |
Lung Cancer Screening Software Market Opportunities Analysis
The market is ripe with opportunities, particularly in the development of multi-modal diagnostic tools that combine imaging data with genomic and liquid biopsy results. This holistic approach to screening offers a more comprehensive risk profile for the patient. Additionally, the untapped potential in emerging markets presents a massive growth avenue as governments in these regions begin to implement national lung cancer screening policies to combat the rising burden of respiratory diseases.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Emerging Markets | +3.5% | India, Brazil, Indonesia | 2027 - 2034 |
| Strategic Partnerships with Imaging OEM Vendors | +2.8% | Japan, South Korea | 2025 - 2030 |
| Development of Mobile Screening Solutions | +1.9% | Rural USA, MEA | 2026 - 2034 |
Lung Cancer Screening Software Market Challenges Impact Analysis
Key challenges include the high rate of false positives associated with early-stage screening, which can lead to unnecessary follow-up procedures and increase the overall cost of care. Ensuring radiologist trust in AI-generated findings is another hurdle, as "black-box" algorithms often lack the transparency required for clinical decision-making. Furthermore, the global shortage of trained radiologists to interpret the rising volume of screening data puts pressure on software vendors to provide highly autonomous and reliable solutions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Management of False Positive Rates | -1.1% | Global | 2025 - 2034 |
| Integration with Legacy PACS/RIS Systems | -0.9% | Western Europe, North America | 2025 - 2029 |
Lung Cancer Screening Software Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the Lung Cancer Screening Software market, focusing on technological components, deployment modes, and end-user adoption across six major geographic regions. It provides a comprehensive assessment of the competitive landscape, identifying key players and their strategic initiatives, such as product launches, mergers, and acquisitions. The research utilizes a combination of primary and secondary data to offer precise market valuations and growth projections through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 489.8 Million |
| Market Forecast in 2034 | USD 2,652.8 Million |
| Growth Rate | 18.5% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Siemens Healthineers, GE HealthCare, Philips Healthcare, Canon Medical Systems, Riverain Technologies, ScreenPoint Medical, Volpara Health, MeVis Medical Solutions, PenRad Technologies, MagView, Arterys (Tempus), ContextVision, Fujifilm Holdings, Aidoc, Lunit, VUNO, Recordati (EUSA Pharma), Infervision, Coreline Soft |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Lung Cancer Screening Software market reveals a high demand for integrated software solutions that provide a unified workflow from image acquisition to reporting. The software segment is further divided into standalone and integrated platforms, with the latter gaining dominance due to its ability to streamline radiologist tasks within existing hospital systems. Deployment analysis shows a significant tilt toward cloud-based solutions, which offer superior data accessibility and lower upfront costs. End-user segmentation highlights hospitals as the largest consumers, though diagnostic imaging centers are the fastest-growing segment as screening services move toward decentralized outpatient settings.
- By Component: Software (Standalone and Integrated), and Services (Implementation, Support, and Maintenance).
- By Deployment: Cloud-based (SaaS) and On-premise installations.
- By Application: Automated Nodule Detection, Volumetric Analysis, Reporting & Documentation, and Patient Management.
- By End-user: Large Hospitals, Academic Medical Centers, Diagnostic Imaging Centers, and Private Clinics.
Regional Highlights
- North America: The largest market share holder, characterized by high adoption of AI, favorable Medicare/Medicaid reimbursement for LDCT, and a strong presence of key market players like GE HealthCare and Riverain Technologies.
- Europe: A mature market with significant growth in the UK, Germany, and France, driven by national screening pilots and strict adherence to data protection standards.
- Asia-Pacific: The fastest-growing region, with China and Japan leading the way. High tobacco consumption rates and massive investments in digital health infrastructure are primary growth factors.
- Latin America: Expected to show steady growth as public health initiatives in Brazil and Mexico begin to focus on early cancer detection.
- Middle East & Africa: An emerging market focusing on building cancer care centers and adopting cloud-based diagnostic solutions to overcome geographical barriers in healthcare access.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Lung Cancer Screening Software Market.- Siemens Healthineers
- GE HealthCare
- Philips Healthcare
- Canon Medical Systems
- Riverain Technologies
- ScreenPoint Medical
- Volpara Health
- MeVis Medical Solutions
- PenRad Technologies
- MagView
- Arterys (Tempus)
- ContextVision
- Fujifilm Holdings
- Aidoc
- Lunit
- VUNO
- Infervision
- Coreline Soft
- Aidence
- Thirona
Frequently Asked Questions
Analyze common user questions about the Lung Cancer Screening Software market and generate a concise list of summarized FAQs reflecting key topics and concerns.What is driving the growth of the lung cancer screening software market?
The growth is primarily driven by the rising global incidence of lung cancer, advancements in AI for early detection, and expanded healthcare guidelines that recommend regular screening for high-risk populations.
How does AI improve lung cancer screening software?
AI improves screening by automating the detection of pulmonary nodules, reducing false positives, and providing volumetric data that helps radiologists track nodule growth more accurately over time.
Which deployment model is more popular: cloud-based or on-premise?
Cloud-based models are increasingly popular due to their scalability, lower initial capital expenditure, and ease of integration with remote diagnostic workflows and multi-site healthcare systems.
What are the main challenges in adopting screening software?
Key challenges include high implementation costs, potential interoperability issues with existing hospital IT systems, and the need for clinical validation to ensure high diagnostic accuracy.
Which region is expected to see the highest growth by 2034?
The Asia-Pacific region is expected to experience the highest growth rate due to its large population base, increasing healthcare spending, and rising adoption of digital health technologies in major economies.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted