Loader Market
Loader Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710999 | Published On : September 25, 2026 |
Format : 


 | Author : Jonathan Sikka
Loader Market Size
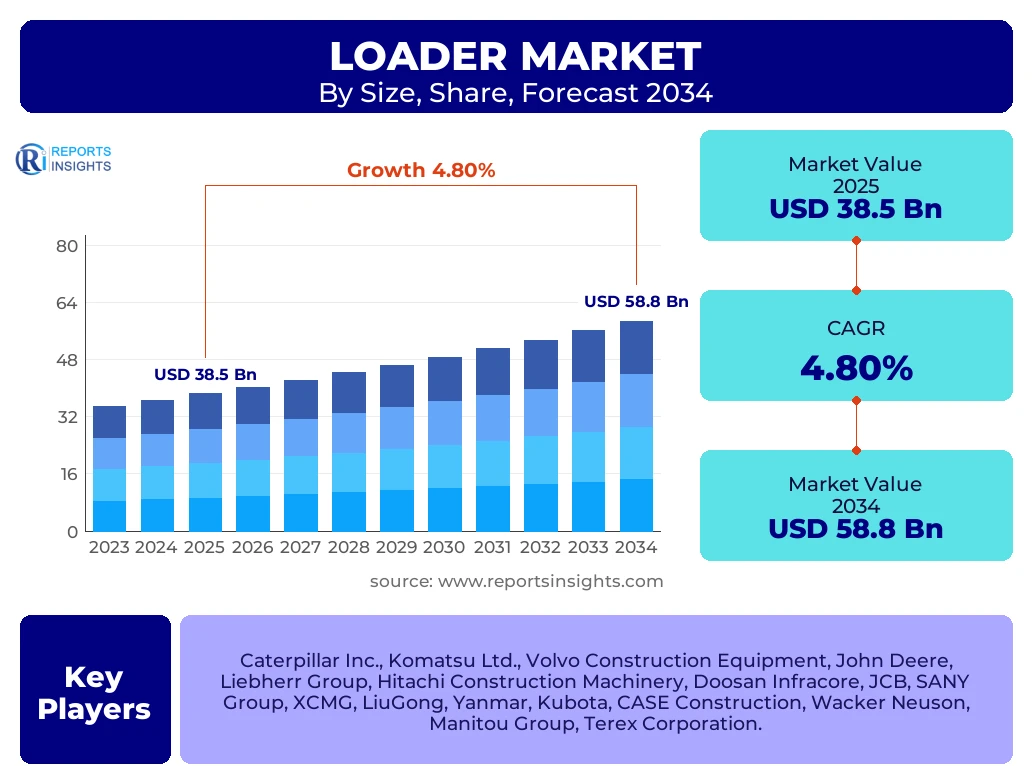
According to Reports Insights Consulting Pvt Ltd, The Loader Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.8% between 2026 and 2034. The market is estimated at USD 40.3 Billion in 2026 and is projected to reach USD 58.8 Billion by the end of the forecast period in 2034.
Key Loader Market Trends & Insights
The global loader market is undergoing a significant transformation driven by the integration of advanced telematics, electrification of powertrains, and the increasing demand for high-efficiency earthmoving equipment in emerging economies. Competitive benchmarking reveals a sharp focus on total cost of ownership (TCO) and fuel efficiency, with major manufacturers shifting toward hybrid and fully electric models to meet stringent Stage V and Tier 4 Final emission standards. Regional insights indicate that the Asia-Pacific region remains the primary engine of growth due to massive infrastructure projects, while North America and Europe are leading the adoption of autonomous and semi-autonomous loading technologies. The market is also seeing a shift toward compact and mini-loaders, which offer greater versatility in urban construction and precision landscaping applications.
- Largest Region: Asia-Pacific, accounting for over 40% of the total market share, driven by rapid urbanization and industrialization in China and India.
- Fastest Growing Region: Southeast Asia and parts of Africa are expected to witness the highest CAGR due to increasing investments in mining and transport infrastructure.
- Largest Segment by Type: Wheel Loaders remain the dominant segment in terms of market value and volume due to their multi-functional utility across diverse industries.
- Largest Segment by Application: Construction and Infrastructure development represent the largest end-user segment, fueled by global government spending on public works.
Key Takeaways Loader Market Size & Forecast
The loader market is characterized by a strong recovery post-pandemic, supported by a resurgence in mining activities and a global push for modernizing aging infrastructure. Key stakeholders are increasingly prioritizing digital twins and IoT-enabled monitoring to reduce downtime and optimize fleet management. The forecast period suggests a move away from traditional diesel-only fleets toward multi-power solutions, including hydrogen and battery-electric systems, particularly for loaders operating in enclosed environments or noise-sensitive urban zones.
- Leading Country: China continues to be the largest manufacturer and consumer of loaders globally, benefiting from a robust domestic supply chain.
- Investment Focus: Significant capital is being directed toward R&D for autonomous navigation and AI-driven load-sensing systems to improve operational safety.
- Market Consolidation: Strategic mergers and acquisitions among Tier 1 and Tier 2 players are expected to streamline production capabilities and expand regional footprints.
- Sustainability Impact: Carbon neutrality goals in the European Union are forcing a rapid transition to zero-emission loaders, creating a niche but high-value market for premium electric models.
Loader Market Drivers Analysis
The primary driver for the loader market is the global surge in infrastructure development, particularly in developing nations where road, rail, and airport projects are expanding at an unprecedented rate. Additionally, the increasing mechanization of the agricultural sector and the modernization of mining operations to improve safety and yield are contributing significantly to the demand for heavy-duty loaders. The push for smart cities is also necessitating the use of compact loaders for intricate urban maintenance tasks.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Infrastructure Investment Initiatives | +1.5% | Global (USA, India, China) | 2025-2034 |
| Transition to Electric and Hybrid Powertrains | +1.2% | Europe and North America | 2026-2030 |
| Technological Integration (IoT & AI) | +0.8% | Japan, Germany, South Korea | 2025-2034 |
| Expansion of Mining and Quarrying Activities | +1.3% | Australia, Brazil, Africa | 2027-2034 |
Loader Market Restraints Analysis
Despite growth, the market faces restraints such as high initial capital expenditure for advanced machinery and the volatility of raw material prices, particularly steel and high-grade plastics. Furthermore, the global shortage of skilled operators for sophisticated loaders equipped with digital controls poses a challenge to immediate market expansion in certain regions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Raw Material Costs | -0.6% | Global | Short-term (2025-2027) |
| Strict Environmental Regulations | -0.4% | EU and North America | Long-term |
Loader Market Opportunities Analysis
The emergence of Autonomous Loaders presents a massive opportunity for reducing labor costs and enhancing safety in hazardous mining environments. Additionally, the aftermarket services sector, including telematics-based predictive maintenance and specialized attachment sales, offers a high-margin revenue stream for manufacturers and dealers alike.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Hydrogen-powered Loaders | +0.9% | Western Europe | 2028-2034 |
| Rental Market Expansion | +1.1% | Middle East and SE Asia | 2025-2034 |
Loader Market Challenges Impact Analysis
Supply chain disruptions for critical semiconductor components continue to affect the production timelines of high-tech loaders. Additionally, the lack of standardized charging infrastructure for electric loaders in remote mining or construction sites remains a significant hurdle for the widespread adoption of zero-emission equipment.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Semiconductor and Chip Shortages | -0.5% | Global Manufacturing Hubs | 2025-2026 |
| Lack of Charging Infrastructure | -0.7% | Developing Economies | 2026-2030 |
Loader Market - Updated Report Scope
This comprehensive report analyzes the global loader market across various dimensions, including machine type, engine capacity, propulsion technology, and end-use industries. It provides granular data on market size, market share, and growth potential for the forecast period of 2026 to 2034, with 2025 serving as the base year for all calculations. The scope encompasses detailed competitive profiling of the top 20 global players and explores the impact of macroeconomic factors such as inflation and regional geopolitical tensions on supply chain dynamics.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 38.5 Billion |
| Market Forecast in 2034 | USD 58.8 Billion |
| Growth Rate | 4.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, John Deere, Liebherr Group, Hitachi Construction Machinery, Doosan Infracore, JCB, SANY Group, XCMG, LiuGong, Yanmar, Kubota, CASE Construction, Wacker Neuson, Manitou Group, Terex Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The loader market is segmented primarily by product type, where Wheel Loaders command the highest share due to their versatility across construction and mining. The propulsion segment is witnessing a significant shift, with electric loaders gaining traction in the "Under 50 HP" category. Application-based segmentation reveals that while construction remains the dominant revenue generator, the industrial and waste management sector is showing rapid growth due to increasing recycling activities and the need for efficient material handling.
- Wheel Loaders: Includes sub-segments of compact, medium, and large wheel loaders tailored for different weight-bearing requirements.
- Skid Steer Loaders: Highly popular in North American residential construction and landscaping due to their maneuverability.
- Backhoe Loaders: Key in emerging markets like India and Brazil for utility and road maintenance projects.
- Track Loaders: Preferred for soft terrain and applications requiring high traction and low ground pressure.
- Electric Propulsion: Fast-growing segment driven by zero-emission mandates and noise reduction requirements in city centers.
Regional Highlights
- Asia-Pacific: The largest and most influential region, with China leading in both production and consumption. India is the fastest-growing market in this region due to the "Gati Shakti" national master plan for infrastructure.
- North America: A mature market focused on replacement cycles and the integration of advanced telematics. The United States is a major hub for Skid Steer and Compact Track loaders.
- Europe: The pioneer in the adoption of electric and hybrid loaders. Germany, France, and the UK are the leading countries, heavily influenced by stringent Euro Stage V emission standards.
- Middle East & Africa: Driven by massive tourism-led infrastructure projects in Saudi Arabia (NEOM) and the UAE, alongside expanding mining operations in sub-Saharan Africa.
- Latin America: Growth is primarily centered in Brazil and Chile, where mining for lithium and copper is driving the demand for large-scale wheel loaders.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Loader Market.- Caterpillar Inc.
- Komatsu Ltd.
- Volvo Construction Equipment (AB Volvo)
- John Deere (Deere & Company)
- Liebherr-International Deutschland GmbH
- Hitachi Construction Machinery Co., Ltd.
- Doosan Infracore (Hyundai Doosan Infracore)
- JCB (J.C. Bamford Excavators Ltd.)
- SANY Group
- XCMG Group (Xuzhou Construction Machinery Group Co., Ltd.)
- Guangxi LiuGong Machinery Co., Ltd.
- Yanmar Holdings Co., Ltd.
- Kubota Corporation
- CASE Construction Equipment (CNH Industrial)
- Wacker Neuson SE
- Manitou Group
- Terex Corporation
- Lonking Holdings Limited
- SDLG (Shandong Lingong Construction Machinery Co., Ltd.)
Frequently Asked Questions
What is the current global market size of the Loader industry?
The Loader Market is estimated to be valued at approximately USD 38.5 Billion in 2025 and is projected to grow to USD 58.8 Billion by 2034.
Which region is expected to dominate the Loader market during the forecast period?
The Asia-Pacific region is expected to dominate the market, holding over 40% of the share, fueled by massive infrastructure and urbanization projects in China and India.
What are the primary factors driving the growth of electric loaders?
The growth of electric loaders is driven by strict government emission regulations, the need for lower noise levels in urban areas, and a reduction in total operating costs over the machine's lifecycle.
Which loader type is most widely used across industries?
Wheel loaders are the most widely used type due to their versatility, high bucket capacity, and suitability for various tasks in construction, mining, and agriculture.
What are the key challenges facing the global loader market?
Key challenges include the high cost of advanced technology integration, potential supply chain disruptions for electronics, and the need for infrastructure development to support electric and hydrogen machines.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted