Lithium Cobalt Oxide Market
Lithium Cobalt Oxide Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710958 | Published On : September 22, 2026 |
Format : 


 | Author : Seema Bhateja
Lithium Cobalt Oxide Market Size
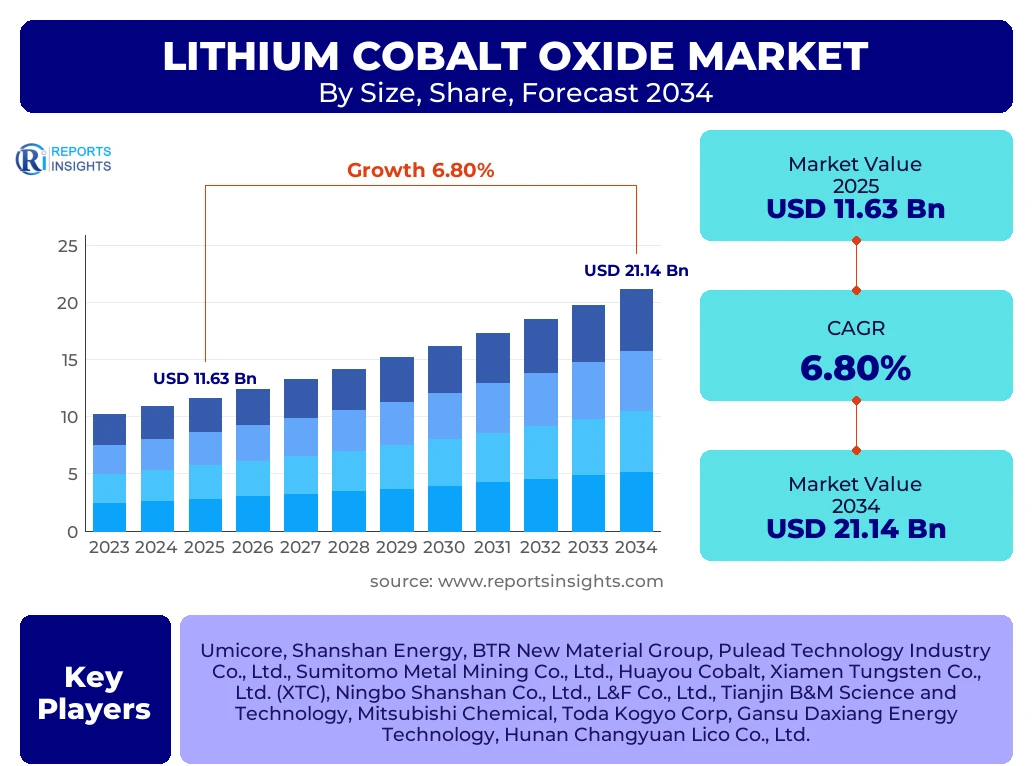
According to Reports Insights Consulting Pvt Ltd, The Lithium Cobalt Oxide Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2026 and 2034. The market is estimated at USD 12.42 Billion in 2026 and is projected to reach USD 21.14 Billion by the end of the forecast period in 2034.
Key Lithium Cobalt Oxide Market Trends & Insights
The global Lithium Cobalt Oxide (LCO) market is undergoing a significant transformation driven by the escalating demand for high-energy-density batteries in the consumer electronics sector. As smartphones, laptops, and wearable devices become increasingly sophisticated, the requirement for cathode materials that offer superior volumetric energy density has intensified. Current market intelligence suggests that the focus is shifting toward high-voltage LCO variants which allow for higher charging cut-off voltages, thereby extending the battery life of portable devices. Additionally, the market is witnessing a rigorous push toward supply chain transparency and ethical sourcing of cobalt, primarily due to global regulatory pressures regarding mining practices in the Democratic Republic of Congo (DRC). Manufacturers are also investing heavily in recycling technologies to mitigate the volatility of raw material prices and to align with global sustainability mandates.
- Largest Region: Asia-Pacific remains the largest regional market, accounting for over 60% of the global share due to the concentration of battery cell manufacturing and consumer electronics assembly in China, South Korea, and Japan.
- Fastest Growing Region: North America is anticipated to be the fastest-growing region during the forecast period, fueled by a resurgence in domestic battery manufacturing and the rapid adoption of high-end portable medical devices.
- Largest Segment by Share: The Mobile Device application segment holds the largest market share, as LCO remains the preferred cathode chemistry for smartphones due to its compact form factor and high energy capacity.
- Emerging Trend: The integration of LCO in solid-state battery research for specialized high-performance applications is emerging as a critical trend for the next decade.
Key Takeaways Lithium Cobalt Oxide Market Size & Forecast
The market trajectory for Lithium Cobalt Oxide is characterized by steady growth within the portable electronics niche, despite the broader battery industry shifting toward Nickel-based chemistries for electric vehicles. Strategic analysis indicates that LCO will maintain its dominance in applications where space is at a premium and energy density is the primary performance metric. The forecast period 2025–2034 will see a stabilization of cobalt prices as recycling infrastructures mature, providing a more predictable cost environment for cathode producers. Furthermore, the convergence of 5G technology and the Internet of Things (IoT) is expected to create a secondary surge in demand for LCO-based batteries in connected devices and high-performance sensors.
- Dominant Country: China is the leading producer and consumer of Lithium Cobalt Oxide, supported by an integrated supply chain ranging from cobalt refining to final battery assembly.
- Growth Driver: The global transition to 5G-enabled smartphones, which require higher battery capacities to support increased power consumption, is a primary driver of LCO market value.
- Strategic Shift: Leading players are pivoting toward high-nickel LCO blends to enhance thermal stability while maintaining high energy density.
- Forecast Stability: The market is expected to exhibit a resilient growth profile with minimal disruption from alternative chemistries in the high-end consumer electronics space through 2034.
Lithium Cobalt Oxide Market Drivers Analysis
The primary growth engine for the Lithium Cobalt Oxide market is the relentless innovation in the consumer electronics industry. As devices become thinner and more powerful, the volumetric energy density offered by LCO remains unmatched by alternative chemistries like LFP or NCM. Furthermore, the expansion of the "Mobile-First" global economy, particularly in emerging markets, ensures a continuous demand for replacement batteries and new device cycles. The specialized requirements of the medical device industry, which demands reliability and high power in small footprints, also serve as a critical micro-driver for high-grade LCO materials.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of 5G Smartphone Penetration | +2.1% | Global / East Asia | 2025 - 2030 |
| Rise in Wearable and IoT Device Demand | +1.4% | North America / Europe | 2026 - 2034 |
| Advancements in High-Voltage LCO Technology | +1.2% | Japan / South Korea | 2025 - 2029 |
Lithium Cobalt Oxide Market Restraints Analysis
The Lithium Cobalt Oxide market faces significant headwinds from the inherent volatility of cobalt prices and the heavy reliance on a localized supply chain centered in the DRC. This cost instability often forces manufacturers to explore cobalt-free or low-cobalt alternatives, particularly in price-sensitive segments. Additionally, environmental and ethical concerns regarding cobalt mining have led to stringent regulatory frameworks and ESG (Environmental, Social, and Governance) requirements that increase operational costs for players throughout the value chain.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High and Volatile Raw Material Costs (Cobalt) | -1.8% | Global | 2025 - 2034 |
| Substitution by NCM and LFP in Power Tools/EVs | -1.5% | Europe / China | 2025 - 2030 |
| Strict ESG Compliance and Mining Regulations | -0.7% | Global / DRC | 2026 - 2034 |
Lithium Cobalt Oxide Market Opportunities Analysis
Significant opportunities lie in the development of closed-loop recycling systems, which can provide a sustainable and cost-effective source of cobalt. As the volume of end-of-life electronics increases, the secondary cobalt market is poised for rapid expansion. Moreover, the growth of the premium drones and aerospace sector, where lightweight batteries with high energy density are mandatory, presents a lucrative niche for high-performance Lithium Cobalt Oxide applications. Strategic partnerships between cathode manufacturers and tech giants to develop proprietary battery chemistries also offer a path for long-term market differentiation.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advanced Battery Recycling Infrastructure | +1.9% | Europe / North America | 2027 - 2034 |
| Demand from High-End Drone and UAV Sectors | +1.1% | Global / USA | 2026 - 2032 |
| Development of All-Solid-State Batteries (ASSB) | +0.8% | Japan / Germany | 2030 - 2034 |
Lithium Cobalt Oxide Market Challenges Impact Analysis
A major challenge for the Lithium Cobalt Oxide market is the technical limitation regarding thermal runaway and safety at extremely high voltages. While increasing the voltage enhances energy density, it also places significant stress on the cathode material, leading to structural degradation and safety risks. Addressing these stability issues through advanced doping and coating techniques requires continuous R&D investment. Furthermore, geopolitical tensions affecting the trade of critical minerals pose a constant threat to the stability of the global LCO supply chain.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cathode Structural Instability at High Voltage | -1.2% | Global | 2025 - 2028 |
| Geopolitical Trade Barriers and Tariffs | -0.9% | USA / China | 2025 - 2034 |
Lithium Cobalt Oxide Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global Lithium Cobalt Oxide market, segmented by product grade, application, and end-user industry. The study evaluates the competitive landscape, provides a deep dive into the supply chain from cobalt extraction to cathode production, and analyzes the impact of technological advancements on market growth. The report covers historical data from 2020 to 2024 and provides comprehensive forecasts from 2026 to 2034, factoring in macroeconomic variables and industry-specific trends.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 11.63 Billion |
| Market Forecast in 2034 | USD 21.14 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Umicore, Shanshan Energy, BTR New Material Group, Pulead Technology Industry Co., Ltd., Sumitomo Metal Mining Co., Ltd., Huayou Cobalt, Xiamen Tungsten Co., Ltd. (XTC), Ningbo Shanshan Co., Ltd., L&F Co., Ltd., Tianjin B&M Science and Technology, Mitsubishi Chemical, Toda Kogyo Corp, Gansu Daxiang Energy Technology, Hunan Changyuan Lico Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Lithium Cobalt Oxide market is categorized primarily by product grade and end-use application. Electronic grade LCO dominates the market as it is specifically synthesized to meet the rigorous performance standards of high-end consumer devices. Industrial grade LCO finds its utility in specialized power systems and older electronics models. On the application side, the smartphone segment remains the cornerstone of demand, while the wearable electronics segment (smartwatches, AR/VR headsets) is identified as the high-growth area due to the miniaturization trend in technology.
- By Product Grade:
- Industrial Grade
- Electronic Grade
- By Application:
- Smartphones
- Laptops and Tablets
- Digital Cameras
- Wearable Electronics (Smartwatches, Fitness Trackers)
- Portable Medical Devices
- High-Performance Drones / UAVs
- Others (MP3 Players, Handheld Consoles)
Regional Highlights
The regional analysis reveals a high concentration of market power in the Asia-Pacific region, which serves as the global hub for battery manufacturing. China, in particular, controls a significant portion of the refining and precursor production. South Korea and Japan are leaders in high-performance cathode technology, hosting some of the world’s most advanced chemical companies. In contrast, North America and Europe are focusing on reducing their reliance on Asian supply chains by investing in domestic cathode production facilities and recycling centers to secure their electronic and defense supply chains.
- Asia-Pacific: Largest market value and share; dominant in manufacturing and raw material processing.
- North America: Fastest growing region due to high adoption of advanced electronics and supportive government policies for domestic battery materials.
- Europe: Focused on circular economy initiatives and strict environmental regulations governing battery chemical production.
- Latin America & MEA: Emerging markets with potential for growth in the consumer electronics retail sector, though manufacturing remains limited.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Lithium Cobalt Oxide Market.- Umicore
- Shanshan Energy
- BTR New Material Group
- Pulead Technology Industry Co., Ltd.
- Sumitomo Metal Mining Co., Ltd.
- Huayou Cobalt
- Xiamen Tungsten Co., Ltd. (XTC)
- Ningbo Shanshan Co., Ltd.
- L&F Co., Ltd.
- Tianjin B&M Science and Technology
- Mitsubishi Chemical
- Toda Kogyo Corp
- Gansu Daxiang Energy Technology
- Hunan Changyuan Lico Co., Ltd.
- Ecopro Co., Ltd.
- Shandong Yiteng New Energy
Frequently Asked Questions
Why is Lithium Cobalt Oxide still preferred for smartphones over cheaper alternatives like LFP?
Lithium Cobalt Oxide (LCO) offers superior volumetric energy density compared to Lithium Iron Phosphate (LFP). In devices where space is extremely limited, such as smartphones, LCO provides more power in a smaller physical footprint, which is critical for maintaining slim designs while ensuring long battery life.
How is the volatility of cobalt prices impacting the LCO market?
Price volatility acts as a restraint, leading to higher manufacturing costs and occasional supply chain disruptions. To mitigate this, companies are investing in high-voltage LCO that uses cobalt more efficiently and expanding battery recycling to recover cobalt from old devices.
What are the environmental concerns associated with the Lithium Cobalt Oxide market?
The primary concerns involve the environmental impact of cobalt mining and the ethical issues surrounding artisanal mining in the DRC. This has led to the implementation of the "Battery Passport" in Europe and other global regulations to ensure responsible sourcing and high recycling rates.
What is High-Voltage Lithium Cobalt Oxide (LCO)?
High-Voltage LCO refers to cathode materials that have been doped or coated to remain stable at charging voltages above 4.45V. This technology allows for increased energy storage capacity within the same battery size, which is the current focus of smartphone battery innovation.
Which region will dominate the Lithium Cobalt Oxide market by 2034?
The Asia-Pacific region is projected to maintain its dominance through 2034, driven by its massive electronics manufacturing infrastructure and established supply chains in China, Japan, and South Korea.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted