Liquid Applied Membrane Market
Liquid Applied Membrane Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711565 | Published On : November 06, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Liquid Applied Membrane Market Size
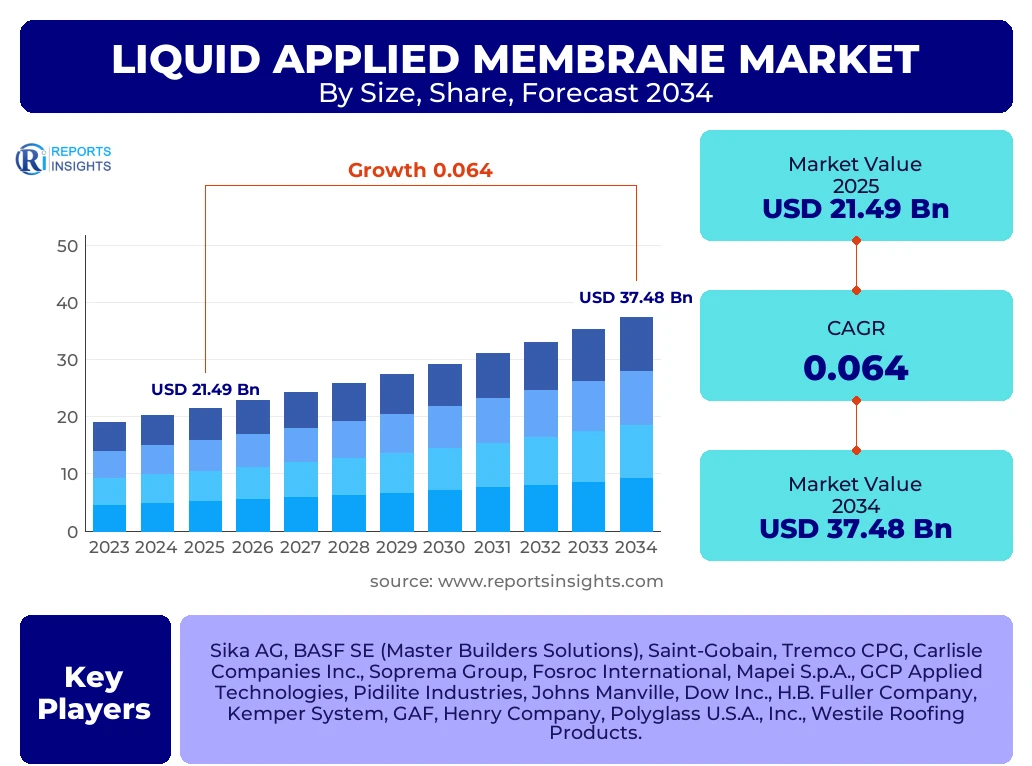
According to Reports Insights Consulting Pvt Ltd, The Liquid Applied Membrane Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 22.87 Billion in 2026 and is projected to reach USD 37.48 Billion by the end of the forecast period in 2034.
The global liquid applied membrane sector is witnessing a transformative era driven by the escalating demand for high-performance waterproofing solutions in both civil engineering and residential construction. Unlike traditional sheet membranes, liquid systems offer a seamless, monolithic barrier that adapts to complex geometries, making them indispensable for modern architectural designs. This growth is further underpinned by the increasing frequency of extreme weather events, which necessitate robust moisture protection for structural longevity and occupant safety.
The valuation reflects a significant shift toward cold-applied technologies that eliminate the fire hazards associated with torch-on systems. As urbanization accelerates across emerging economies and aging infrastructure in developed nations undergoes comprehensive rehabilitation, the adoption of liquid applied membranes is expected to intensify. The convergence of material science innovations, such as rapid-curing polyaspartics and eco-friendly water-based acrylics, provides a strong foundation for the market's robust expansion through 2034.
Key Liquid Applied Membrane Market Trends & Insights
The liquid applied membrane market is characterized by a rapid transition toward sustainable and high-efficiency chemistries. Current market intelligence indicates that users and specifiers are increasingly prioritizing systems that offer not only waterproofing but also secondary benefits such as UV reflectivity (cool roofs) and chemical resistance. In regions like North America and Europe, stringent Volatile Organic Compound (VOC) regulations are pushing manufacturers to phase out solvent-based products in favor of high-solid or water-borne alternatives. Furthermore, the integration of automation in application, such as robotic spray systems for large-scale bridge decks and parking structures, is a burgeoning trend that addresses labor shortages and ensures consistent dry film thickness.
- Asia-Pacific is currently the largest regional market, driven by massive infrastructure projects in China and India.
- The Middle East and Africa represent the fastest-growing region due to major investments in tourism-related construction and smart city initiatives.
- Polyurethane membranes remain the largest segment in terms of market share due to their superior elasticity and durability.
- Sustainable and green roof applications are seeing a surge in demand within metropolitan areas to combat the urban heat island effect.
- The industrial and commercial sectors are adopting PMMA (Polymethyl Methacrylate) membranes for rapid-return-to-service projects, minimizing operational downtime.
Key Takeaways Liquid Applied Membrane Market Size & Forecast
The trajectory of the liquid applied membrane market suggests a consolidated move toward high-value, specialized applications. Analytical insights reveal that the roofing sector remains the primary consumer, but underground waterproofing and wet area protection are gaining substantial ground. Stakeholders are focusing on lifecycle cost analysis rather than initial material costs, recognizing that liquid systems significantly reduce the risk of joint failure, which is the most common cause of leaks in traditional systems. The forecast period will likely see a surge in hybrid systems that combine the strengths of different polymers to provide customized solutions for varying climatic conditions.
- The infrastructure segment is anticipated to witness the highest growth rate during the forecast period.
- China and the United States are the leading countries in terms of absolute market value and technological adoption.
- Bituminous liquid membranes continue to hold significant share in cost-sensitive markets and residential foundation projects.
- The shift from traditional torch-on methods to cold-applied liquid membranes is a primary catalyst for market expansion in developed economies.
- Technological advancements in dual-component spray systems are enhancing application speed and efficiency across large-scale commercial sites.
Liquid Applied Membrane Market Drivers Analysis
The primary drivers of the liquid applied membrane market are rooted in the global push for sustainable infrastructure and the evolution of building codes. Increasing investments in public transport, such as tunnels and bridge decks, require waterproofing solutions that can withstand high hydrostatic pressure and mechanical stress. Additionally, the growing awareness regarding energy-efficient buildings has turned roofing into a functional asset, where liquid membranes provide the necessary base for solar installations and reflective coatings.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Urbanization and Smart City Projects | +1.8% | Global (Strongest in APAC) | 2025 - 2034 |
| Strict Regulations on VOC Emissions | +1.2% | Europe and North America | 2025 - 2030 |
| Demand for Energy-Efficient Cool Roofs | +1.5% | MEA and North America | 2026 - 2034 |
| Shift from Sheet to Liquid for Complex Geometries | +1.1% | Global | 2025 - 2034 |
Liquid Applied Membrane Market Restraints Analysis
Despite the positive outlook, the market faces constraints primarily related to application conditions and material costs. Liquid applied membranes are highly sensitive to weather during the curing phase; high humidity or unexpected rainfall can compromise the bond and integrity of the system. Furthermore, the higher initial cost of premium resins compared to traditional asphalt-based solutions can be a deterrent in price-sensitive developing markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Sensitivity to Ambient Weather Conditions | -0.8% | Global (Tropical Regions) | Ongoing |
| Volatility in Raw Material Prices (Petrochemicals) | -0.6% | Global | 2025 - 2028 |
| High Cost of Specialized Application Equipment | -0.4% | Latin America and Africa | 2025 - 2034 |
Liquid Applied Membrane Market Opportunities Analysis
The market is ripe with opportunities for innovation, particularly in the development of bio-based resins and "smart" membranes capable of self-healing or detecting leaks. The massive backlog of infrastructure maintenance in Western Europe and the United States offers a significant opportunity for liquid applied systems, which are ideal for retrofitting existing structures without the need for extensive demolition.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Infrastructure Rehabilitation and Retrofitting | +2.1% | USA, Germany, Japan | 2026 - 2034 |
| Development of Bio-based Waterproofing Resins | +0.9% | Europe | 2027 - 2034 |
| Growth in the Green Roof (Garden Roof) Sector | +1.4% | Major Metropolitan Cities | 2025 - 2034 |
Liquid Applied Membrane Market Challenges Impact Analysis
Key challenges involve the scarcity of skilled labor proficient in the application of multi-component liquid systems and the lack of standardized global testing protocols for liquid membranes. Improper mixing or application at incorrect thicknesses remains a leading cause of system failure, highlighting the need for rigorous applicator training and certification programs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Certified Professional Applicators | -0.7% | North America and Europe | 2025 - 2030 |
| Lack of Standardized Installation Protocols | -0.5% | Emerging Markets | Ongoing |
| Adhesion Issues on Contaminated Substrates | -0.3% | Global (Renovations) | Ongoing |
Liquid Applied Membrane Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the liquid applied membrane market, covering various chemistries including polyurethane, cementitious, bituminous, acrylic, and polyurea. The scope encompasses detailed forecasting for various end-use sectors such as residential, commercial, industrial, and infrastructure. It offers a granular look at application areas including roofs, walls, underground structures, and tunnels, providing stakeholders with actionable intelligence for strategic planning and investment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 21.49 Billion |
| Market Forecast in 2034 | USD 37.48 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Sika AG, BASF SE (Master Builders Solutions), Saint-Gobain, Tremco CPG, Carlisle Companies Inc., Soprema Group, Fosroc International, Mapei S.p.A., GCP Applied Technologies, Pidilite Industries, Johns Manville, Dow Inc., H.B. Fuller Company, Kemper System, GAF, Henry Company, Polyglass U.S.A., Inc., Westile Roofing Products. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The liquid applied membrane market is segmented primarily by chemistry and application, reflecting the diverse requirements of modern construction. Polyurethane membranes dominate the high-end market due to their excellent crack-bridging properties and elasticity, which are vital in regions prone to thermal expansion. Cementitious membranes, conversely, are the go-to choice for internal wet areas and swimming pools because of their ease of application and compatibility with tile adhesives. The emergence of PMMA has revolutionized the refurbishment market, allowing for roof overlays that cure within an hour, even in sub-zero temperatures.
- By Product Type:
- Polyurethane: Preferred for its superior flexibility and durability in exposed applications.
- Cementitious: Widely used in basements, wet areas, and water tanks.
- Bituminous: A cost-effective solution for foundations and damp-proofing.
- Acrylic: Popular for maintenance and decorative waterproofing in mild climates.
- Polyurea & PMMA: High-performance segments characterized by rapid curing and extreme durability.
- By Application:
- Roofing: The largest segment, including flat roofs, green roofs, and cool roofs.
- Underground Construction: Including foundations and retaining walls requiring hydrostatic resistance.
- Infrastructure: Bridge decks and tunnels where mechanical resistance is paramount.
- Wet Areas: Bathrooms, kitchens, and balconies in residential and commercial buildings.
Regional Highlights
The Asia-Pacific region is the dominant force in the liquid applied membrane market, accounting for a significant portion of global consumption. This dominance is attributed to the aggressive urbanization in China, Southeast Asia, and India, where high-rise developments and transit infrastructure are being constructed at an unprecedented pace. China’s focus on the "Sponge City" concept and India’s Smart Cities Mission are direct catalysts for advanced waterproofing demand.
In Europe, the market is driven by strict sustainability mandates and a high volume of renovation projects. Germany and the UK lead the region in adopting liquid systems for heritage building restoration and green roof installations. North America follows closely, with the US market experiencing a surge in demand for liquid membranes in commercial roofing and parking garage rehabilitation, spurred by federal infrastructure funding. The Middle East is a key growth area, where extreme heat necessitates the use of UV-resistant, solar-reflective liquid membranes to reduce cooling loads in high-profile architectural projects.
- Asia-Pacific: Largest market share, driven by infrastructure and residential booms in China and India.
- North America: Robust demand for high-end polyurethane and PMMA systems in the commercial sector.
- Europe: Leading in green building standards and high-solid, low-VOC membrane adoption.
- Middle East: Fastest growth in "Cool Roof" technologies and large-scale hospitality infrastructure.
- Latin America: Steady growth fueled by industrial expansion in Brazil and Mexico.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Liquid Applied Membrane Market.- Sika AG
- BASF SE (Master Builders Solutions)
- Saint-Gobain
- Tremco CPG (RPM International Inc.)
- Carlisle Companies Inc.
- Soprema Group
- Fosroc International
- Mapei S.p.A.
- GCP Applied Technologies (Saint-Gobain)
- Pidilite Industries Ltd.
- Johns Manville (Berkshire Hathaway)
- Dow Inc.
- H.B. Fuller Company
- Kemper System America, Inc.
- GAF (Standard Industries)
- Henry Company
- Polyglass U.S.A., Inc.
- Westile Roofing Products
- CICO Technologies Ltd.
- Koster American Corporation
Frequently Asked Questions
What are the main advantages of liquid applied membranes over sheet membranes?
Liquid applied membranes provide a seamless, monolithic barrier that eliminates joints, which are the most common failure points in sheet systems. They are particularly effective for complex roof geometries, pipes, and HVAC penetrations, offering superior adhesion and ease of application on various substrates.
Which chemistry is currently dominating the liquid applied membrane market?
Polyurethane (PU) currently dominates the market due to its exceptional elasticity, durability, and crack-bridging capabilities. However, PMMA and Polyurea are gaining share in sectors where rapid curing and extreme mechanical resistance are required.
How does the environment impact the application of liquid membranes?
Environmental factors like humidity, temperature, and dew point are critical. Most liquid membranes require dry substrates and specific temperature ranges to cure properly. Failure to adhere to these conditions can lead to delamination, bubbling, or improper film formation.
What is the impact of VOC regulations on the market?
Strict VOC (Volatile Organic Compound) regulations, especially in Europe and North America, have accelerated the shift from solvent-based to water-based and high-solid content membranes. This transition is driving innovation in eco-friendly chemistries without compromising performance.
What role does the liquid applied membrane play in sustainable construction?
Liquid membranes are central to sustainable construction through "Cool Roof" technology, which reflects sunlight and reduces building energy consumption. They also provide the essential root-resistant barrier needed for intensive and extensive green roof systems, which improve urban air quality and stormwater management.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
