Intravenoimmunoglobulin Ivig Market
Intravenoimmunoglobulin Ivig Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711232 | Published On : October 21, 2026 |
Format : 


 | Author : Erika Grotto
Intravenoimmunoglobulin Ivig Market Size
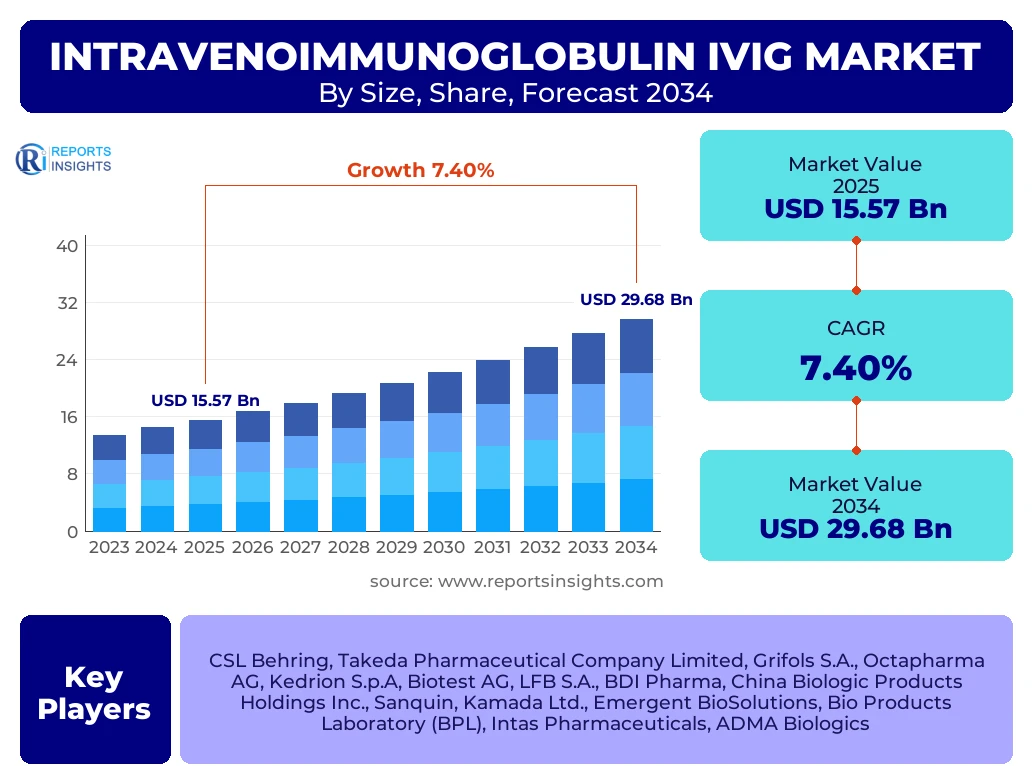
According to Reports Insights Consulting Pvt Ltd, The Intravenoimmunoglobulin Ivig Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2025 and 2034. The market is estimated at USD 16.72 Billion in 2026 and is projected to reach USD 29.68 Billion by the end of the forecast period in 2034.
Key Intravenoimmunoglobulin Ivig Market Trends & Insights
The global market for Intravenous Immunoglobulin is undergoing a transformative phase driven by advancements in plasma fractionation technologies and a shift toward patient-centric administration models. Strategic benchmarking reveals that market leaders are increasingly focusing on the development of highly concentrated formulations and the expansion of subcutaneous administration options to enhance patient compliance. Regional insights suggest that while North America maintains its position as the primary revenue generator due to high diagnosis rates, the Asia-Pacific region is emerging as a high-growth corridor fueled by improving healthcare infrastructure and rising awareness of primary immunodeficiency disorders. Analytical trends indicate that the convergence of automation in plasma collection and data-driven supply chain management is optimizing the production yields of immunoglobulin products.
- North America remains the largest regional market due to established reimbursement frameworks and high prevalence of autoimmune disorders.
- Asia-Pacific is identified as the fastest-growing region, supported by increasing government healthcare spending and improved diagnostic capabilities in China and India.
- The Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) segment holds the largest market share in terms of clinical indication.
- There is a significant trend toward Subcutaneous Immunoglobulin (SCIG) as a preferred alternative to traditional intravenous routes for chronic home-based therapy.
Key Takeaways Intravenoimmunoglobulin Ivig Market Size & Forecast
A comprehensive assessment of market dynamics reveals that the growth trajectory is heavily influenced by the broadening therapeutic applications of immunoglobulin therapy. Market size expansion is closely linked to the rising geriatric population, which is more susceptible to immune-mediated conditions. Stakeholders are prioritizing investments in plasma collection centers to stabilize raw material supply, as the demand for plasma-derived therapies continues to outpace current collection rates. Furthermore, regulatory approvals for new indications are acting as significant catalysts for market volume growth across developed economies. The forecast period highlights a stabilization in pricing strategies as competitive pressures intensify among top-tier global manufacturers.
- The United States is the leading country market, accounting for a substantial portion of the global demand and pricing influence.
- Primary Immunodeficiency (PID) continues to be a primary revenue driver, though neurologic indications are seeing faster volume expansion.
- The Hospital Pharmacy segment remains the leading distribution channel, though Home Care settings are gaining rapid traction.
- Advancements in recombinant immunoglobulin technology represent a significant long-term disruptive potential for the plasma-derived market.
Intravenoimmunoglobulin Ivig Market Drivers Analysis
The acceleration of the global market is fundamentally supported by a combination of demographic shifts and clinical evolution. The increasing frequency of idiopathic and autoimmune conditions globally has necessitated a more robust supply of immunoglobulin. Additionally, the improvement in screening protocols for rare immunological disorders has significantly expanded the patient pool receiving long-term treatment.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Autoimmune Disorders | +2.1% | Global / Highly relevant in Europe and North America | 2025 - 2034 |
| Expanding Off-label Clinical Applications | +1.8% | United States, Germany, Japan | 2026 - 2030 |
| Expansion of Plasma Collection Centers | +1.5% | United States, China, Brazil | 2025 - 2034 |
Intravenoimmunoglobulin Ivig Market Restraints Analysis
Despite robust demand, the market faces structural constraints, primarily related to the high cost of production and the complexity of the biological manufacturing process. The reliance on human plasma as a finite raw material creates supply chain vulnerabilities that can lead to periodic market shortages and price volatility.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Immunoglobulin Therapy | -1.2% | Emerging Markets (India, SE Asia, Africa) | 2025 - 2034 |
| Strict Regulatory Requirements for Plasma Extraction | -0.9% | European Union, China | 2025 - 2030 |
Intravenoimmunoglobulin Ivig Market Opportunities Analysis
The market presents significant white-space opportunities in the development of personalized medicine approaches and the optimization of subcutaneous delivery systems. Emerging economies with expanding middle-class populations represent untapped potential for market penetration as healthcare access improves.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Home-based Subcutaneous Therapy | +2.3% | North America and Western Europe | 2026 - 2034 |
| R&D in Recombinant Immunoglobulin Alternatives | +1.4% | United Kingdom, Switzerland, USA | 2028 - 2034 |
Intravenoimmunoglobulin Ivig Market Challenges Impact Analysis
Manufacturers face persistent challenges regarding the ethical sourcing of plasma and the logistical complexities of cold-chain management for biological products. Furthermore, the emergence of alternative biological therapies for specific autoimmune conditions could challenge the dominance of IVIG in certain therapeutic segments.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply-Demand Imbalance of Plasma | -1.1% | Global | 2025 - 2034 |
| Competition from Targeted Monoclonal Antibodies | -0.7% | United States, EU5 | 2027 - 2034 |
Intravenoimmunoglobulin Ivig Market - Updated Report Scope
This report provides an exhaustive analysis of the global IVIG market, encompassing historical data, current valuation, and future projections. The scope includes a detailed breakdown of indications, administration routes, and end-user segments across major geographic regions. The analysis integrates supply-side dynamics with demand-side trends to offer a 360-degree view of the competitive landscape and regulatory environment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 15.57 Billion |
| Market Forecast in 2034 | USD 29.68 Billion |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | CSL Behring, Takeda Pharmaceutical Company Limited, Grifols S.A., Octapharma AG, Kedrion S.p.A, Biotest AG, LFB S.A., BDI Pharma, China Biologic Products Holdings Inc., Sanquin, Kamada Ltd., Emergent BioSolutions, Bio Products Laboratory (BPL), Intas Pharmaceuticals, ADMA Biologics |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Intravenous Immunoglobulin market is segmented based on product type, clinical indication, route of administration, and end-user profile. The analysis highlights that concentration levels, particularly the 10% concentration segment, dominate the market due to their balance of efficacy and infusion time. Clinical indication segmentation reveals that while oncology-related use is growing, neurological applications remain the most consistent revenue generators. Distribution through hospital pharmacies continues to be the primary channel, although the home care segment is exhibiting the highest growth rate as patients seek more convenient and cost-effective treatment options outside of institutional settings.
- By Type: 5% Concentration, 10% Concentration, 20% Concentration
- By Route of Administration: Intravenous (IVIG), Subcutaneous (SCIG)
- By Indication: Primary Immunodeficiency (PID), Chronic Inflammatory Demyelinating Polyneuropathy (CIDP), Immune Thrombocytopenic Purpura (ITP), Guillain-Barre Syndrome, Kawasaki Disease, Hypogammaglobulinemia, Specific Antibody Deficiency
- By End-User: Hospitals, Specialized Clinics, Home Healthcare Agencies
Regional Highlights
- North America: This region holds the largest market share, driven by a high rate of autoimmune diagnosis, favorable reimbursement policies (Medicare/Medicaid), and the presence of major industry players.
- Asia-Pacific: Identified as the fastest-growing market due to the rapid expansion of healthcare infrastructure in China and India, coupled with increasing awareness of immunodeficiency diseases.
- Europe: Maintains a strong market position with high consumption rates in countries like Germany, France, and the UK, supported by robust public health systems.
- Latin America: Showing steady growth as healthcare accessibility improves and regional plasma fractionation capabilities are expanded.
- Middle East & Africa: A developing market where growth is tied to government-led healthcare initiatives and the rising prevalence of infectious and chronic diseases.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Intravenoimmunoglobulin Ivig Market.- CSL Behring
- Takeda Pharmaceutical Company Limited
- Grifols S.A.
- Octapharma AG
- Kedrion S.p.A
- Biotest AG
- LFB S.A.
- BDI Pharma
- China Biologic Products Holdings Inc.
- Sanquin
- Kamada Ltd.
- Emergent BioSolutions
- Bio Products Laboratory (BPL)
- Intas Pharmaceuticals
- ADMA Biologics
- Nihon Pharmaceutical Co., Ltd.
- GC Pharma
- Hualan Biological Engineering Inc.
- Shanghai RAAS Blood Products Co., Ltd.
- Abeona Therapeutics
Frequently Asked Questions
What is the projected market size of the global Intravenous Immunoglobulin market by 2034?
The market is projected to reach approximately USD 29.68 Billion by 2034, growing at a CAGR of 7.4% from 2026 onwards.
What are the primary drivers for the growth of the IVIG market?
Key drivers include the rising prevalence of autoimmune and primary immunodeficiency disorders, an aging global population, and the expansion of clinical indications for immunoglobulin therapy.
Which region is expected to exhibit the highest growth rate during the forecast period?
The Asia-Pacific region is expected to be the fastest-growing market due to improving diagnostic rates and increasing healthcare investments in major economies like China and India.
How does Subcutaneous Immunoglobulin (SCIG) differ from Intravenous Immunoglobulin (IVIG) in market impact?
SCIG is increasingly favored for chronic treatment as it allows for home-based self-administration, leading to higher patient compliance and reduced healthcare costs compared to hospital-based IVIG infusions.
What are the major challenges facing the IVIG market manufacturers?
The most significant challenges include the scarcity and high cost of human plasma raw material, complex regulatory compliance requirements, and potential competition from newer targeted biological therapies.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
