Industrial Insulation Market
Industrial Insulation Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711220 | Published On : October 19, 2026 |
Format : 


 | Author : Jonathan Sikka
Industrial Insulation Market Size
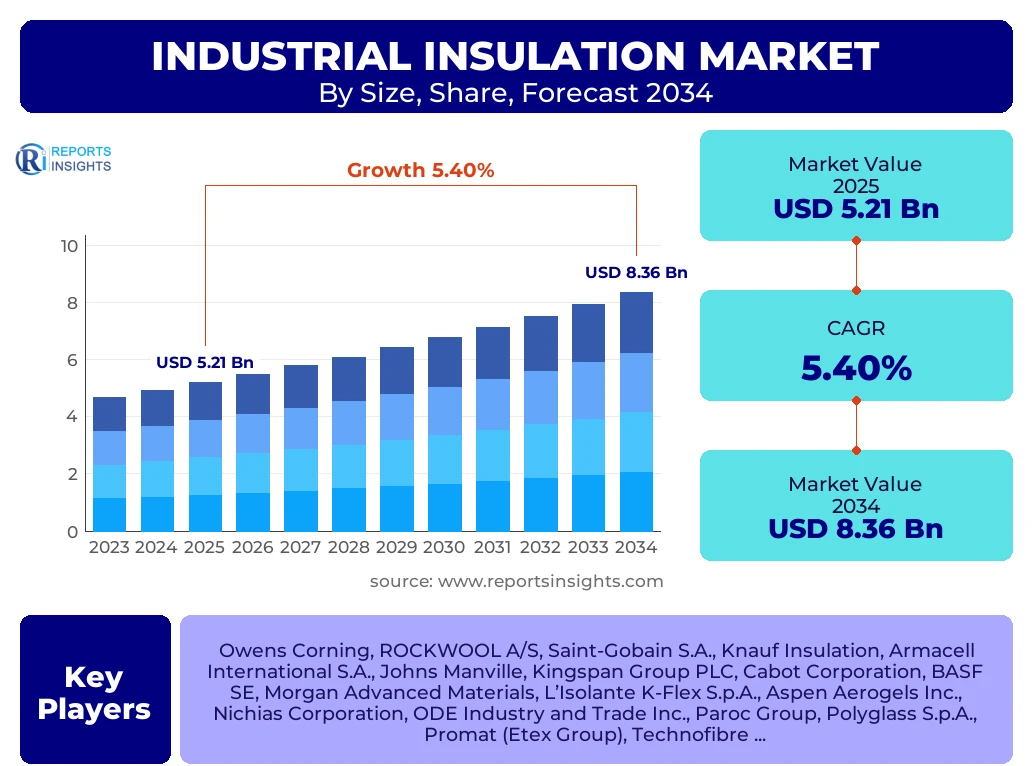
According to Reports Insights Consulting Pvt Ltd, The Industrial Insulation Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 5.48 Billion in 2026 and is projected to reach USD 8.36 Billion by the end of the forecast period in 2034.
Key Industrial Insulation Market Trends & Insights
The global industrial insulation market is undergoing a significant transformation driven by the dual imperatives of energy efficiency and carbon footprint reduction. Stakeholders are increasingly focusing on high-performance materials that offer superior thermal resistance while meeting stringent fire safety regulations. Recent analysis indicates that the integration of digital twins and IoT-based monitoring systems into insulation management is becoming a prevalent trend, allowing industrial operators to detect heat leaks and moisture ingress in real-time. This shift toward "smart insulation" is particularly evident in the chemical and power generation sectors, where operational uptime and energy conservation are critical to maintaining competitive margins.
- Largest Region: North America remains the largest region by market share, driven by a mature industrial base and strict environmental regulations.
- Fastest Growing Region: Asia-Pacific is the fastest-growing region, fueled by rapid industrialization in China, India, and Southeast Asia.
- Leading Material Segment: Mineral Wool continues to hold the largest share due to its excellent fire-resistant properties and cost-effectiveness.
- Dominant End-Use Industry: The Power Generation sector leads the market share, necessitated by the high-temperature requirements of thermal and nuclear plants.
Key Takeaways Industrial Insulation Market Size & Forecast
The forecast period from 2025 to 2034 suggests a steady upward trajectory for the industrial insulation sector, underpinned by the retrofitting of aging infrastructure in developed economies and new capacity additions in emerging markets. Investors and market participants are increasingly prioritizing sustainable materials, such as bio-based and recycled insulation products, to align with global ESG (Environmental, Social, and Governance) targets. The market is also witnessing a surge in demand for cryogenic insulation, particularly within the expanding Liquefied Natural Gas (LNG) supply chain, which requires specialized materials to maintain ultra-low temperatures during transport and storage.
- China is the leading country in terms of production capacity and domestic consumption growth in the APAC region.
- Sustainability is the primary driver for product innovation, with manufacturers shifting away from traditional synthetic foams toward recyclable mineral fibers.
- Pipe Insulation remains the largest product segment, accounting for over 45% of the total market volume.
- The Middle East is emerging as a critical hub for high-temperature insulation due to its heavy concentration of oil refineries and petrochemical complexes.
Industrial Insulation Market Drivers Analysis
The primary catalyst for the industrial insulation market is the global push for enhanced energy efficiency across heavy industries. As energy prices fluctuate and carbon taxes become more prevalent, industries such as oil and gas, cement, and steel are investing heavily in advanced insulation solutions to minimize heat loss and reduce operational expenditures. Furthermore, the expansion of the global LNG infrastructure, necessitated by the transition toward cleaner fossil fuels, is creating a robust demand for specialized cryogenic insulation materials.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Energy Efficiency Regulations | +1.8% | European Union & North America | 2025–2034 |
| Expansion of LNG Terminals | +1.5% | USA, Qatar, Australia | 2026–2032 |
| Rapid Industrialization in APAC | +1.2% | China & India | 2025–2030 |
Industrial Insulation Market Restraints Analysis
Market growth faces significant headwinds from the volatility of raw material prices, particularly for petrochemical-based insulation products like plastic foams. Additionally, the high initial capital investment required for high-performance insulation systems, such as aerogels or vacuum panels, often deters small to medium-sized enterprises (SMEs) from adopting advanced solutions. The lack of a skilled workforce capable of installing complex insulation systems in hazardous industrial environments also remains a persistent barrier to widespread market penetration.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Raw Material Costs | -0.9% | Global | 2025–2034 |
| High Installation Costs | -0.7% | Developing Economies | 2025–2028 |
Industrial Insulation Market Opportunities Analysis
The transition toward a circular economy presents substantial opportunities for manufacturers to develop fully recyclable insulation materials. There is also a burgeoning niche in the "Health and Safety" segment, where non-carcinogenic and low-VOC (Volatile Organic Compound) insulation products are gaining traction. Furthermore, the refurbishment of aging industrial plants in Eastern Europe and parts of North America offers a massive market for retrofitting services, where advanced insulation can significantly extend the lifespan and efficiency of legacy equipment.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Green Building & Sustainable Materials | +1.4% | Germany, Scandinavia, USA | 2026–2034 |
| Retrofitting Aging Infrastructure | +1.1% | USA, Russia, UK | 2025–2034 |
Industrial Insulation Market Challenges Impact Analysis
The industry must navigate the challenge of Corrosion Under Insulation (CUI), which remains a multi-billion dollar problem for the oil, gas, and chemical sectors. Developing insulation materials that can effectively repel moisture while allowing for visual inspection of the underlying substrate is a technical hurdle that requires significant R&D investment. Additionally, geopolitical tensions and trade barriers affecting the supply of specialty chemicals and minerals used in insulation production could lead to regional supply-demand imbalances.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Corrosion Under Insulation (CUI) Management | -0.6% | Coastal Industrial Zones | 2025–2034 |
| Disruptions in Global Supply Chains | -0.4% | Global Market | 2025–2027 |
Industrial Insulation Market - Updated Report Scope
This report provides a comprehensive examination of the global industrial insulation landscape, covering historical data from 2020 and providing detailed forecasts through 2034. It encompasses a deep dive into material types, product formats, and diverse end-use applications across six major geographical regions. The scope includes an analysis of competitive dynamics, technological innovations, and the regulatory frameworks that govern thermal and acoustic insulation standards in heavy industry.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.21 Billion |
| Market Forecast in 2034 | USD 8.36 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Owens Corning, ROCKWOOL A/S, Saint-Gobain S.A., Knauf Insulation, Armacell International S.A., Johns Manville, Kingspan Group PLC, Cabot Corporation, BASF SE, Morgan Advanced Materials, L’Isolante K-Flex S.p.A., Aspen Aerogels Inc., Nichias Corporation, ODE Industry and Trade Inc., Paroc Group, Polyglass S.p.A., Promat (Etex Group), Technofibre, Unifrax, and KCC Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The industrial insulation market is segmented based on material, product type, and end-use industry to provide a granular view of growth drivers. Mineral wool continues to lead the material segment due to its versatility and high melting point, making it indispensable for high-temperature applications. Pipe insulation represents the largest product category, as extensive piping networks in refineries and power plants require constant thermal regulation to prevent energy loss and ensure worker safety. In terms of end-use, the Power Generation sector remains the primary consumer, though the Chemical and Petrochemical sectors are catching up due to increased investments in processing facilities across the Middle East and Asia.
- By Material Type:
- Mineral Wool (Glass Wool and Stone/Rock Wool)
- Calcium Silicate
- Plastic Foam (Expanded Polystyrene, Extruded Polystyrene, Polyurethane/Polyisocyanurate)
- Elastomeric Foam
- Others (Aerogels, Perlite, and Cellular Glass)
- By Product Type:
- Pipe Insulation
- Board Insulation
- Blanket Insulation
- Others (Custom shapes and sprays)
- By End-Use Industry:
- Power Generation (Thermal, Nuclear, Solar Thermal)
- Oil & Gas (Upstream, Midstream, Downstream)
- Chemical & Petrochemical
- Food & Beverage Processing
- Cement and Metal Processing
- Others
Regional Highlights
- North America: The largest market share holder, dominated by the United States. Growth is driven by the resurgence of the domestic manufacturing sector and stringent EPA regulations regarding energy conservation.
- Asia-Pacific: The fastest-growing region with a CAGR exceeding 6.5%. Rapid urbanization and the establishment of massive industrial zones in China, India, and Vietnam are the primary catalysts.
- Europe: A highly mature market with a focus on advanced materials. The "European Green Deal" is pushing industries to adopt high-efficiency insulation to reach net-zero targets.
- Middle East & Africa: Significant growth in the oil and gas sector, particularly for high-temperature insulation in oil refineries and desalination plants.
- Latin America: Emerging opportunities in the mining and food processing industries, particularly in Brazil and Chile.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Industrial Insulation Market.- Owens Corning
- ROCKWOOL A/S
- Saint-Gobain S.A.
- Knauf Insulation
- Armacell International S.A.
- Johns Manville (Berkshire Hathaway)
- Kingspan Group PLC
- Cabot Corporation
- BASF SE
- Morgan Advanced Materials
- L’Isolante K-Flex S.p.A.
- Aspen Aerogels Inc.
- Nichias Corporation
- ODE Industry and Trade Inc.
- Paroc Group
- Polyglass S.p.A.
- Promat (Etex Group)
- Unifrax (Alkegen)
- KCC Corporation
- Huntsman Corporation
Frequently Asked Questions
What is the current size of the global Industrial Insulation Market?
The global Industrial Insulation Market is estimated to be valued at approximately USD 5.21 Billion in 2025 and is projected to reach USD 8.36 Billion by 2034, growing at a CAGR of 5.4%.
Which material type is most preferred in industrial insulation?
Mineral wool (including rock wool and glass wool) is the most preferred material due to its excellent thermal resistance, fire safety ratings, and cost-effectiveness across high-temperature industrial applications.
What are the key drivers for the Industrial Insulation Market?
The key drivers include stringent government regulations regarding energy efficiency, the global expansion of the LNG and petrochemical industries, and the need to reduce operational costs through improved thermal management.
Which region is expected to show the fastest growth?
The Asia-Pacific region is expected to show the fastest growth rate during the forecast period, driven by massive infrastructure projects and rapid industrialization in emerging economies like India and China.
How does Corrosion Under Insulation (CUI) affect the market?
CUI is a major challenge that leads to equipment failure and safety risks. This has prompted the market to innovate with moisture-resistant materials and smart monitoring sensors to detect and mitigate corrosion early.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
