Industrial Institutional Cleaning Chemicals Market
Industrial Institutional Cleaning Chemicals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711516 | Published On : November 04, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Industrial Institutional Cleaning Chemicals Market Size
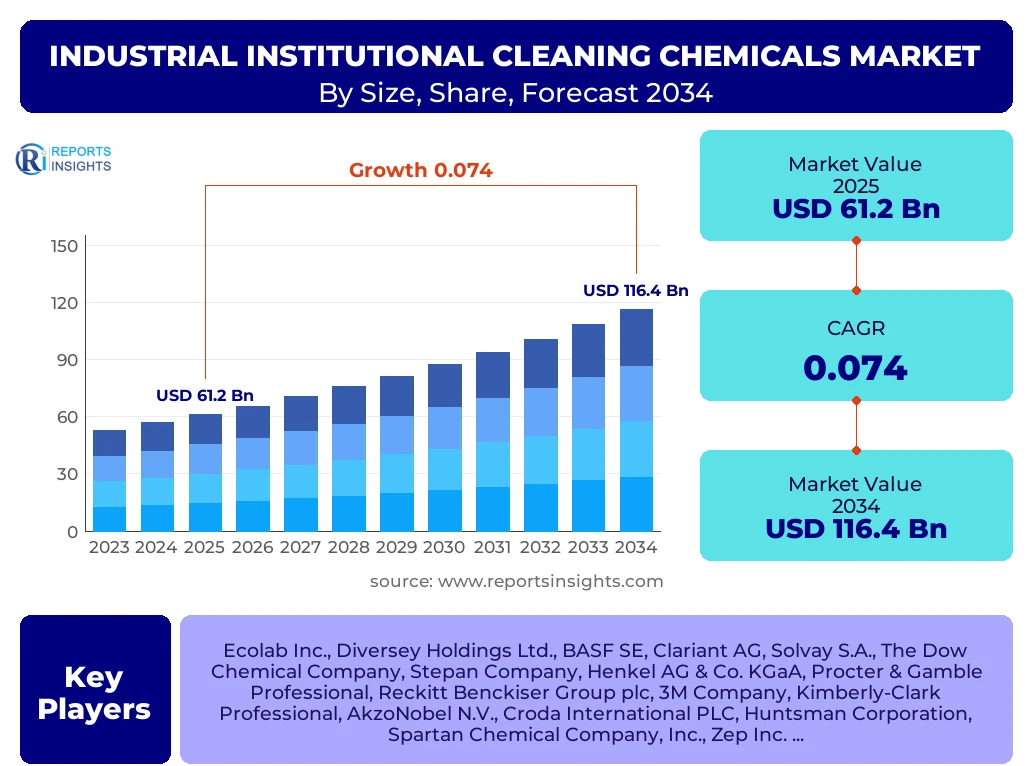
According to Reports Insights Consulting Pvt Ltd, The Industrial Institutional Cleaning Chemicals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2025 and 2034. The market is estimated at USD 65.7 Billion in 2026 and is projected to reach USD 116.4 Billion by the end of the forecast period in 2034.
Key Industrial Institutional Cleaning Chemicals Market Trends & Insights
The industrial and institutional (I&I) cleaning chemicals sector is undergoing a profound transformation driven by a convergence of heightened hygiene standards, regulatory pressures for sustainable formulations, and technological integration. Modern cleaning protocols have shifted from basic aesthetics to rigorous microbial control, particularly in healthcare and food processing environments. Market participants are increasingly focusing on specialized chemical delivery systems that minimize waste and maximize efficacy. Regional analysis indicates that while North America remains a powerhouse due to mature regulatory frameworks, the Asia-Pacific region is experiencing a surge in demand fueled by rapid urbanization and the expansion of the hospitality sector. Competitive benchmarking reveals a strategic pivot toward bio-based surfactants and concentrated formulations that reduce logistics costs and carbon footprints.
- Largest Region: North America remains the dominant market shareholder, accounting for over 32% of global revenue, driven by stringent healthcare and food safety standards.
- Fastest Growing Region: Asia-Pacific is anticipated to register the highest CAGR of approximately 8.9% through 2034, supported by the burgeoning industrial sector in India, China, and Southeast Asia.
- Largest Segment by Share: The General Purpose Cleaners segment currently leads the market in terms of volume and value, utilized extensively across commercial offices and educational institutions.
- High-Growth Segment: Disinfectants and Sanitizers are witnessing the fastest growth rate post-pandemic, as public spaces maintain elevated hygiene protocols.
- Dominant Application: The Commercial segment, encompassing hotels, restaurants, and retail spaces, constitutes the largest end-use application for I&I chemicals.
Key Takeaways Industrial Institutional Cleaning Chemicals Market Size & Forecast
The global outlook for the I&I cleaning chemicals market remains robust, with a clear trajectory toward specialized applications and sustainable chemistry. Forecast models suggest that the market will benefit from the continuous expansion of the global healthcare infrastructure and a renewed focus on employee wellness in corporate environments. Stakeholders are prioritizing product transparency and ingredient safety to comply with evolving environmental regulations such as REACH and the EPA Safer Choice program. The integration of IoT-enabled chemical dispensers is another significant development, allowing facility managers to monitor consumption patterns and optimize inventory management, thereby reducing operational overheads and enhancing the efficacy of cleaning programs across large-scale institutions.
- Leading Country: The United States continues to lead global demand due to its massive healthcare infrastructure and strict OSHA and FDA compliance requirements.
- Sustainability Pivot: Over 60% of new product launches in the I&I space now feature eco-labels or bio-degradable certifications, indicating a permanent shift in market preference.
- Healthcare Expansion: The medical and healthcare sector is the primary driver for high-efficacy disinfectants, with an expected 8.2% CAGR within this specific application sub-segment.
- Value-Chain Optimization: Manufacturers are increasingly adopting direct-to-consumer digital platforms to bypass traditional distribution hurdles and improve profit margins.
- Strategic Consolidation: Large players are acquiring regional niche manufacturers to expand their geographic reach and gain access to proprietary green cleaning technologies.
Industrial Institutional Cleaning Chemicals Market Drivers Analysis
The primary catalyst for the industrial and institutional cleaning chemicals market is the escalation of global health and safety standards. Government mandates across the globe, particularly in the wake of public health crises, have institutionalized rigorous cleaning and disinfection cycles in high-traffic areas such as airports, schools, and shopping malls. This regulatory environment necessitates high-performance chemical solutions that can guarantee pathogen elimination while remaining safe for frequent human exposure.
Furthermore, the explosive growth of the global food processing industry serves as a major market driver. Food safety regulations demand specialized cleaning agents that are effective against foodborne pathogens like Salmonella and Listeria but do not leave toxic residues. As international trade in processed foods increases, the adoption of standardized, high-grade cleaning chemicals becomes mandatory for exporters, thereby expanding the market footprint of global chemical suppliers into emerging economies.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Healthcare Hygiene Regulations | +2.1% | Global (Strongest in North America & Europe) | Short to Long Term |
| Expansion of Food Processing Industry | +1.8% | Asia-Pacific and Latin America | Medium Term |
| Rise in Medical Tourism and Hospital Expansion | +1.5% | India, Thailand, and Middle East | Medium to Long Term |
Industrial Institutional Cleaning Chemicals Market Restraints Analysis
Volatile raw material pricing represents a significant hurdle for manufacturers in the I&I cleaning chemicals sector. Many active ingredients, such as surfactants and solvents, are derived from petrochemicals, making their production costs susceptible to fluctuations in global oil and gas prices. These pricing pressures are often difficult to pass on to institutional clients who operate under long-term, fixed-price contracts, leading to margin compression for chemical producers.
In addition to economic factors, stringent environmental regulations regarding Volatile Organic Compounds (VOCs) and phosphorus content act as a restraint. Transitioning away from established, effective, but environmentally harmful ingredients requires substantial investment in research and development. Smaller manufacturers often struggle to meet these new standards, leading to market exits or forced consolidation, which can temporarily disrupt the local supply chain and limit product variety for certain niche applications.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Fluctuations | -1.2% | Global | Ongoing |
| Stringent Environmental Compliance (VOCs) | -0.9% | European Union and California (USA) | Short to Medium Term |
Industrial Institutional Cleaning Chemicals Market Opportunities Analysis
The shift toward "Green Chemistry" presents the single largest opportunity in the market. As corporate social responsibility (CSR) becomes a core component of institutional procurement policies, there is a massive untapped demand for cleaners that use plant-derived surfactants, bio-enzymes, and non-toxic solvents. Companies that can provide high-performance sustainable alternatives at a price point comparable to traditional chemicals will capture significant market share in the coming decade.
Technological integration through smart dispensing systems and the Internet of Things (IoT) also offers a lucrative avenue for growth. These systems allow for precise dilution of concentrated chemicals, preventing over-use and reducing environmental impact while providing valuable data to facility managers. By pivoting from a product-only model to a service-oriented model that includes equipment monitoring and automated reordering, manufacturers can foster deeper customer loyalty and generate recurring revenue streams.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based Surfactants | +2.4% | North America and Europe | Medium to Long Term |
| IoT-Enabled Smart Dispensing Systems | +1.7% | Global (Urban Centers) | Short to Medium Term |
| Rapid Urbanization and Hospitality Growth | +1.3% | Southeast Asia and Africa | Long Term |
Industrial Institutional Cleaning Chemicals Market Challenges Impact Analysis
Counterfeit and sub-standard products in emerging markets pose a significant challenge to the reputation and revenue of established global brands. In regions with loose regulatory enforcement, local unorganized players often produce low-cost, ineffective, or even hazardous cleaning agents that mimic the branding of market leaders. This not only erodes market share but also potentially compromises public safety, requiring global companies to invest heavily in brand protection and legal enforcement.
Furthermore, the challenge of product differentiation in a highly commoditized market remains prevalent. Many institutional buyers prioritize cost over specialized features, leading to aggressive price wars. Manufacturers must find innovative ways to demonstrate the "Total Cost of Clean"—showing how more expensive, concentrated, or efficient chemicals can actually reduce overall facility maintenance costs through reduced labor and water consumption—rather than just competing on the initial price per gallon.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Market Fragmentation and Price Wars | -1.1% | Global | Ongoing |
| Counterfeit Products in Emerging Markets | -0.7% | Asia-Pacific and parts of Africa | Medium Term |
Industrial Institutional Cleaning Chemicals Market - Updated Report Scope
This report provides a granular analysis of the global Industrial and Institutional (I&I) cleaning chemicals landscape, covering technological advancements, regulatory shifts, and economic indicators. It encompasses a comprehensive assessment of the value chain, from raw material procurement to end-user applications, ensuring stakeholders have the necessary data to navigate the complexities of this highly competitive market. The scope includes deep-dives into various product categories and their specific roles in different industrial verticals.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 61.2 Billion |
| Market Forecast in 2034 | USD 116.4 Billion |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Ecolab Inc., Diversey Holdings Ltd., BASF SE, Clariant AG, Solvay S.A., The Dow Chemical Company, Stepan Company, Henkel AG & Co. KGaA, Procter & Gamble Professional, Reckitt Benckiser Group plc, 3M Company, Kimberly-Clark Professional, AkzoNobel N.V., Croda International PLC, Huntsman Corporation, Spartan Chemical Company, Inc., Zep Inc., Pilot Chemical Corp., Evonik Industries AG, Church & Dwight Co., Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the I&I cleaning chemicals market reveals a sophisticated ecosystem designed to meet the unique demands of various high-traffic and high-cleanliness environments. The Product Type segmentation highlights the dominance of general-purpose cleaners, yet shows an aggressive growth path for specialized sanitizers that meet EPA or equivalent medical-grade standards. The Raw Material segment is witnessing a significant shift as traditional surfactants are being replaced by bio-based alternatives that offer similar efficacy with lower aquatic toxicity. From an Application perspective, the healthcare and food processing sectors are the most demanding, requiring validated efficacy against specific pathogens, whereas the commercial sector prioritizes cost-efficiency and user experience (fragrance and ease of use).
- By Product Type:
- General Purpose Cleaners (Multi-surface, Glass, Bathroom)
- Disinfectants and Sanitizers (Chlorine-based, Quats, Hydrogen Peroxide, Alcohol-based)
- Laundry Care (Detergents, Softeners, Bleaches)
- Warewashing (Dishwashing Detergents, Rinse Aids)
- Floor Care (Waxes, Strippers, Polishes)
- Specialty Cleaners (Degreasers, Descalers, Metal Cleaners)
- By Raw Material:
- Surfactants (Anionic, Non-ionic, Cationic, Amphoteric)
- Solvents (Alcohols, Ethers, Bio-solvents)
- Enzymes (Proteases, Amylases, Lipases)
- Chelating Agents and Builders
- By Application:
- Commercial (Hospitality, Restaurants, Retail, Offices)
- Institutional (Hospitals, Nursing Homes, Schools, Universities, Public Facilities)
- Industrial (Food and Beverage Processing, Pharmaceutical Manufacturing, General Manufacturing)
Regional Highlights
- North America: The largest market by value, characterized by advanced adoption of green cleaning standards and high concentration of major market players like Ecolab and 3M. The US healthcare sector is a primary driver for disinfectant innovation.
- Europe: The leader in regulatory-driven innovation. EU REACH and ECOLABEL standards have forced manufacturers to pivot rapidly toward sustainable chemistries, making Europe the global hub for bio-based surfactant research.
- Asia-Pacific: The fastest-growing region. Rapid industrialization in China and India, along with a booming tourism sector in Southeast Asia, is creating massive demand for institutional hygiene products. Rising middle-class awareness of hygiene is further fueling market growth.
- Latin America: Showing steady growth in the food processing segment, particularly in Brazil and Argentina, which are major global exporters of meat and agricultural products requiring high sanitation standards.
- Middle East & Africa: Driven by massive infrastructure projects and the expansion of the luxury hospitality sector in the GCC countries, particularly Saudi Arabia and the UAE.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Industrial Institutional Cleaning Chemicals Market.- Ecolab Inc.
- Diversey Holdings Ltd.
- BASF SE
- Clariant AG
- Solvay S.A.
- The Dow Chemical Company
- Stepan Company
- Henkel AG & Co. KGaA
- Procter & Gamble Professional
- Reckitt Benckiser Group plc
- 3M Company
- Kimberly-Clark Professional
- AkzoNobel N.V.
- Croda International PLC
- Huntsman Corporation
- Spartan Chemical Company, Inc.
- Zep Inc.
- Pilot Chemical Corp.
- Evonik Industries AG
- Church & Dwight Co., Inc.
Frequently Asked Questions
What is the projected market size of the Industrial Institutional Cleaning Chemicals market by 2034?
The market is projected to reach approximately USD 116.4 Billion by 2034, growing at a CAGR of 7.4% from 2026, driven by rising hygiene standards and industrial expansion.
Which region is expected to show the fastest growth in the I&I cleaning chemicals sector?
The Asia-Pacific region is expected to be the fastest-growing market, with a projected CAGR of 8.9% due to rapid urbanization, healthcare infrastructure development, and increased food safety regulations.
What are the key trends currently shaping the cleaning chemicals market?
Primary trends include the shift toward bio-based and biodegradable surfactants, the adoption of IoT-enabled smart dispensing systems for precise chemical use, and the development of specialized viral-load reducing disinfectants.
How is the "Green Chemistry" movement affecting institutional chemical procurement?
Institutional buyers are increasingly prioritizing products with third-party eco-certifications (like EPA Safer Choice or EU Ecolabel) to meet sustainability goals, forcing manufacturers to reformulate products using non-toxic, plant-derived ingredients.
Which application segment holds the largest share of the market?
The Commercial segment, which includes the hospitality, retail, and food service industries, currently holds the largest market share, though the Healthcare segment is growing at the fastest rate within the institutional category.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
