Industrial Hemp Market
Industrial Hemp Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_700244 | Published On : October 05, 2026 |
Format : 


 | Author : Jonathan Sikka
Industrial Hemp Market Size
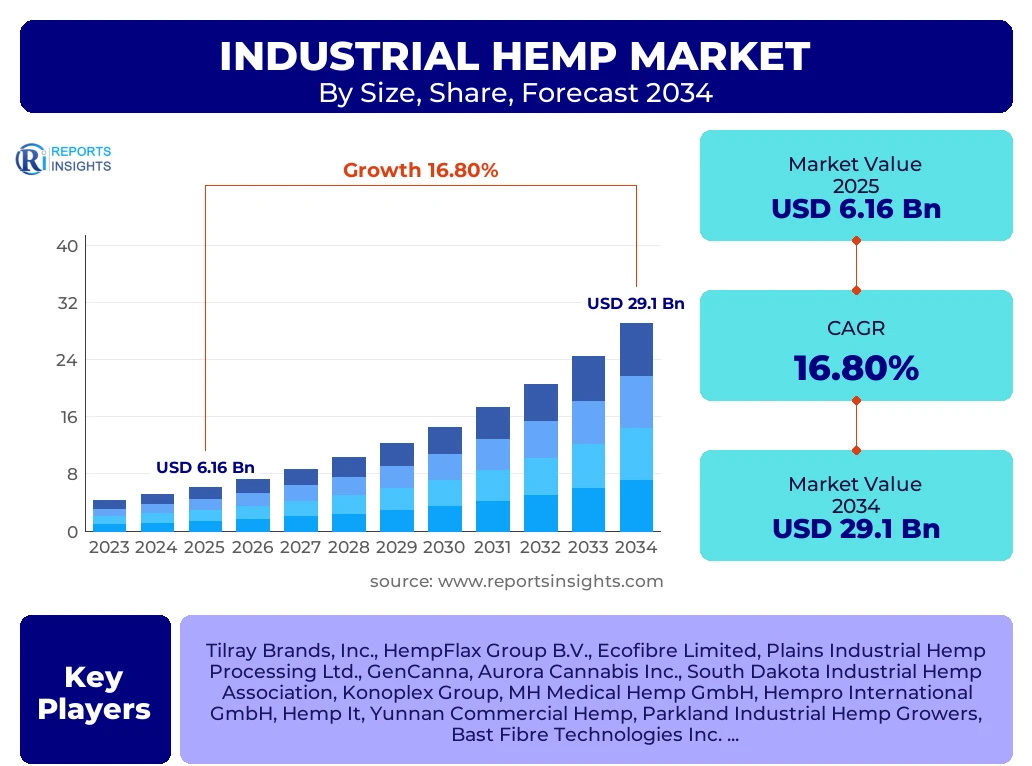
According to Reports Insights Consulting Pvt Ltd, The Industrial Hemp Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 16.8% between 2025 and 2034. The market is estimated at USD 7.2 Billion in 2026 and is projected to reach USD 29.1 Billion by the end of the forecast period in 2034.
Key Industrial Hemp Market Trends & Insights
The global industrial hemp market is undergoing a significant transformation, driven by the shift toward sustainable manufacturing and the legalization of hemp cultivation across major economies. Stakeholders are increasingly focusing on the versatility of the hemp plant, which yields seeds, fibers, and hurds, each serving distinct industrial purposes. Regional insights indicate that North America and Asia-Pacific are leading the charge, supported by favorable government policies and a growing consumer preference for bio-based products. Competitive benchmarking reveals that leading companies are investing heavily in processing technologies to improve fiber quality and reduce extraction costs, thereby making hemp more competitive against synthetic alternatives. The integration of hemp into the textile and construction sectors is identified as a primary growth lever, as industries seek to reduce their carbon footprint through carbon-sequestering materials.
- Largest Region: North America remains the largest region in terms of market share, primarily due to the early adoption of hemp-derived products and the 2018 Farm Bill in the United States.
- Fastest Growing Region: Asia-Pacific is anticipated to be the fastest-growing region, fueled by massive production capacities in China and evolving regulations in India and Thailand.
- Leading Segment by Value: The hemp fiber segment holds the largest share by value, driven by high demand from the textile, automotive, and paper industries.
- Emerging Trend: The rise of hempcrete in the construction industry is gaining traction as a sustainable, fire-resistant, and carbon-negative building material.
Key Takeaways Industrial Hemp Market Size & Forecast
The market forecast for industrial hemp remains robust, underpinned by its alignment with global sustainability goals and the Circular Economy framework. Analyzing common user queries reveals a high interest in the scalability of hemp processing and its economic viability compared to cotton or timber. The forecast period between 2025 and 2034 is expected to witness a transition from niche application to mainstream industrial integration. This growth is supported by advancements in decortication technology, which allows for more efficient separation of hemp fibers and hurds. Furthermore, the expansion of the hemp-based food and beverage market, particularly in the plant-based protein sector, is providing a steady revenue stream for cultivators and processors alike.
- Market Dominance: The industrial application segment, including textiles and biocomposites, is expected to dominate the market share throughout the forecast period.
- Regulatory Impact: Progressive legalization in European and Latin American countries is unlocking new supply chains and reducing trade barriers for hemp-derived raw materials.
- Investor Sentiment: Significant capital inflow is being directed toward R and D for hemp-based bioplastics as a solution to global plastic pollution.
- Key Leading Country: China is the global leader in hemp fiber production and export, accounting for a substantial portion of the global supply chain.
Industrial Hemp Market Drivers Analysis
The primary driver for the industrial hemp market is the global shift toward environmentally friendly and sustainable raw materials. As industries face increasing pressure from both regulators and consumers to lower their environmental impact, hemp offers a viable alternative to petroleum-based plastics and high-water-consumption crops like cotton. Hemp requires significantly less water, fewer pesticides, and has a shorter growth cycle, making it an attractive option for sustainable agriculture. Additionally, the carbon sequestration capabilities of hemp are positioning it as a key player in the carbon credit market, providing farmers with additional economic incentives.
Another major driver is the expanding functional food and personal care sectors. Hemp seeds and oil are rich in omega fatty acids and proteins, making them highly desirable in the health-conscious consumer market. The legalization of hemp-derived CBD in various jurisdictions has also catalyzed market growth, although industrial applications remain the core long-term value driver. Strategic partnerships between hemp processors and automotive manufacturers are also increasing, as the industry looks to use hemp fibers in interior panels and insulation for weight reduction and improved recyclability.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift toward Sustainable Textiles | +4.2% | Global / Europe | 2025 - 2034 |
| Legalization and Regulatory Support | +3.8% | USA, Thailand, India | 2025 - 2029 |
| Demand for Plant-Based Proteins | +3.1% | North America / UK | 2026 - 2034 |
Industrial Hemp Market Restraints Analysis
Despite the optimistic growth projections, the industrial hemp market faces substantial restraints, primarily related to the lack of standardized processing infrastructure. In many regions, the technology required for high-volume decortication and fiber refining is still in its infancy or requires significant capital investment. This lack of infrastructure leads to bottlenecks in the supply chain, often resulting in higher prices for hemp-derived raw materials compared to established commodities. Without localized processing facilities, transportation costs also increase, negating some of the environmental benefits and economic advantages of the crop.
Regulatory inconsistency remains a significant hurdle. While hemp is legally distinguished from high-THC cannabis in many countries, the testing requirements, licensing fees, and transportation laws vary significantly between borders and even within states. This creates a complex compliance landscape for multinational companies and inhibits the free flow of hemp goods. Furthermore, the risk of cross-pollination with recreational or medical cannabis crops creates friction in agricultural planning and zoning, often leading to restrictive local ordinances that limit cultivation scale.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Infrastructure Bottlenecks | -2.5% | Africa, Latin America | 2025 - 2030 |
| Regulatory Ambiguity | -1.8% | Global / EU | 2025 - 2034 |
Industrial Hemp Market Opportunities Analysis
The development of hemp-based biocomposites presents a massive opportunity for the industrial hemp market. As the automotive and aerospace industries seek lightweight materials to improve fuel efficiency and reduce emissions, hemp-reinforced polymers are emerging as a high-performance, sustainable solution. These materials offer comparable strength to glass fibers while being lighter and more biodegradable. Companies that can innovate in the treatment and bonding of hemp fibers with various resins stand to capture significant market share in the advanced materials sector.
Furthermore, the "Green Building" movement provides a burgeoning market for hempcrete and hemp insulation. Unlike traditional concrete, hempcrete is carbon-negative, as it stores more carbon than is emitted during its production. With the rising global focus on decarbonizing the built environment, hemp-based construction materials are moving from experimental use to commercial-scale projects. This opportunity is particularly relevant in Europe and North America, where building codes are increasingly favoring materials with low embodied carbon and high thermal efficiency.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Hemp-based Bioplastics | +5.5% | Global / APAC | 2027 - 2034 |
| Green Construction Materials | +4.7% | Europe / North America | 2026 - 2034 |
Industrial Hemp Market Challenges Impact Analysis
One of the most pressing challenges is the volatility of crop yields and the lack of specialized harvesting equipment. Industrial hemp requires specific agricultural machinery for cutting and gathering, which is often expensive and not readily available in all regions. Farmers frequently have to adapt existing equipment, which can lead to crop damage and reduced quality of the fiber or seeds. Additionally, hemp is sensitive to soil conditions and climate variability, and the lack of specialized crop insurance for hemp in many countries increases the financial risk for small-scale cultivators.
The market also faces a challenge in the form of public perception and the residual stigma associated with the cannabis plant family. Although industrial hemp is a non-psychoactive variety, consumer confusion can occasionally lead to resistance or increased scrutiny from financial institutions and marketing platforms. This stigma can affect everything from bank loans for hemp businesses to the ability of brands to advertise hemp-based food products on social media. Overcoming these educational barriers is essential for the industry to reach its full market potential.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lack of Specialized Machinery | -1.5% | North America / India | 2025 - 2028 |
| Market Stigma & Financial Barriers | -1.2% | Global | 2025 - 2034 |
Industrial Hemp Market - Updated Report Scope
The updated report provides a comprehensive analysis of the industrial hemp ecosystem, covering the entire value chain from cultivation to end-use applications. This study includes detailed projections, competitive landscapes, and technological assessments across five major geographic regions. The scope encompasses various hemp types, including those grown for fiber, seed, and oil, while analyzing the socio-economic impacts of hemp legalization and the integration of hemp into global industrial supply chains.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 6.16 Billion |
| Market Forecast in 2034 | USD 29.1 Billion |
| Growth Rate | 16.8% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Tilray Brands, Inc., HempFlax Group B.V., Ecofibre Limited, Plains Industrial Hemp Processing Ltd., GenCanna, Aurora Cannabis Inc., South Dakota Industrial Hemp Association, Konoplex Group, MH Medical Hemp GmbH, Hempro International GmbH, Hemp It, Yunnan Commercial Hemp, Parkland Industrial Hemp Growers, Bast Fibre Technologies Inc., Cavac Biomatériaux, Panda Biotech, LLC, Western Grain Cleaning and Processing, Global Hemp Group Inc., American Hemp, Dun Agro Hemp Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The industrial hemp market is segmented primarily by product type and end-use application, reflecting the versatile nature of the crop. The fiber segment is traditionally the strongest, serving the textile and paper industries, while the hurd segment is seeing rapid growth due to its application in building materials. The seed segment is driven by the nutraceutical and food industries, where hemp is valued for its high protein and mineral content. Segmentation by source also highlights a growing preference for organic hemp, particularly in the personal care and dietary supplement markets.
- By Type:
- Hemp Fiber (Long fiber and short fiber)
- Hemp Seeds (Whole seeds, hulled seeds, seed meal)
- Hemp Hurds (Used for hempcrete and animal bedding)
- Hemp Oil (Edible oil and industrial oil)
- By Source:
- Organic
- Conventional
- By Application:
- Textiles (Clothing, rope, canvas)
- Personal Care (Lotions, soaps, cosmetics)
- Food and Beverage (Milk, protein powder, snacks)
- Animal Care (Bedding, feed supplements)
- Construction (Hempcrete, insulation)
- Automotive (Biocomposites for interior panels)
- Paper (Specialty paper, cigarette paper)
Regional Highlights
- North America: This region holds the largest market share, with the United States and Canada leading in hemp seed and CBD-related production. The 2018 Farm Bill was a pivotal moment, allowing for large-scale industrial cultivation.
- Asia-Pacific: Projected as the fastest-growing market, Asia-Pacific benefits from China’s massive hemp fiber industry. China accounts for nearly half of the world’s hemp fiber production, exporting primarily to Europe and North America.
- Europe: A mature market for industrial hemp, with France being a major producer of hemp seeds. The European Green Deal is expected to further boost hemp usage in construction and textiles.
- Latin America: Countries like Uruguay and Colombia are emerging as cost-effective cultivation hubs, targeting export markets for hemp biomass and textiles.
- Middle East and Africa: South Africa is leading regional growth following regulatory shifts that recognize hemp as an industrial crop, aiming to revitalize the local textile industry.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Industrial Hemp Market.- Tilray Brands, Inc.
- HempFlax Group B.V.
- Ecofibre Limited
- Plains Industrial Hemp Processing Ltd.
- GenCanna
- Aurora Cannabis Inc.
- South Dakota Industrial Hemp Association
- Konoplex Group
- MH Medical Hemp GmbH
- Hempro International GmbH
- Hemp It
- Yunnan Commercial Hemp
- Parkland Industrial Hemp Growers
- Bast Fibre Technologies Inc.
- Cavac Biomatériaux
- Panda Biotech, LLC
- Western Grain Cleaning and Processing
- Global Hemp Group Inc.
- American Hemp
- Dun Agro Hemp Group
Frequently Asked Questions
What is the current market size of the Industrial Hemp industry?
The industrial hemp market is estimated to be valued at approximately USD 6.16 Billion in 2025, with projections to reach USD 29.1 Billion by 2034, growing at a CAGR of 16.8%.
Which industry application is driving the most growth for hemp?
The textile industry is currently the largest driver by value, but the construction sector (hempcrete) and the automotive biocomposite sector are showing the most rapid growth potential.
Who are the leading producers of industrial hemp globally?
China is the global leader in hemp fiber production, while the United States and France are leading producers of hemp for seeds and oil-related industrial applications.
What are the main benefits of using hemp over cotton?
Hemp requires about half the water of cotton, can grow without the use of most pesticides, produces more fiber per acre, and actually improves soil health through phytoremediation.
What are the primary challenges facing the industrial hemp market?
Key challenges include a lack of specialized harvesting and decortication machinery, regulatory inconsistencies across different countries, and the high initial cost of infrastructure development.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
