Industrial Films Market
Industrial Films Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711725 | Published On : November 13, 2026 |
Format : 


 | Author : Jonathan Sikka
Industrial Films Market Size
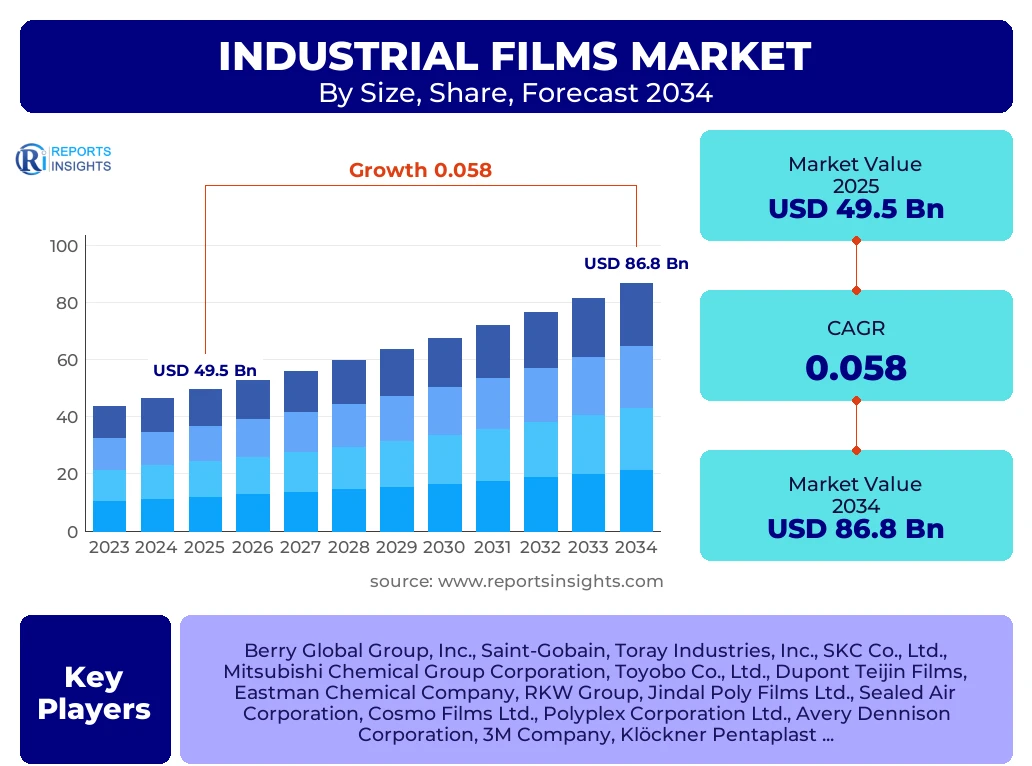
According to Reports Insights Consulting Pvt Ltd, The Industrial Films Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 52.4 Billion in 2026 and is projected to reach USD 86.8 Billion by the end of the forecast period in 2034.
Key Industrial Films Market Trends & Insights
The global industrial films landscape is currently navigating a period of significant transition, driven by the dual imperatives of material science innovation and stringent environmental sustainability goals. Market participants are increasingly focusing on high-performance polymers that offer enhanced barrier properties while reducing overall material consumption. Regional shifts indicate a massive pivot toward the Asia-Pacific region, fueled by rapid industrialization and the expansion of manufacturing hubs in emerging economies. The integration of advanced manufacturing techniques, such as multi-layer co-extrusion, has allowed for the creation of thinner, stronger films that cater to specialized requirements in the medical, construction, and aerospace sectors. Competitive benchmarking reveals that top-tier companies are prioritizing circular economy initiatives, investing heavily in chemically recycled resins and bio-based alternatives to traditional petroleum-derived plastics.
- Largest Region: Asia-Pacific remains the dominant market shareholder, accounting for over 42% of the global revenue due to its robust manufacturing base and infrastructure development.
- Fastest Growing Region: Southeast Asia and India are projected to witness the highest CAGR as domestic manufacturing capabilities and construction activities accelerate.
- Largest Material Segment: Linear Low-Density Polyethylene (LLDPE) continues to lead the market owing to its superior tensile strength and puncture resistance.
- Leading End-Use Segment: The construction industry represents the largest application area, utilizing films for vapor barriers, protection, and insulation.
Key Takeaways Industrial Films Market Size & Forecast
The industrial films market is entering a phase of sustained growth, underpinned by the rising demand for efficient protective solutions across diverse industrial verticals. Strategic forecasts suggest that the intersection of technological advancement and regulatory pressure will be the primary catalyst for market evolution. Stakeholders are shifting their focus from generic film production to value-added, specialty films that provide functional benefits such as UV protection, antimicrobial properties, and high thermal stability. As global supply chains stabilize, the emphasis is moving toward localized production to mitigate logistics costs and carbon footprints, further shaping the competitive dynamics of the industry through 2034.
- Market Valuation: The total market value is expected to surpass the USD 85 billion mark by 2034, reflecting a stable and resilient growth trajectory.
- Material Evolution: Bio-polyethylene and recycled PET (rPET) films are gaining significant market share as corporations align with ESG (Environmental, Social, and Governance) targets.
- Infrastructure Impact: Major infrastructure projects in developing nations are creating a consistent demand for heavy-duty construction films and geomembranes.
- Innovation Focus: Development of smart films with integrated sensors for structural health monitoring or cargo tracking is emerging as a high-potential niche.
Industrial Films Market Drivers Analysis
The primary drivers of the industrial films market are rooted in the expansion of global manufacturing and the critical need for advanced protective materials. As industries such as electronics and pharmaceuticals grow, the demand for contamination-free, high-barrier packaging and protective layers becomes paramount. Additionally, the global push for infrastructure modernization requires massive quantities of durable films for moisture control and soil stabilization.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Urbanization and Infrastructure Projects | +1.8% | China, India, Southeast Asia | 2025–2034 |
| Rising Demand for High-Barrier Medical Films | +1.2% | North America, Europe | 2026–2034 |
| Advancements in Agriculture (Greenhouse Films) | +0.9% | Brazil, USA, Spain | 2025–2030 |
| E-commerce Expansion and Industrial Packaging | +1.4% | Global | 2025–2034 |
Industrial Films Market Restraints Analysis
Market growth is tempered by volatile raw material prices and increasingly stringent environmental regulations concerning single-use plastics. The fluctuating cost of crude oil directly impacts the price of polymer resins, creating uncertainty for manufacturers. Furthermore, legislative bans on certain types of non-biodegradable films in various jurisdictions force companies to undergo expensive R&D transitions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Petrochemical Feedstock Prices | -0.8% | Global | Ongoing |
| Strict Plastic Waste Management Regulations | -1.1% | European Union, Canada | 2025–2034 |
Industrial Films Market Opportunities Analysis
The shift toward a circular economy presents the most significant opportunity for market players. Developing recyclable multi-layer films that maintain high performance while being compatible with standard recycling streams is a major area for growth. Additionally, the automotive sector's transition to electric vehicles (EVs) creates new requirements for specialized insulation and battery-wrap films.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based and Compostable Films | +2.1% | Western Europe, North America | 2026–2034 |
| EV Battery Insulation and Protective Films | +1.5% | Japan, South Korea, Germany | 2025–2034 |
| Nanotechnology-enabled Functional Films | +0.7% | USA, Japan | 2027–2034 |
Industrial Films Market Challenges Impact Analysis
Key challenges include the technical difficulty of recycling multi-material laminates and the high initial investment required for advanced extrusion machinery. Small and medium-sized enterprises (SMEs) often struggle to keep pace with the rapid technological changes and the high cost of certifying new materials for medical or aerospace use.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Complexity in Laminated Film Recycling | -0.6% | Developed Markets | 2025–2030 |
| Supply Chain Disruptions in Specialty Resins | -0.4% | Global | 2025–2028 |
Industrial Films Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global industrial films market, covering material types, film categories, and extensive end-use applications. The study offers granular data on market sizing, year-on-year growth projections, and competitive landscape assessments across six major geographic regions. By integrating macroeconomic indicators with industry-specific micro-trends, the report serves as a strategic roadmap for stakeholders looking to identify high-growth niches and navigate regulatory complexities.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 49.5 Billion |
| Market Forecast in 2034 | USD 86.8 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Berry Global Group, Inc., Saint-Gobain, Toray Industries, Inc., SKC Co., Ltd., Mitsubishi Chemical Group Corporation, Toyobo Co., Ltd., Dupont Teijin Films, Eastman Chemical Company, RKW Group, Jindal Poly Films Ltd., Sealed Air Corporation, Cosmo Films Ltd., Polyplex Corporation Ltd., Avery Dennison Corporation, 3M Company, Klöckner Pentaplast, Garware Hi-Tech Films, Mitsui Chemicals, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The industrial films market is highly fragmented based on material chemistry and functional requirements. Material segmentation reveals the dominance of polyethylene derivatives due to their versatility and cost-effectiveness. Application-based segmentation highlights the critical role of these films in protecting high-value assets and ensuring structural integrity in harsh environments. The move toward "Smart Films" is a notable sub-segment growth area, where films are engineered with specific optical or electrical properties for high-tech applications.
- By Material:
- LLDPE: Dominated by stretch and industrial wrap applications.
- PET: Preferred for high-temperature stability and electrical insulation.
- Polypropylene (PP): Widely used for biaxially oriented (BOPP) films.
- PVC: Utilized for construction and protective sleeves.
- Polyamide (PA): High-barrier properties for medical and chemical containment.
- By Film Type:
- Barrier Films: Essential for pharmaceuticals and chemical resistance.
- Stretch and Shrink Films: Critical for logistics and unitization of pallet loads.
- Specialty Films: Includes anti-fog, UV-resistant, and conductive films.
- By End-Use Industry:
- Construction: Vapor barriers, floor protection, and insulation.
- Agriculture: Silage bags, mulch films, and greenhouse covers.
- Medical: Sterile packaging and surgical drapes.
- Transportation: Surface protection during vehicle transit.
Regional Highlights
- Asia-Pacific: The largest market, driven by China's massive manufacturing output and India's construction boom. The region accounts for the highest consumption of LLDPE and HDPE films.
- North America: A mature market focused on innovation in medical-grade and aerospace films. The US is a leader in the development of sustainable and bio-based film technologies.
- Europe: Driven by strict environmental mandates, Europe is the global leader in the adoption of recycled-content films and circular economy practices.
- Latin America: Growth is primarily centered in Brazil and Mexico, focusing on agricultural films and industrial packaging for export commodities.
- Middle East & Africa: Significant potential in the construction and oil & gas sectors for heavy-duty protective films and geomembranes.

Top Key Players
The market research report includes a detailed profile of leading top-wise companies in the Industrial Films Market. These organizations are categorized based on their manufacturing capacity, technological innovation, and geographic footprint.
- Berry Global Group, Inc.
- Saint-Gobain S.A.
- Toray Industries, Inc.
- SKC Co., Ltd.
- Mitsubishi Chemical Group Corporation
- Toyobo Co., Ltd.
- Dupont Teijin Films
- Eastman Chemical Company
- RKW Group
- Jindal Poly Films Ltd.
- Sealed Air Corporation
- Cosmo Films Ltd.
- Polyplex Corporation Ltd.
- Avery Dennison Corporation
- 3M Company
- Klöckner Pentaplast
- Garware Hi-Tech Films
- Mitsui Chemicals, Inc.
- Uflex Ltd.
- Trioworld Group
Frequently Asked Questions
What is the current size of the global Industrial Films market?
The global Industrial Films market is estimated at USD 49.5 billion in 2025 and is expected to grow steadily toward USD 86.8 billion by 2034.
Which material is most widely used in the production of industrial films?
Linear Low-Density Polyethylene (LLDPE) is the most widely used material due to its excellent flexibility, tensile strength, and cost-to-performance ratio.
What are the primary growth drivers for the industrial films industry?
Growth is primarily driven by the expansion of the construction sector, rising demand for high-barrier packaging in the pharmaceutical industry, and the increasing use of protective films in manufacturing and logistics.
How is the move toward sustainability affecting the market?
Sustainability is forcing a shift toward mono-material films, bio-based resins, and products with high post-consumer recycled (PCR) content to meet regulatory and consumer demands.
Which region is expected to show the fastest growth rate?
The Asia-Pacific region, specifically emerging economies like India and Southeast Asian nations, is expected to exhibit the fastest growth due to rapid industrialization and infrastructure investment.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
