In Vitro Diagnostic Market
In Vitro Diagnostic Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_705756 | Published On : October 15, 2026 |
Format : 


 | Author : Erika Grotto
In Vitro Diagnostic Market Size
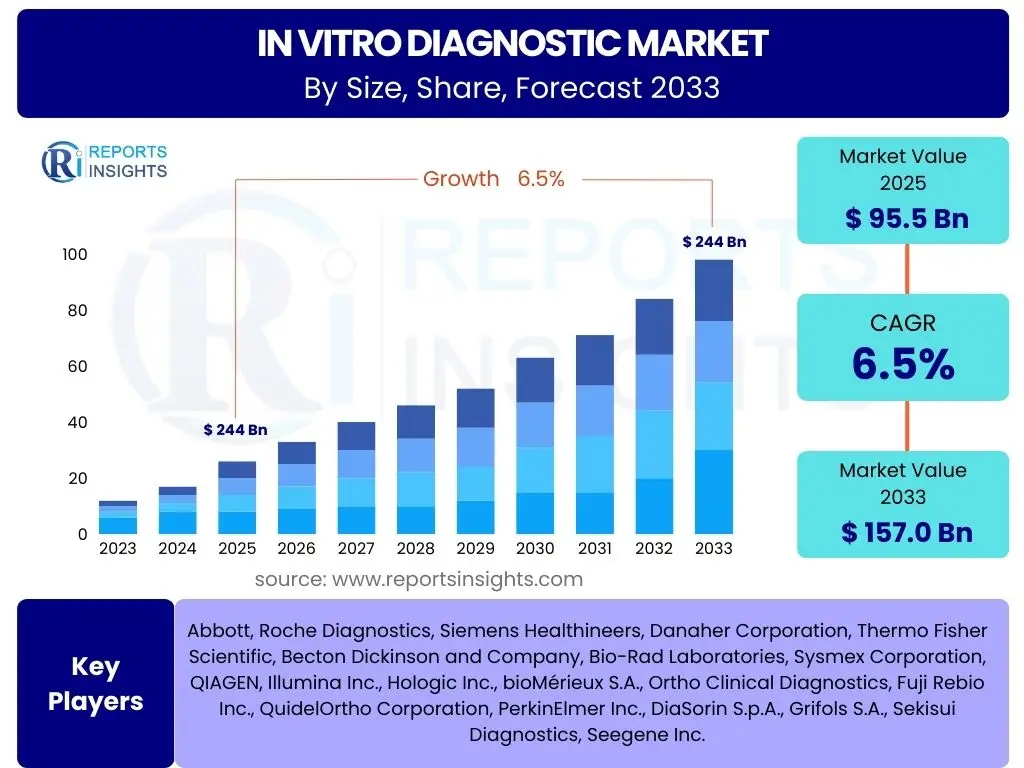
According to Reports Insights Consulting Pvt Ltd, The In Vitro Diagnostic Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 115.62 Billion in 2026 and is projected to reach USD 176.18 Billion by the end of the forecast period in 2034.
Key In Vitro Diagnostic Market Trends & Insights
The global In Vitro Diagnostic (IVD) market is undergoing a profound transformation driven by the integration of digital health technologies, the decentralization of testing, and the rising demand for personalized medicine. Enterprise stakeholders are increasingly focusing on the shift from traditional laboratory-based testing to Point-of-Care (POC) and Near-Patient Testing (NPT), which facilitates faster clinical decision-making and improved patient outcomes. Furthermore, the convergence of Artificial Intelligence (AI) and Machine Learning (ML) with diagnostic platforms is enhancing the accuracy of complex data interpretation, particularly in molecular diagnostics and oncology. The market is also witnessing a significant move toward liquid biopsy and non-invasive diagnostic procedures, which offer a safer and more convenient alternative to conventional biopsies. Regional analysis suggests that while North America remains the dominant revenue generator due to advanced healthcare infrastructure, the Asia-Pacific region is emerging as the fastest-growing market, propelled by expanding healthcare access and increasing investments in diagnostic laboratory networks.
- Largest Region: North America currently holds the largest market share, driven by high healthcare expenditure and early adoption of advanced diagnostic technologies.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period due to large patient populations and rising healthcare awareness in China and India.
- Largest Product Segment: Reagents and Consumables represent the largest segment by revenue, fueled by the continuous and recurring need for these products in routine and specialized testing.
- Leading Technology Segment: Immunoassay/Immunochemistry remains the dominant technology segment, widely utilized for detecting infectious diseases, cardiovascular markers, and oncology indicators.
- Key Market Trend: Increasing integration of AI and big data analytics in IVD platforms to streamline workflow and improve diagnostic precision.
Key Takeaways In Vitro Diagnostic Market Size & Forecast
The In Vitro Diagnostic market is characterized by robust growth prospects linked to the rising global burden of chronic and infectious diseases. The shift toward value-based care and the implementation of stringent regulatory frameworks across major economies are shaping the competitive landscape. Stakeholders are prioritizing the development of companion diagnostics, which play a critical role in the growth of targeted therapies. The forecast indicates that while the reagents segment will continue to dominate, the molecular diagnostics technology will see the most significant upward trajectory. Strategic collaborations between diagnostic manufacturers and pharmaceutical companies are expected to accelerate the commercialization of novel assays, particularly in the field of oncology and rare diseases. Additionally, the expansion of lab automation and the adoption of high-throughput screening are critical factors that will drive operational efficiency in diagnostic laboratories through 2034.
- Market Growth: The market will see steady expansion, reaching over USD 176 billion by 2034, supported by the growing aging population.
- Infectious Disease Testing: This remains a primary application area, significantly boosted by the lessons learned from global pandemic preparedness.
- Point-of-Care Expansion: Rapid testing kits and portable diagnostic devices are seeing unprecedented demand in home-care settings and outpatient clinics.
- Strategic Mergers: The industry is witnessing a trend of consolidation as major players acquire niche technology firms to broaden their molecular diagnostic portfolios.
- Regional Leadership: The United States and Western Europe remain the primary hubs for diagnostic innovation and high-value laboratory services.
In Vitro Diagnostic Market Drivers Analysis
The primary drivers of the In Vitro Diagnostic market include the rising prevalence of chronic conditions such as diabetes, cardiovascular diseases, and cancer, which necessitate frequent and accurate diagnostic monitoring. Technological advancements in genomic and proteomic research have also paved the way for sophisticated diagnostic tools that offer higher sensitivity and specificity. Furthermore, the global shift toward early disease detection and preventive healthcare is encouraging governments and private insurers to incentivize diagnostic screening programs. The expansion of healthcare infrastructure in emerging economies further accelerates the adoption of modern IVD systems in clinical settings.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Incidence of Chronic and Infectious Diseases | +1.8% | Global (High impact in North America and Europe) | 2025-2034 |
| Advancements in Molecular Diagnostics and Genomics | +1.5% | United States, Germany, Japan | 2026-2034 |
| Growing Demand for Point-of-Care (POC) Testing | +1.2% | China, India, Brazil, Southeast Asia | 2025-2030 |
| Integration of AI and Laboratory Automation | +0.9% | Advanced Economies (US and EU) | 2027-2034 |
In Vitro Diagnostic Market Restraints Analysis
Despite strong growth, the In Vitro Diagnostic market faces challenges such as stringent and often divergent regulatory approval processes across different jurisdictions, which can delay the launch of innovative products. High costs associated with advanced diagnostic instruments, particularly in molecular diagnostics, limit their adoption in budget-constrained healthcare settings in developing regions. Additionally, the lack of a standardized reimbursement landscape for novel diagnostic tests, such as liquid biopsies and genetic screenings, poses a significant barrier to widespread clinical implementation.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Frameworks and Approval Hurdles | -0.8% | United States (FDA), European Union (IVDR) | 2025-2034 |
| High Instrument Costs and Limited Budgets | -0.6% | Middle East, Africa, Parts of Latin America | 2025-2029 |
| Inadequate Reimbursement Policies for Advanced Tests | -0.5% | Global (Developing Markets specifically) | 2026-2032 |
In Vitro Diagnostic Market Opportunities Analysis
Significant opportunities reside in the development of companion diagnostics, which assist in selecting the most effective treatment for individual patients based on their genetic profile. The expansion of the direct-to-consumer (DTC) testing market also presents a new revenue stream as patients become more proactive about their health. Furthermore, the integration of IVD with tele-health platforms creates a seamless diagnostic-to-treatment pathway. Emerging markets in Asia and Latin America represent vast untapped potential due to their rapidly improving healthcare systems and increasing per capita medical spending.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Companion Diagnostics for Oncology | +1.4% | United States, Europe, China | 2025-2034 |
| Growth in Direct-to-Consumer Genetic Testing | +1.1% | North America and Western Europe | 2026-2034 |
| Infrastructure Modernization in Emerging Markets | +1.3% | APAC and Latin America | 2025-2034 |
In Vitro Diagnostic Market Challenges Impact Analysis
The industry must navigate the challenge of maintaining data privacy and cybersecurity as diagnostic systems become increasingly networked and cloud-based. Another critical challenge is the global shortage of skilled laboratory professionals capable of operating sophisticated molecular diagnostic platforms. Furthermore, supply chain vulnerabilities, particularly for specialized reagents and electronic components for diagnostic hardware, remain a concern for maintaining consistent production levels.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Risks in Connected Diagnostic Devices | -0.4% | North America and Europe | 2025-2034 |
| Shortage of Trained Pathologists and Lab Technicians | -0.5% | Global | 2025-2034 |
| Supply Chain Disruptions for Rare Reagents | -0.3% | Global | Short to Medium Term |
In Vitro Diagnostic Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global In Vitro Diagnostic market across various dimensions, including product type, technology, application, end-user, and geography. It provides granular insights into market dynamics, competitive intensity, and the regulatory landscape. The study identifies high-growth segments and evaluates the impact of macroeconomic factors on market evolution through the forecast period of 2026 to 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 109.68 Billion |
| Market Forecast in 2034 | USD 176.18 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Roche Diagnostics, Abbott Laboratories, Danaher Corporation, Siemens Healthineers, Thermo Fisher Scientific, Sysmex Corporation, Becton, Dickinson and Company (BD), Bio-Rad Laboratories, Inc., QIAGEN N.V., Ortho Clinical Diagnostics (QuidelOrtho), bioMérieux SA, Agilent Technologies, Inc., DiaSorin S.p.A., Myriad Genetics, Inc., Hologic, Inc., Illumina, Inc., Revvity, Inc., Grifols, S.A., Sonic Healthcare, Quest Diagnostics. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The In Vitro Diagnostic market is segmented primarily by product and service, technology, and application. The Reagents and Consumables segment holds the largest share due to the recurring sales model and the high volume of tests performed daily. In terms of technology, Immunoassays lead the market, although Molecular Diagnostics is the fastest-growing segment, driven by its high precision in detecting genetic mutations and viral loads. Application-wise, infectious disease testing remains the dominant segment, while oncology and cardiology are witnessing rapid growth due to the rising need for early diagnosis and treatment monitoring.
- By Product & Service:
- Reagents & Consumables (Assays, Buffers, Calibrators)
- Instruments (Fully Automated, Semi-automated, POC Devices)
- Software & Services (Laboratory Information Systems, Maintenance)
- By Technology:
- Immunoassay/Immunochemistry (ELISA, CLIA, Rapid Tests)
- Clinical Chemistry (General Chemistry, Specialized Chemistry)
- Molecular Diagnostics (PCR, NGS, In Situ Hybridization)
- Hematology (CBC, Flow Cytometry)
- Microbiology (Culture, Identification)
- Coagulation & Hemostasis
- Urinalysis
- By Application:
- Infectious Diseases (COVID-19, HIV, Hepatitis, Flu)
- Oncology (Cancer Screening and Monitoring)
- Cardiology (Cardiac Markers)
- Nephrology
- Autoimmune Diseases
- Drug Testing/Toxicology
- Diabetes Testing
- By End User:
- Hospital-based Laboratories
- Standalone Clinical Laboratories (Reference Labs)
- Academic & Research Institutes
- Home Care/Point-of-Care Settings
Regional Highlights
- North America: The largest market globally, characterized by advanced lab automation, high healthcare spending, and a strong presence of key market players. The US is a major hub for diagnostic innovation.
- Europe: The second-largest market, with countries like Germany, France, and the UK leading in diagnostic infrastructure. The implementation of the In Vitro Diagnostic Regulation (IVDR) is a key factor influencing market dynamics.
- Asia-Pacific: The fastest-growing region. Rapid urbanization, an aging population, and improving healthcare accessibility in China, India, and Japan are driving significant demand for IVD products.
- Latin America: Expected to show steady growth as countries like Brazil and Mexico invest in modernizing their diagnostic lab networks.
- Middle East and Africa: A developing market with growth potential linked to the increasing prevalence of infectious diseases and government initiatives to improve public health services.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the In Vitro Diagnostic Market.- Roche Diagnostics
- Abbott Laboratories
- Danaher Corporation (Beckman Coulter, Cepheid)
- Siemens Healthineers
- Thermo Fisher Scientific
- Sysmex Corporation
- Becton, Dickinson and Company (BD)
- Bio-Rad Laboratories, Inc.
- QIAGEN N.V.
- Ortho Clinical Diagnostics (QuidelOrtho)
- bioMérieux SA
- Agilent Technologies, Inc.
- DiaSorin S.p.A.
- Myriad Genetics, Inc.
- Hologic, Inc.
- Illumina, Inc.
- Revvity, Inc. (formerly PerkinElmer)
- Grifols, S.A.
- Sonic Healthcare
- Quest Diagnostics
Frequently Asked Questions
What is the current and projected size of the In Vitro Diagnostic market?
The global In Vitro Diagnostic market is estimated at USD 109.68 Billion in 2025 and is projected to grow to USD 176.18 Billion by 2034, expanding at a CAGR of 5.4%.
Which technology segment is expected to grow the fastest?
Molecular Diagnostics is expected to be the fastest-growing technology segment, driven by its high sensitivity in detecting infectious diseases and its role in precision oncology and personalized medicine.
What are the primary factors driving market growth?
Key drivers include the rising global prevalence of chronic and infectious diseases, technological advancements in laboratory automation, and the increasing shift toward point-of-care and rapid testing.
Who are the leading players in the In Vitro Diagnostic market?
The market is led by top companies such as Roche, Abbott, Danaher, Siemens Healthineers, and Thermo Fisher Scientific, who maintain their positions through continuous innovation and strategic acquisitions.
Which region offers the most significant growth opportunities?
While North America is currently the largest market, the Asia-Pacific region offers the most significant growth opportunities due to expanding healthcare infrastructure and a large, aging patient population.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
