High Temperature Thermoplastics Market
High Temperature Thermoplastics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711723 | Published On : November 13, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
High Temperature Thermoplastics Market Size
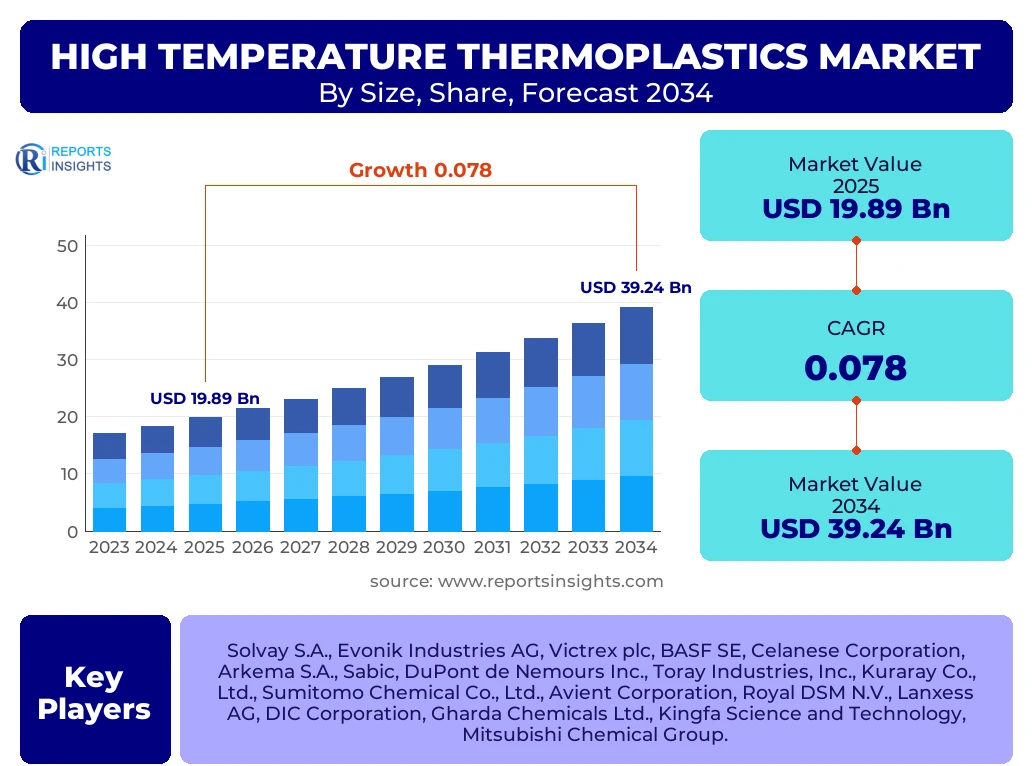
According to Reports Insights Consulting Pvt Ltd, The High Temperature Thermoplastics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2025 and 2034. The market is estimated at USD 21.45 Billion in 2026 and is projected to reach USD 39.24 Billion by the end of the forecast period in 2034.
Key High Temperature Thermoplastics Market Trends & Insights
The global landscape for high temperature thermoplastics (HTTPs) is undergoing a significant transformation driven by the escalating demand for lightweight, high-performance materials capable of withstanding extreme thermal and chemical environments. Current market dynamics reflect a concerted shift toward metal replacement in the aerospace and automotive sectors, where HTTPs offer superior strength-to-weight ratios and resistance to corrosion. Furthermore, the rapid expansion of 5G infrastructure and the miniaturization of electronic components are fueling the adoption of Liquid Crystal Polymers (LCP) and Polyether Ether Ketone (PEEK) due to their exceptional dielectric properties and dimensional stability. Analysts observe a growing emphasis on sustainable manufacturing processes, including the development of bio-based high-performance resins and enhanced recycling protocols for advanced polymers to meet stringent environmental regulations.
- Asia-Pacific is the fastest-growing region due to rapid industrialization and the presence of major electronics and automotive manufacturing hubs in China, India, and South Korea.
- North America remains the largest region by market value, supported by a mature aerospace and defense industry and significant investment in medical technology.
- The Fluoropolymers segment holds the largest market share owing to widespread application in chemical processing, wire and cable insulation, and automotive fuel systems.
- Polyether Ether Ketone (PEEK) is identified as the highest CAGR segment during the forecast period due to its increasing adoption in medical implants and high-stress aerospace components.
- Strategic partnerships and horizontal integration among chemical giants are intensifying to streamline the supply chain for specialty monomers required for HTTP production.
Key Takeaways High Temperature Thermoplastics Market Size & Forecast
The market trajectory for high temperature thermoplastics remains robust, underpinned by a 7.8% CAGR that reflects the critical nature of these materials in modern engineering. As industries transition toward electrification and higher energy efficiency, the role of polymers that can maintain structural integrity above 200 degrees Celsius becomes indispensable. The forecast period anticipates a surge in domestic production capabilities in emerging economies, reducing the reliance on Western imports and optimizing the cost structure of high-performance plastics. Key takeaways highlight the convergence of material science with additive manufacturing, allowing for the 3D printing of complex HTTP parts that were previously impossible to mold or machine efficiently.
- The global market value is set to nearly double by 2034, driven by technological breakthroughs in polymer synthesis.
- China and India are emerging as pivotal consumption centers, transitioning from low-end plastic production to high-value specialty resin manufacturing.
- Transportation, encompassing both EV and traditional aerospace, accounts for over 35% of the total market volume.
- Medical-grade high temperature thermoplastics are seeing increased uptake as they withstand repeated autoclave sterilization cycles better than traditional plastics.
- Innovation in Sulfone polymers (PPSU, PESU) is expected to dominate the plumbing and aerospace interior segments due to their inherent flame retardancy.
High Temperature Thermoplastics Market Drivers Analysis
The primary catalyst for market expansion is the global initiative for vehicle lightweighting to enhance fuel efficiency and extend the range of electric vehicles (EVs). By replacing heavy metal components in under-the-hood applications with high temperature thermoplastics, manufacturers can significantly reduce vehicle weight while ensuring thermal stability and chemical resistance against oils and coolants. Additionally, the continuous advancement in the aerospace sector, particularly for next-generation engines and structural components, necessitates materials that offer high mechanical strength at elevated temperatures. The surge in demand for portable electronic devices and the rollout of 5G networks further drive the market, as these applications require materials with low dissipation factors and high heat resistance during soldering processes.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Automotive Lightweighting & EV Range Optimization | +2.4% | Germany, USA, China | 2025 - 2034 |
| Aerospace Fleet Modernization & Engine Efficiency | +1.8% | France, USA, UK | 2026 - 2032 |
| Miniaturization of Electronic Components & 5G Rollout | +1.5% | South Korea, Taiwan, Japan | 2025 - 2030 |
| Expansion of Medical Device Sterilization Requirements | +1.2% | Global | 2027 - 2034 |
High Temperature Thermoplastics Market Restraints Analysis
Despite the positive growth outlook, the market faces significant hurdles related to the high cost of raw materials and complex processing requirements. High temperature thermoplastics require specialized equipment capable of handling extreme melt temperatures, often exceeding 350 degrees Celsius, which increases capital expenditure for manufacturers. Furthermore, the niche nature of these materials often leads to a fragmented supply chain and price volatility for specialty monomers. Regulatory scrutiny regarding the environmental impact of certain fluoropolymers, particularly those involving PFAS (per- and polyfluoroalkyl substances), also presents a long-term restraint, forcing companies to invest heavily in alternative, compliant chemistries.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Production and Processing Costs | -1.1% | Global | 2025 - 2034 |
| Stringent Environmental Regulations (PFAS) | -0.8% | European Union, USA | 2026 - 2030 |
| Volatility in Specialty Chemical Feedstock | -0.5% | Global | Short Term |
High Temperature Thermoplastics Market Opportunities Analysis
The integration of high temperature thermoplastics in additive manufacturing (3D printing) presents a massive growth frontier. Professional-grade 3D printers can now utilize filaments and powders made of PEEK and PEI, enabling the production of customized, low-volume parts for aerospace and medical implants with zero waste. Another significant opportunity lies in the burgeoning renewable energy sector, specifically in solar thermal and hydrogen fuel cells, where HTTPs are used for gaskets, seals, and structural frames that must endure outdoor exposure and chemical reactivity. Moreover, the push for circular economy models is encouraging the development of high-performance thermoplastic composites that are easier to recycle than thermoset equivalents.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration with Additive Manufacturing (3D Printing) | +1.9% | USA, Germany | 2026 - 2034 |
| Renewable Energy Infrastructure (Hydrogen/Solar) | +1.4% | EU, China | 2028 - 2034 |
| Development of Bio-based High Performance Resins | +1.1% | Global | 2027 - 2034 |
High Temperature Thermoplastics Market Challenges Impact Analysis
One of the most pressing challenges is the technical barrier associated with achieving consistent part quality in high-heat injection molding. Variations in thermal gradients can lead to internal stresses and warping, necessitating advanced simulation tools and highly skilled labor. Additionally, competition from advanced thermoset composites and high-strength metal alloys remains a challenge in specific heavy-industrial applications. The energy-intensive nature of HTTP production also conflicts with corporate sustainability goals, requiring manufacturers to optimize energy consumption and adopt greener energy sources for their production facilities.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Barriers in Injection Molding & Processing | -0.9% | Global | 2025 - 2034 |
| Competition from Advanced Thermosets & Alloys | -0.7% | Japan, USA | 2025 - 2030 |
| High Carbon Footprint of Polymer Synthesis | -0.6% | EU, North America | 2026 - 2034 |
High Temperature Thermoplastics Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the high temperature thermoplastics sector, covering a diverse range of polymer families and their cross-industry applications. The study provides granular data on consumption volumes, pricing trends, and revenue forecasts across five major geographic regions. By evaluating the technological readiness levels of various resins—from widely used fluoropolymers to emerging polyimides—this report serves as a strategic roadmap for stakeholders involved in material science, procurement, and industrial design. Special attention is given to the impact of macroeconomic factors and geopolitical shifts on the global supply chain for specialty chemicals.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 19.89 Billion |
| Market Forecast in 2034 | USD 39.24 Billion |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Solvay S.A., Evonik Industries AG, Victrex plc, BASF SE, Celanese Corporation, Arkema S.A., Sabic, DuPont de Nemours Inc., Toray Industries, Inc., Kuraray Co., Ltd., Sumitomo Chemical Co., Ltd., Avient Corporation, Royal DSM N.V., Lanxess AG, DIC Corporation, Gharda Chemicals Ltd., Kingfa Science and Technology, Mitsubishi Chemical Group. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The high temperature thermoplastics market is characterized by a sophisticated segmentation based on resin chemistry and performance characteristics. Fluoropolymers lead the market in volume, primarily due to their unparalleled chemical inertness and low friction properties, making them vital for the chemical processing and automotive industries. However, in terms of value growth, PEEK and other Polyaryletherketones (PAEK) are dominant as they offer the highest thermal and mechanical performance among all commercial thermoplastics. The segmentation also highlights the rising importance of Polyphthalamide (PPA) as a cost-effective alternative to more expensive resins in under-the-hood automotive applications. From an end-user perspective, the Electrical & Electronics segment is witnessing rapid evolution, moving toward materials with ultra-high heat resistance to support lead-free soldering and high-frequency data transmission.
- By Product Type:
- Fluoropolymers: PTFE, PFA, FEP, PVDF, ETFE
- High-performance Polyamides: Polyphthalamide (PPA)
- Sulfone Polymers: Polyether Sulfone (PESU), Polyphenylsulfone (PPSU), Polysulfone (PSU)
- Polyimides: Polyetherimide (PEI), Polyamide-imide (PAI), Polyimide (PI)
- Liquid Crystal Polymers (LCP)
- Polyether Ether Ketone (PEEK)
- Polyphenylene Sulfide (PPS)
- By End-Use Industry:
- Aerospace & Defense: Engine components, structural parts, interior fasteners
- Transportation: Fuel systems, EV battery components, braking systems
- Electrical & Electronics: Connectors, circuit boards, semiconductor manufacturing parts
- Medical & Healthcare: Surgical instruments, dental tools, implantable devices
- Industrial & Chemical Processing: Pumps, valves, seals, and gaskets
- Energy: Oil & Gas downhole tools, solar panel components
Regional Highlights
The global distribution of the high temperature thermoplastics market shows a clear distinction between innovation hubs and manufacturing powerhouses. North America, particularly the United States, continues to lead in R&D and high-value applications within the aerospace and medical sectors. The presence of major aircraft manufacturers and medical device innovators ensures a steady demand for PEEK and PEI resins. Europe follows closely, with Germany and France serving as centers for automotive engineering excellence, where the focus is on reducing emissions through lightweighting. However, the Asia-Pacific region is the most dynamic, accounting for the highest growth rate. China's shift from being a primary consumer to a major producer of PPS and LCP is reshaping global trade flows. Japan remains a critical player, particularly in the production of high-purity LCP and Sulfone polymers for the electronics industry. The Middle East is also seeing localized growth as regional players diversify from crude oil into downstream high-value specialty chemicals.
- North America: Largest market by revenue, driven by the Boeing-led aerospace ecosystem and advanced healthcare infrastructure.
- Asia-Pacific: Fastest-growing region with a CAGR of 9.2%, powered by China's semiconductor self-sufficiency goals and India's automotive sector expansion.
- Europe: Focused on sustainability and stringent automotive standards, leading the demand for bio-based and recyclable high-performance polymers.
- Rest of the World: Increasing oil and gas exploration in the MEA region is driving the demand for high-temperature seals and coatings.

Top Key Players
The market research report includes a detailed profile of leading top-wise companies in the High Temperature Thermoplastics Market. These organizations are focused on strategic expansion, R&D for next-generation resins, and vertical integration to secure raw material supplies.
- Solvay S.A.
- Evonik Industries AG
- Victrex plc
- BASF SE
- Celanese Corporation
- Arkema S.A.
- Sabic (Saudi Basic Industries Corporation)
- DuPont de Nemours Inc.
- Toray Industries, Inc.
- Kuraray Co., Ltd.
- Sumitomo Chemical Co., Ltd.
- Avient Corporation
- Royal DSM N.V.
- Lanxess AG
- DIC Corporation
- Gharda Chemicals Ltd.
- Kingfa Science and Technology
- Mitsubishi Chemical Group
- Shin-Etsu Chemical Co., Ltd.
- Kureha Corporation
Frequently Asked Questions
Analyzing common user questions about the high temperature thermoplastics market helps clarify the technical and economic landscape for potential investors and engineers.
What defines a thermoplastic as "High Temperature"?
High temperature thermoplastics are typically defined as polymers that maintain their mechanical and physical properties at continuous service temperatures (CST) exceeding 150 degrees Celsius (300 degrees Fahrenheit). These materials often have glass transition temperatures (Tg) and melting points significantly higher than commodity or engineering plastics like polyethylene or nylon.
Which industry is the largest consumer of high temperature thermoplastics?
The transportation sector, including both aerospace and automotive, is currently the largest consumer. In aerospace, they are used to reduce weight in engines and structural components, while in the automotive industry, they are essential for under-the-hood parts that must withstand heat and aggressive chemicals.
Why is PEEK considered a premium material in this market?
Polyether Ether Ketone (PEEK) offers a unique combination of high thermal stability (up to 260 degrees Celsius), excellent chemical resistance, high mechanical strength, and biocompatibility. Its ability to be processed via injection molding, extrusion, and 3D printing makes it incredibly versatile for mission-critical applications.
How does the 5G rollout affect the LCP market?
5G technology requires materials with very low dielectric loss and high dimensional stability to ensure signal integrity at high frequencies. Liquid Crystal Polymers (LCP) are ideal for 5G antenna substrates and connectors because they offer exceptional moisture resistance and low dielectric constants.
Are there sustainable alternatives in the high temperature thermoplastics market?
Yes, manufacturers are increasingly developing bio-based versions of high-performance polyamides and investigating chemical recycling methods for PEEK and PPS. Additionally, the move toward thermoplastic composites allows for easier end-of-life recycling compared to traditional thermoset resins like epoxy.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
