Hemoglobinopathies Market
Hemoglobinopathies Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710935 | Published On : September 19, 2026 |
Format : 


 | Author : Erika Grotto
Hemoglobinopathies Market Size
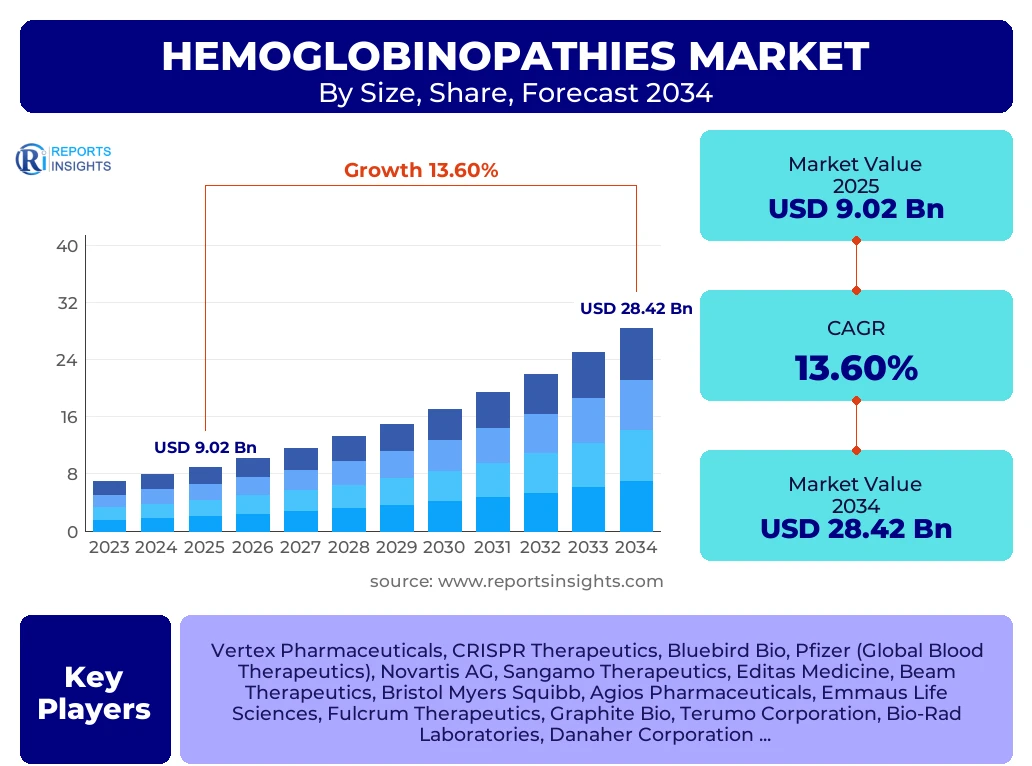
According to Reports Insights Consulting Pvt Ltd, The Hemoglobinopathies Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.6% between 2026 and 2034. The market is estimated at USD 10.25 Billion in 2026 and is projected to reach USD 28.42 Billion by the end of the forecast period in 2034.
Key Hemoglobinopathies Market Trends & Insights
The global hemoglobinopathies market is undergoing a fundamental transformation, shifting from conventional symptomatic management toward curative-intent therapies. This evolution is primarily driven by the clinical success and regulatory approval of gene-editing technologies, such as CRISPR-Cas9, which offer permanent solutions for patients with sickle cell disease and transfusion-dependent thalassemia. Furthermore, the integration of advanced diagnostic screening in newborn programs across emerging economies is facilitating earlier intervention, thereby expanding the patient pool receiving active treatment. Stakeholders are increasingly focusing on specialized care centers and multidisciplinary approaches to manage the complex systemic complications associated with chronic hemoglobin disorders.
Competitive benchmarking reveals a high degree of consolidation among biopharmaceutical giants and specialized biotech firms. Companies are aggressively pursuing orphan drug designations to capitalize on extended market exclusivity and expedited regulatory pathways. Additionally, there is a notable trend toward the development of oral iron chelators and small-molecule therapies that improve patient compliance compared to parenteral alternatives. The convergence of digital health monitoring and personalized medicine is also allowing for more precise titration of therapies, reducing the incidence of vaso-occlusive crises and iron overload-related organ damage.
- North America currently stands as the largest region by revenue, driven by high treatment costs and early adoption of gene therapies.
- The Asia Pacific region is identified as the fastest-growing market due to the high prevalence of thalassemia and improving healthcare infrastructure.
- Sickle Cell Disease (SCD) represents the largest disease segment in terms of market share, supported by a robust pipeline of novel therapeutics.
- Gene therapy is the fastest-growing treatment segment, projected to disrupt traditional blood transfusion and chelation markets.
Key Takeaways Hemoglobinopathies Market Size & Forecast
The long-term outlook for the hemoglobinopathies market remains bullish, characterized by a transition toward high-value, one-time curative treatments. While traditional therapies like blood transfusions and hydroxyurea continue to provide the baseline for care, the entry of blockbuster gene therapies is expected to exponentially increase market valuation. The forecast period anticipates a significant reduction in the long-term economic burden of these diseases as curative treatments reduce the need for lifelong hospitalizations and chronic complications management. Strategic collaborations between healthcare providers and insurers are becoming essential to address the high upfront costs of these innovative modalities.
- The United States is the leading country in the market, supported by significant R and D investment and favorable reimbursement policies for orphan diseases.
- Increased prevalence of genetic blood disorders in the Middle East and Africa is driving demand for cost-effective diagnostic and therapeutic solutions.
- Technological advancements in hematopoietic stem cell transplantation (HSCT) are expanding the eligible patient population by improving donor matching and reducing graft-versus-host disease.
- Government-led initiatives for mandatory newborn screening are pivotal in driving the early-stage diagnostic market segment.
- Market growth is heavily influenced by the expansion of specialty pharmacy networks that handle complex biological and genomic products.
Hemoglobinopathies Market Drivers Analysis
The primary catalysts for market expansion include the rapid advancement of genomic medicine and an increasing global burden of hereditary blood disorders. As genomic sequencing becomes more accessible, the identification of specific genetic mutations allows for the development of targeted therapies. Additionally, the rising awareness among patient populations and healthcare providers regarding the long-term benefits of early intervention is accelerating the adoption of novel treatment protocols. Government subsidies and international health programs aimed at eradicating the complications of sickle cell disease and thalassemia also play a vital role in market stimulation.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Breakthroughs in Gene Editing (CRISPR/Cas9) | +4.2% | Global (Primarily US and EU) | 2025 - 2034 |
| Expansion of Newborn Screening Programs | +2.8% | Asia Pacific and MEA | 2026 - 2030 |
| Rising Prevalence of Sickle Cell Disease | +2.1% | Sub-Saharan Africa and Americas | 2025 - 2034 |
| Orphan Drug Designations and Incentives | +1.5% | North America and Europe | 2025 - 2034 |
Hemoglobinopathies Market Restraints Analysis
Despite the optimistic growth trajectory, the market faces significant headwinds, most notably the astronomical cost of gene therapies which can exceed two million dollars per patient. Such pricing models strain national healthcare budgets and private insurance frameworks, leading to intensive scrutiny and potential access barriers. Furthermore, the logistical complexity of administering advanced therapies, which requires specialized facilities and highly trained personnel, limits the availability of these treatments in low-to-middle-income countries where the disease burden is highest.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Curative Therapies | -3.5% | Global | 2025 - 2034 |
| Limited Access to Specialized Care Centers | -1.8% | Developing Economies | 2026 - 2032 |
| Complications Associated with Long-term Transfusions | -1.2% | Emerging Markets | 2025 - 2030 |
Hemoglobinopathies Market Opportunities Analysis
The market presents substantial opportunities in the development of "off-the-shelf" or in vivo gene therapies that could bypass the need for expensive ex vivo processing. There is also a significant gap in the market for affordable, non-invasive diagnostic tools that can be utilized in resource-limited settings. Expanding therapeutic indications to include less common hemoglobin variants and focusing on pediatric formulations represent untapped revenue streams for pharmaceutical manufacturers. Furthermore, digital therapeutics that help patients manage pain and adhere to chelation schedules offer a growing sub-sector for innovation.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of In Vivo Gene Editing | +3.9% | Global | 2028 - 2034 |
| Focus on Emerging Economies (India, Brazil) | +2.4% | BRIC Nations | 2026 - 2034 |
| Advancements in Oral Chelation Therapy | +1.7% | Global | 2025 - 2030 |
Hemoglobinopathies Market Challenges Impact Analysis
One of the most pressing challenges is the long-term safety monitoring of gene-edited patients, as potential off-target effects or insertional mutagenesis could emerge years after treatment. Regulatory bodies are demanding rigorous long-term follow-up data, which increases the R and D burden on companies. Additionally, the competitive landscape is becoming increasingly crowded, making it difficult for new entrants to differentiate their products. Supply chain issues related to the transport of cryopreserved cellular products also pose a logistical hurdle for global scaling of advanced therapies.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Regulatory Requirements for Gene Therapy | -2.1% | North America and EU | 2025 - 2034 |
| Ethical Concerns Regarding Embryonic Screening | -0.9% | Global | 2025 - 2034 |
| Logistical Constraints in Cell Therapy Supply Chain | -1.4% | Global | 2026 - 2031 |
Hemoglobinopathies Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global hemoglobinopathies landscape, focusing on therapeutic developments, diagnostic innovations, and regional market dynamics. It covers the full spectrum of disorders, including sickle cell disease and various forms of thalassemia, while evaluating the impact of emerging modalities such as gene editing and stem cell transplantation. The report provides quantitative forecasts and qualitative insights into the market's trajectory over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 9.02 Billion |
| Market Forecast in 2034 | USD 28.42 Billion |
| Growth Rate | 13.6% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Vertex Pharmaceuticals, CRISPR Therapeutics, Bluebird Bio, Pfizer (Global Blood Therapeutics), Novartis AG, Sangamo Therapeutics, Editas Medicine, Beam Therapeutics, Bristol Myers Squibb, Agios Pharmaceuticals, Emmaus Life Sciences, Fulcrum Therapeutics, Graphite Bio, Terumo Corporation, Bio-Rad Laboratories, Danaher Corporation, Abbott Laboratories, Roche Diagnostics, PerkinElmer, Siemens Healthineers |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The hemoglobinopathies market is segmented based on disease type, therapy modality, diagnostic method, and end-user. Within the disease type segment, Beta-Thalassemia and Sickle Cell Disease dominate the landscape due to their high clinical severity and the resulting demand for advanced interventions. The therapy segment is witnessing a significant shift; while blood transfusions remain the standard of care for immediate management, gene therapy is rapidly gaining ground as the most lucrative and transformative sub-segment. The diagnosis segment is characterized by a move toward high-throughput sequencing and automated electrophoresis to improve screening efficiency.
- By Disease Type: Focuses on the genetic variations including Thalassemia (Alpha and Beta) and Sickle Cell Disease, which remains the most prevalent hemoglobinopathy globally.
- By Therapy: Includes traditional methods like blood transfusions and chelation therapy, as well as modern approaches like bone marrow transplants and gene-editing techniques.
- By Diagnosis: Covers the critical early-detection methods such as newborn screening, which is essential for reducing pediatric mortality.
- By End-User: Analyzes the distribution of services across hospitals, specialized hematology clinics, and high-volume diagnostic centers.
Regional Highlights
North America currently commands the largest share of the hemoglobinopathies market, underpinned by a sophisticated healthcare infrastructure, high healthcare spending, and the early commercial launch of innovative gene therapies. In contrast, the European market is characterized by strong government support for orphan drug research and comprehensive insurance coverage that facilitates patient access to high-cost treatments. The Middle East and Africa represent a region with immense unmet medical needs and the highest disease prevalence, providing a massive volume-based opportunity for companies that can deliver affordable diagnostic and therapeutic solutions.
- North America: Leading market in terms of value due to high adoption of Casgevy and Lyfgenia therapies.
- Asia Pacific: Fastest growing region (CAGR ~15%) driven by India and Southeast Asia's efforts to control Thalassemia.
- Middle East and Africa: Holds the highest volume of patients, with increasing focus on national screening initiatives in Saudi Arabia and Nigeria.
- Europe: Centralized regulatory pathways and favorable reimbursement for curative treatments drive steady growth.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Hemoglobinopathies Market.- Vertex Pharmaceuticals
- CRISPR Therapeutics
- Bluebird Bio
- Pfizer (Global Blood Therapeutics)
- Novartis AG
- Sangamo Therapeutics
- Editas Medicine
- Beam Therapeutics
- Bristol Myers Squibb
- Agios Pharmaceuticals
- Emmaus Life Sciences
- Fulcrum Therapeutics
- Graphite Bio
- Terumo Corporation
- Bio-Rad Laboratories
- Danaher Corporation
- Abbott Laboratories
- Roche Diagnostics
- PerkinElmer
- Siemens Healthineers
Frequently Asked Questions
What is the current and projected size of the Hemoglobinopathies Market?
The Hemoglobinopathies Market is estimated to be worth USD 10.25 Billion in 2026 and is projected to reach USD 28.42 Billion by 2034, growing at a CAGR of 13.6%.
Which disease segment holds the largest share in the Hemoglobinopathies market?
Sickle Cell Disease (SCD) currently holds the largest market share due to its high prevalence in Africa and the Americas and the recent approval of high-value gene therapies.
What are the primary drivers of growth for this market?
The key drivers include advancements in CRISPR gene-editing technology, the expansion of universal newborn screening programs, and increasing investment in orphan drug development.
Which region is expected to show the fastest growth rate?
The Asia Pacific region is expected to exhibit the fastest CAGR during the forecast period, fueled by a high incidence of thalassemia and improving healthcare access in developing nations.
What are the major challenges facing the market?
The major challenges include the extremely high cost of curative therapies, complex regulatory hurdles for cell and gene products, and the need for specialized medical infrastructure for administration.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted