Hearing Aid Market
Hearing Aid Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_701938 | Published On : September 23, 2026 |
Format : 


 | Author : Erika Grotto
Hearing Aid Market Size
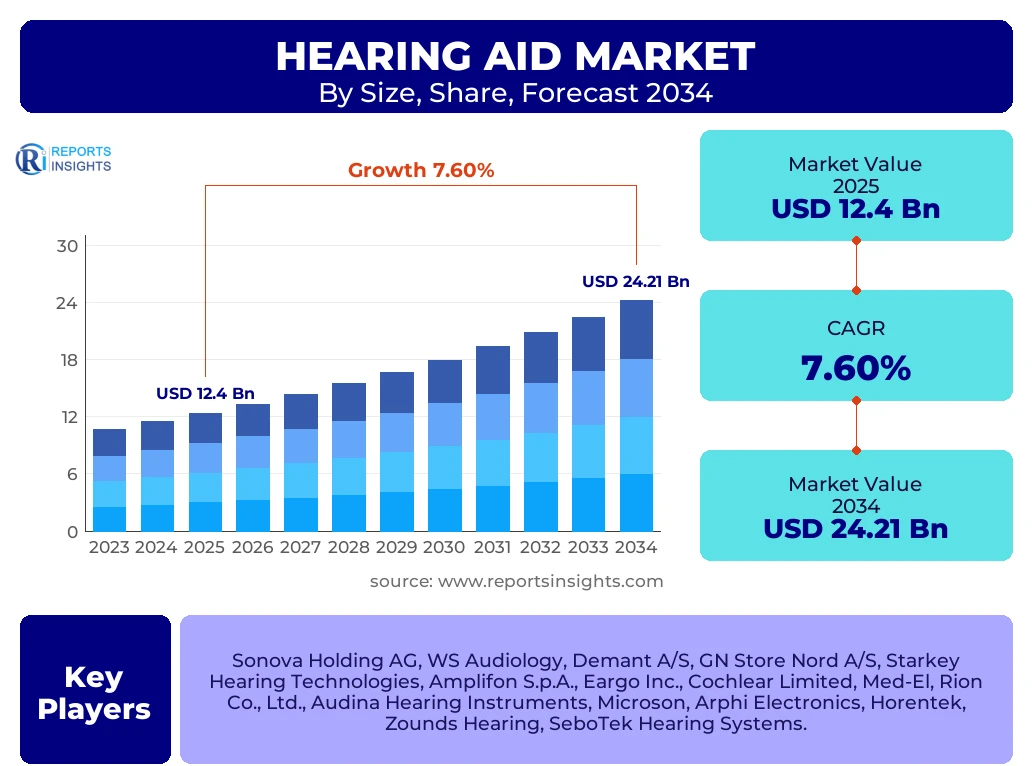
According to Reports Insights Consulting Pvt Ltd, The Hearing Aid Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.6% between 2026 and 2034. The market is estimated at USD 13.34 Billion in 2026 and is projected to reach USD 24.21 Billion by the end of the forecast period in 2034.
Key Hearing Aid Market Trends & Insights
The Hearing Aid market is undergoing a significant transformation driven by the convergence of medical technology and consumer electronics. Users are increasingly seeking devices that offer more than just sound amplification, leading to a surge in demand for multi-functional wearables. The integration of Artificial Intelligence (AI) and Machine Learning (ML) is the most prominent trend, allowing for real-time environment adaptation and noise suppression. Furthermore, the regulatory shift in the United States allowing Over-the-Counter (OTC) Hearing Aid has democratized access, particularly for individuals with mild-to-moderate hearing loss, fundamentally altering the competitive landscape and pricing strategies across the globe.
- Largest Region: North America remains the dominant market owing to high healthcare expenditure and early adoption of advanced audiology solutions.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR due to a rapidly aging population in China and Japan, coupled with improving healthcare infrastructure in India.
- Largest Segment by Product: Behind-the-Ear (BTE) and Receiver-in-the-Ear (RITE) devices hold the largest market share due to their versatility and power.
- Largest Segment by Technology: Digital Hearing Aid dominate the market, nearly phasing out analog versions through superior sound processing capabilities.
- Emerging Trend: The rise of invisible-in-canal (IIC) and completely-in-canal (CIC) devices driven by the demand for discreet, aesthetic solutions.
Key Takeaways Hearing Aid Market Size & Forecast
The global Hearing Aid market is characterized by robust growth patterns supported by demographic shifts and technological breakthroughs. As the global population ages, the prevalence of age-related hearing loss, or presbycusis, is rising, creating a consistent and expanding user base. Market leaders are focusing on miniaturization and connectivity, ensuring that Hearing Aid integrate seamlessly with the modern Internet of Things (IoT) ecosystem, including smartphones, smart televisions, and virtual assistants. This strategic alignment with consumer lifestyle trends is essential for capturing the younger demographic currently affected by noise-induced hearing loss.
- The global market value is set to nearly double by 2034, reflecting the essential nature of these medical devices.
- Technological integration of sensors for health tracking, such as heart rate monitoring and fall detection, is turning Hearing Aid into holistic health wearables.
- The United States and Germany are the primary hubs for research and development, hosting the majority of market-leading manufacturers.
- Expansion of telehealth services in audiology is reducing the barriers to professional fitting and consultation, particularly in rural or underserved areas.
- The transition from disposable to rechargeable lithium-ion batteries is becoming a standard consumer expectation, driving replacement cycles.
Hearing Aid Market Drivers Analysis
The primary catalyst for market expansion is the demographic shift toward an older population. Statistics from the World Health Organization indicate that by 2050, nearly 2.5 billion people will have some degree of hearing loss. This "Silver Tsunami" creates a massive, non-discretionary demand for hearing assistance. Additionally, the technological leap from basic amplification to sophisticated signal processing has reduced the "stigma" associated with Hearing Aid, rebranding them as high-tech audio accessories.
Furthermore, the increase in noise pollution in urban environments and the widespread use of personal audio devices among younger generations are contributing to an earlier onset of hearing impairment. This broadening of the target demographic, combined with favorable government reimbursement policies in developed nations, ensures a steady influx of new users into the market ecosystem.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Global Population (Presbycusis) | +3.2% | Global (Primary: Japan, Italy, Germany) | 2025 - 2034 |
| Technological Integration (AI & Bluetooth 5.0) | +2.1% | North America and Europe | 2025 - 2030 |
| OTC Regulation Implementation | +1.5% | United States | 2025 - 2028 |
| Rising Prevalence of Noise-Induced Hearing Loss | +0.8% | Emerging Economies (APAC, LATAM) | 2027 - 2034 |
Hearing Aid Market Restraints Analysis
Despite the high demand, the primary restraint remains the high cost of premium Hearing Aid, which often includes professional fees for testing, fitting, and follow-up care. In many developing regions, these devices are not covered by public health insurance, making them inaccessible to a large portion of the population. This financial barrier often leads to long delay periods between the diagnosis of hearing loss and the actual purchase of a device.
Additionally, the complexity of managing digital devices can be a deterrent for the very elderly population who may suffer from dexterity issues or cognitive decline. While technology is a driver, the learning curve associated with smartphone apps and wireless pairing can act as a psychological barrier for certain consumer segments, limiting the full penetration of high-end features.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Procurement & Maintenance Cost | -1.4% | Lower-middle income countries | 2025 - 2034 |
| Limited Reimbursement Policies | -0.9% | Latin America and Africa | 2025 - 2030 |
| Social Stigma and Cosmetic Concerns | -0.5% | Global (Focus on Asian markets) | 2025 - 2029 |
Hearing Aid Market Opportunities Analysis
The introduction of Over-the-Counter (OTC) Hearing Aid presents a massive opportunity for manufacturers to target the "mild hearing loss" segment that was previously underserved. This allows companies to tap into retail channels and e-commerce platforms, bypassing the traditional, more expensive clinical model. Companies that can balance clinical efficacy with consumer-friendly branding are likely to capture significant market share in this new category.
Moreover, the integration of biometric sensors into Hearing Aid—known as "Hearables"—opens doors to the broader health-tech market. Features like step counting, heart rate variability monitoring, and even language translation capabilities can transform the hearing aid from a corrective tool into a proactive wellness device. This convergence offers a unique value proposition for tech-savvy consumers and health-conscious seniors alike.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into OTC Retail Channels | +2.4% | North America and Western Europe | 2025 - 2032 |
| Tele-Audiology and Remote Support | +1.8% | Australia, Canada, and Rural US | 2026 - 2034 |
| Development of Biometric 'Hearables' | +1.2% | South Korea, Japan, and USA | 2027 - 2034 |
Hearing Aid Market Challenges Impact Analysis
A significant challenge facing the industry is the shortage of trained audiologists and hearing care professionals in many parts of the world. Even as technology becomes more advanced, the "last mile" of professional fitting and personalized tuning remains critical for user satisfaction. Without a sufficient professional workforce, device abandonment rates can remain high, damaging brand reputation and market growth.
Furthermore, the entry of major consumer electronics giants into the "audio enhancement" space creates intense competitive pressure. Companies traditionally focused on headphones and earbuds are now introducing features that mimic hearing aid functionality (transparency modes and conversation boost). This blurs the line between medical devices and consumer electronics, challenging the traditional pricing models and market share of established medical-grade manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Audiologists | -1.1% | Emerging Markets and Rural Regions | 2025 - 2034 |
| Competition from Consumer Tech Giants | -1.3% | Global | 2026 - 2031 |
| Supply Chain Volatility (Semiconductors) | -0.6% | Global Manufacturers | 2025 - 2027 |
Hearing Aid Market - Updated Report Scope
The updated report provides a 360-degree view of the Hearing Aid industry, encompassing technological shifts, regulatory changes, and competitive dynamics across six major geographical regions. It analyzes the impact of digital transformation on audiological care and provides a detailed roadmap for stakeholders navigating the transition from traditional to smart hearing solutions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 12.4 Billion |
| Market Forecast in 2034 | USD 24.21 Billion |
| Growth Rate | 7.6% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Sonova Holding AG, WS Audiology, Demant A/S, GN Store Nord A/S, Starkey Hearing Technologies, Amplifon S.p.A., Eargo Inc., Cochlear Limited, Med-El, Rion Co., Ltd., Audina Hearing Instruments, Microson, Arphi Electronics, Horentek, Zounds Hearing, SeboTek Hearing Systems. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented to reflect the diverse needs of the patient population and the various technological tiers available. The Product Type segment remains the most vital for understanding consumer preferences, where a clear shift toward RITE (Receiver-in-the-Ear) is observed due to its balanced profile of comfort and performance. The Distribution Channel segment is currently experiencing a disruption as online and retail channels grow at the expense of traditional clinical settings, driven by the OTC movement.
- By Product Type: Behind-the-Ear (BTE), Receiver-in-the-Ear (RITE), In-the-Ear (ITE), In-the-Canal (ITC), Completely-in-the-Canal (CIC), and Invisible-in-the-Canal (IIC).
- By Technology: Digital Hearing Aid (Basic, Mid, and Premium Tiers) and Analog Hearing Aid.
- By Patient Type: Adult and Pediatric.
- By Distribution Channel: Audiology Clinics, ENT Clinics, Hospitals, E-commerce Platforms, and Retail Pharmacies/Over-the-Counter.
- By Power Source: Rechargeable (Lithium-ion) and Disposable Batteries (Zinc-Air).
Regional Highlights
- North America: Currently the largest market share holder. The region is characterized by early adoption of AI-enabled devices and a high volume of veteran-related hearing care through the VA system. The US OTC market is a major growth engine.
- Europe: This region holds a significant share due to strong public healthcare systems and reimbursement schemes in countries like Germany, France, and the UK. It is home to several of the world’s largest hearing aid manufacturers.
- Asia-Pacific: The fastest-growing region. Rapidly aging demographics in China and Japan, combined with a rising middle class in India and Southeast Asia, are driving massive volume growth. Expanding awareness programs are reducing the stigma in these markets.
- Latin America: Growing at a steady pace with Brazil and Mexico as key contributors. Market growth is tied to improving economic conditions and the expansion of private healthcare clinics.
- Middle East & Africa: A niche but growing market. Demand is primarily concentrated in the GCC countries, where healthcare infrastructure is modernizing rapidly.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Hearing Aid Market.- Sonova Holding AG (Phonak, Unitron)
- WS Audiology (Signia, Widex, Rexton)
- Demant A/S (Oticon, Bernafon, Sonic)
- GN Store Nord A/S (ReSound, Beltone, Jabra)
- Starkey Hearing Technologies
- Amplifon S.p.A.
- Eargo, Inc.
- Cochlear Limited
- Med-El (Medical Electronics)
- Rion Co., Ltd.
- Audina Hearing Instruments, Inc.
- Microson
- Arphi Electronics Pvt. Ltd.
- Horentek
- Zounds Hearing
- SeboTek Hearing Systems, LLC
- IntriCon Corporation
- Elkon Pvt. Ltd.
Frequently Asked Questions
What is the main driver for the Hearing Aid Market growth through 2034?
The primary driver is the global aging population, with a significant increase in individuals over the age of 65 who are prone to age-related hearing loss (presbycusis), combined with the rising demand for technologically advanced, connected devices.
How has the introduction of OTC Hearing Aid affected the market?
OTC Hearing Aid have lowered the barrier to entry for consumers with mild-to-moderate hearing loss, leading to increased price competition and the expansion of distribution into retail and e-commerce channels, formerly dominated by clinics.
Which technology segment is dominating the market?
Digital technology is the dominant segment, accounting for over 90% of the market. Digital aids offer advanced features like noise cancellation, multi-directional microphones, and Bluetooth connectivity that analog devices cannot provide.
What are the key regional markets for Hearing Aid?
North America currently holds the largest market share due to high awareness and healthcare spending, while the Asia-Pacific region is the fastest-growing market due to its large aging population and improving healthcare access.
What are the primary challenges facing hearing aid manufacturers?
Key challenges include high product costs in emerging markets, a global shortage of audiology professionals for device fitting, and increasing competition from consumer electronics companies offering 'hearable' features.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
