Healthcare Medical Tourism Market
Healthcare Medical Tourism Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711512 | Published On : November 04, 2026 |
Format : 


 | Author : Erika Grotto
Healthcare Medical Tourism Market Size
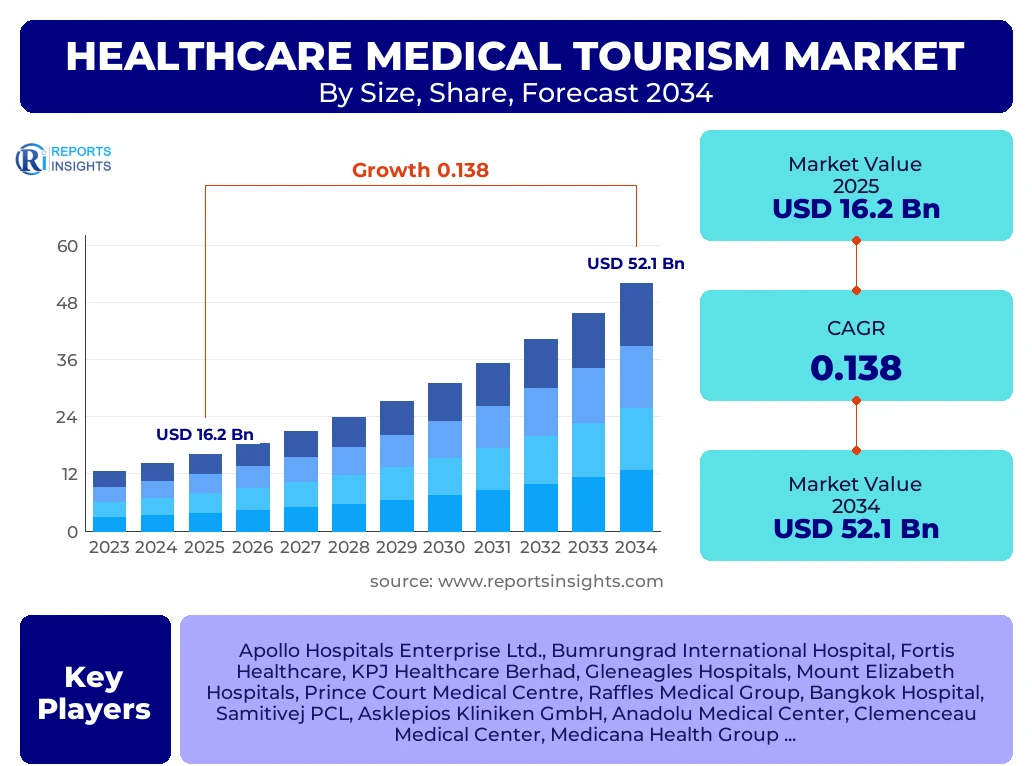
According to Reports Insights Consulting Pvt Ltd, The Healthcare Medical Tourism Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.8% between 2025 and 2034. The market is estimated at USD 18.4 Billion in 2026 and is projected to reach USD 52.1 Billion by the end of the forecast period in 2034.
Key Healthcare Medical Tourism Market Trends & Insights
The healthcare medical tourism industry is currently undergoing a structural transformation driven by the integration of digital health platforms and a significant shift toward value-based cross-border care. Stakeholders are increasingly focusing on accreditation as a primary differentiator, with Joint Commission International (JCI) standards becoming the benchmark for international patient safety. Analysis suggests that while traditional hubs in Southeast Asia remain dominant, there is an emerging trend of specialized medical clusters in the Middle East and Eastern Europe catering to high-complexity procedures such as oncology and robotic surgery. Competitive benchmarking reveals that cost remains a primary driver, but patient experience and post-operative care coordination are becoming critical factors in market retention and regional growth.
- Largest Region: Asia Pacific remains the dominant market share holder, driven by established infrastructures in Thailand, India, and Malaysia.
- Fastest Growing Region: The Middle East and Africa (MEA) region, particularly Turkey and the UAE, is witnessing the most rapid expansion due to aggressive government investments.
- Largest Segment by Share: Cosmetic and Dental procedures continue to hold the largest share of the market due to their elective nature and high out-of-pocket costs in developed nations.
- Emerging Trend: The rise of Medical Value Travel (MVT) which integrates wellness and recuperation into the traditional clinical tourism model.
Key Takeaways Healthcare Medical Tourism Market Size & Forecast
The global outlook for medical tourism remains highly positive as the disparity in healthcare costs between developed and developing nations continues to widen. Forecast data indicates that the market is moving toward a more regulated environment, where bilateral agreements between governments and insurance providers are facilitating seamless patient transfers. The democratization of information through digital health portals has empowered patients to conduct rigorous comparative analyses of surgical outcomes across borders, leading to higher quality standards globally. Key insights suggest that the integration of telehealth for pre-surgical consultations and post-operative follow-ups is significantly reducing the perceived risk of traveling abroad for medical care.
- Thailand is the leading destination for elective cosmetic surgeries globally, maintaining a significant competitive edge in service quality.
- India serves as the primary hub for high-complexity cardiovascular and orthopedic procedures at a fraction of the cost found in North America.
- Turkey has emerged as a global leader in hair transplant procedures and specialized ophthalmic treatments.
- The North American outbound market is the primary source of revenue for many Latin American hubs, especially Mexico and Costa Rica.
- Technological advancements in minimally invasive surgeries are reducing recovery times, making international travel more feasible for patients.
Healthcare Medical Tourism Market Drivers Analysis
The primary driver for the healthcare medical tourism market is the substantial cost arbitrage available between western economies and emerging medical hubs. Patients in regions like the United States and the United Kingdom often face exorbitant costs for elective procedures or long waiting lists for essential surgeries under socialized medicine systems. This creates a push factor, where high-quality care in JCI-accredited facilities abroad becomes an attractive alternative. Furthermore, the rising penetration of medical insurance that covers cross-border treatments is incentivizing patients to seek care in overseas destinations that offer premium amenities alongside clinical excellence.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Significant Cost Savings (up to 80% vs US/UK) | +4.5% | Global / USA outbound | 2025 - 2034 |
| Long Waiting Times in Socialized Healthcare Systems | +3.2% | Canada, United Kingdom | 2025 - 2030 |
| Rise of Accredited Global Healthcare Facilities | +2.8% | Thailand, India, Turkey | 2026 - 2034 |
| Integration of Telehealth for Follow-up Care | +2.1% | Singapore, UAE | 2027 - 2034 |
Healthcare Medical Tourism Market Restraints Analysis
Despite the growth, the market faces significant hurdles related to legal and ethical complexities. The lack of a unified global legal framework for medical malpractice means that patients often have limited recourse if a procedure fails or complications arise in a foreign jurisdiction. Additionally, the risk of infectious diseases and the variability in medical standards across non-accredited facilities can deter potential medical tourists. Continuity of care remains a critical restraint, as the transition of medical records and follow-up communication between international surgeons and local primary care physicians is often fragmented.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Legal Challenges and Malpractice Liabilities | -1.8% | International Jurisdictions | 2025 - 2034 |
| Concerns over Follow-up Care and Continuity | -1.4% | Europe and North America | 2025 - 2030 |
| Fluctuating Political and Economic Stability | -1.1% | Latin America, MEA | 2026 - 2034 |
Healthcare Medical Tourism Market Opportunities Analysis
The expansion of specialized medical cities and the formalization of medical tourism corridors present significant growth opportunities. Governments are increasingly offering specialized visas for medical tourists, streamlining the entry process and providing a more welcoming environment. There is also a burgeoning opportunity in the "Medical Wellness" niche, where clinical treatments are combined with holistic therapies and luxury recovery stays. The adoption of Blockchain for secure, cross-border health data exchange and AI-driven patient matching services can further enhance the transparency and reliability of the global medical tourism ecosystem.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Specialized Medical Economic Zones | +3.5% | UAE, Saudi Arabia | 2026 - 2034 |
| Corporate Insurance Partnership Models | +2.9% | USA, Germany | 2027 - 2034 |
| Expansion into Precision Medicine and Genomics | +2.4% | Singapore, South Korea | 2028 - 2034 |
Healthcare Medical Tourism Market Challenges Impact Analysis
One of the most pressing challenges is the ethical concern regarding "medical brain drain" in host countries, where resources may be diverted from local populations to cater to wealthy international patients. Furthermore, global health crises or pandemics can abruptly halt international travel, highlighting the vulnerability of the market to external shocks. Maintaining consistent quality standards across a vast network of providers while keeping prices competitive remains a constant operational challenge for medical tourism facilitators and hospital groups alike.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Ethical Concerns Regarding Local Resource Allocation | -0.9% | Developing Nations | 2025 - 2034 |
| Global Travel Vulnerability and Geopolitics | -1.5% | Global | Ongoing |
| Strict Regulatory Changes for Organ Transplants | -0.7% | China, India | 2025 - 2030 |
Healthcare Medical Tourism Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global healthcare medical tourism landscape, covering clinical, economic, and regulatory dimensions. It evaluates the impact of technological integration on patient flows and provides a granular assessment of high-value medical segments. The report also scrutinizes the strategic positioning of key market players and the emerging influence of government-led initiatives in shaping regional competitive advantages.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 16.2 Billion |
| Market Forecast in 2034 | USD 52.1 Billion |
| Growth Rate | 13.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Apollo Hospitals Enterprise Ltd., Bumrungrad International Hospital, Fortis Healthcare, KPJ Healthcare Berhad, Gleneagles Hospitals, Mount Elizabeth Hospitals, Prince Court Medical Centre, Raffles Medical Group, Bangkok Hospital, Samitivej PCL, Asklepios Kliniken GmbH, Anadolu Medical Center, Clemenceau Medical Center, Medicana Health Group, Memorial Healthcare Group, Seoul National University Hospital, IHH Healthcare Berhad, Sunway Medical Centre. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The healthcare medical tourism market is segmented primarily by treatment type and service provider, reflecting the diverse medical needs of global travelers. The cosmetic and dental segments dominate in terms of volume due to lower regulatory hurdles and high private expenditure. However, the cardiovascular and orthopedic segments are growing in value as patients seek advanced surgical interventions that are either too expensive or unavailable in their home countries. The segmentation further considers the type of provider, where private hospital chains are capturing the majority of the market due to their focus on international accreditation and patient-centric services.
- By Treatment Type:
- Cosmetic Surgery (Breast Augmentation, Rhinoplasty, Liposuction)
- Dental Treatment (Implants, Veneers, Orthodontics)
- Cardiovascular Surgery (Bypass, Valve Replacement)
- Orthopedic Surgery (Hip/Knee Replacement, Spinal Surgery)
- Fertility Treatment (IVF, Surrogacy)
- Oncology (Cancer Treatment and Radiotherapy)
- Bariatric Surgery (Weight Loss Procedures)
- Ophthalmology (LASIK, Cataract Surgery)
- By Service Provider:
- Private Multispecialty Hospitals
- Public/Government Hospitals with International Wings
- Specialized Surgical Centers
- By Booking Channel:
- Direct Booking
- Medical Tourism Facilitators/Agencies
- Corporate/Insurance Referrals
Regional Highlights
The Asia Pacific region remains the global powerhouse for medical tourism, with Thailand leading in elective procedures and India excelling in complex clinical surgeries. The region’s dominance is supported by a robust ecosystem of JCI-accredited facilities and a high concentration of internationally trained physicians. In contrast, the Middle East is the fastest-growing region, with cities like Dubai and Abu Dhabi positioning themselves as luxury medical hubs, attracting patients from Europe and Africa through high-end infrastructure and specialized treatments.
- Thailand: The world’s leading destination for cosmetic and wellness tourism, boasting the highest number of JCI-accredited hospitals in Southeast Asia.
- India: A critical hub for cardiovascular, orthopedic, and transplant surgeries, offering high-tech care at the world’s most competitive prices.
- Mexico: The primary destination for North American dental and bariatric patients due to geographic proximity and significant cost savings.
- Turkey: Rapidly becoming the global center for hair transplants and ophthalmology, supported by government subsidies and strategic airline partnerships.
- Singapore: Positioned as a premium destination for high-complexity oncology and neurology cases, catering to the upper-affluent segment of the market.
- Costa Rica: A growing hub for eco-wellness combined with high-quality dental and cosmetic services.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Healthcare Medical Tourism Market.- Apollo Hospitals Enterprise Ltd.
- Bumrungrad International Hospital
- Fortis Healthcare
- KPJ Healthcare Berhad
- Gleneagles Hospitals (IHH Healthcare)
- Mount Elizabeth Hospitals
- Prince Court Medical Centre
- Raffles Medical Group
- Bangkok Hospital
- Samitivej PCL
- Asklepios Kliniken GmbH
- Anadolu Medical Center
- Clemenceau Medical Center
- Medicana Health Group
- Memorial Healthcare Group
- Seoul National University Hospital
- Sunway Medical Centre
- Max Healthcare Institute Ltd.
- Texila American University (Medical Services Division)
Frequently Asked Questions
Analyze common user questions about the Healthcare Medical Tourism market and generate a concise list of summarized FAQs reflecting key topics and concerns.
What are the most popular destinations for medical tourism in 2025?
The top destinations include Thailand for cosmetic surgery, India for cardiac and orthopedic procedures, Mexico for dental work, and Turkey for hair transplants. These countries offer a combination of high accreditation standards and significant cost advantages.
How much can patients save by choosing medical tourism?
Patients can typically save between 30% and 80% on medical costs compared to the United States or Western Europe. These savings include the cost of the procedure, travel, and accommodation, though they vary significantly by treatment type and destination.
Is medical tourism safe and how is quality ensured?
Safety is ensured by choosing facilities with international accreditations such as Joint Commission International (JCI). Many hospitals in medical tourism hubs employ physicians trained in the US or Europe and use the latest medical technologies to maintain global safety standards.
What role does insurance play in the medical tourism market?
Insurance providers are increasingly offering "Global Health" plans or specific riders that cover international medical travel. Some employers in the US also incentivize medical tourism to reduce corporate healthcare expenditures while maintaining high-quality outcomes for employees.
What are the primary risks associated with medical tourism?
The primary risks include complications during travel, limited legal recourse in foreign jurisdictions, and potential gaps in post-operative care once the patient returns home. Effective communication between international and local healthcare providers is essential to mitigate these risks.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
