Health Sensors Market
Health Sensors Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710898 | Published On : September 15, 2026 |
Format : 


 | Author : Shamin Verma
Health Sensors Market Size
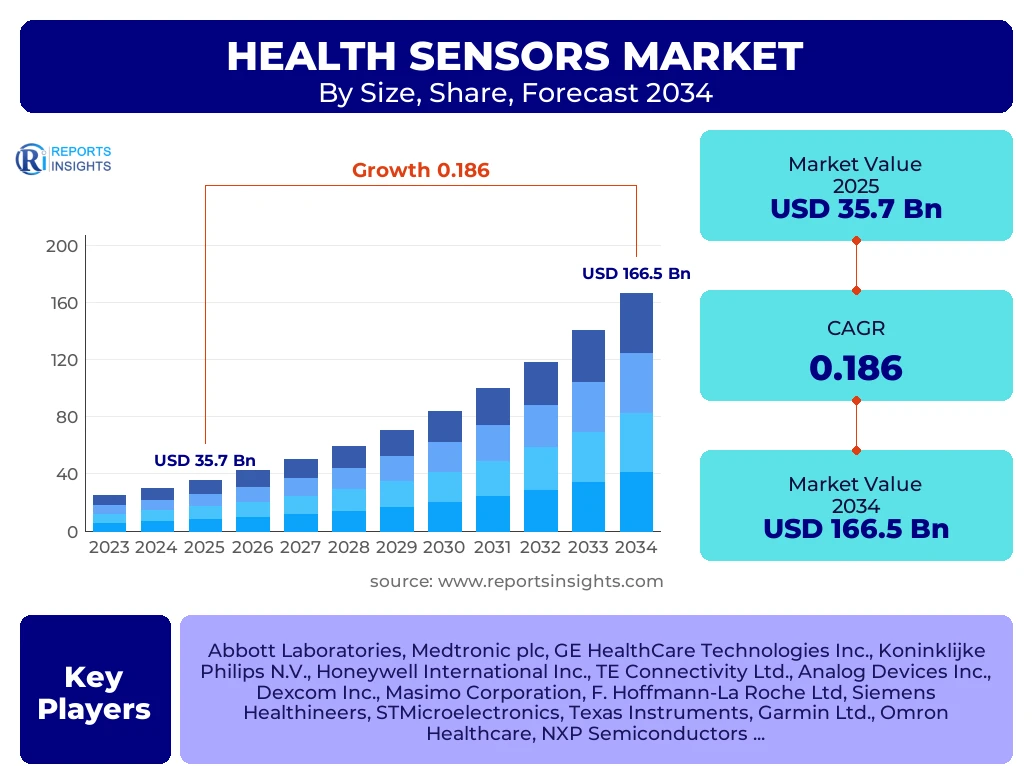
According to Reports Insights Consulting Pvt Ltd, The Health Sensors Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 18.6% between 2026 and 2034. The market is estimated at USD 42.3 Billion in 2026 and is projected to reach USD 166.5 Billion by the end of the forecast period in 2034.
Key Health Sensors Market Trends & Insights
The global health sensors landscape is undergoing a significant transformation driven by the convergence of micro-electromechanical systems (MEMS), artificial intelligence (AI), and the Internet of Medical Things (IoMT). As healthcare shifts from reactive to proactive and personalized models, health sensors have become the primary data acquisition layer for real-time diagnostics. Current trends indicate a move toward non-invasive continuous glucose monitoring, advanced cardiovascular tracking through photoplethysmography (PPG), and the integration of flexible, skin-like electronic sensors that offer unprecedented comfort and data fidelity. Furthermore, the decentralization of clinical trials and the rise of decentralized healthcare delivery models are propelling the adoption of clinical-grade sensors in residential settings.
- Largest Region: North America currently holds the largest market share, attributed to its advanced healthcare infrastructure and high adoption rate of wearable medical technologies.
- Fastest Growing Region: Asia-Pacific is expected to exhibit the highest CAGR during the forecast period due to rising healthcare expenditure and increasing prevalence of chronic diseases in populous nations like China and India.
- Largest Segment: Wearable health sensors represent the largest segment by share, fueled by the consumerization of health data and the popularity of smartwatches and fitness trackers.
- Emerging Tech: AI-integrated sensors that provide predictive health analytics rather than just raw data are seeing rapid institutional investment.
Key Takeaways Health Sensors Market Size & Forecast
The market trajectory for health sensors is predominantly defined by the increasing burden of chronic conditions such as diabetes, hypertension, and cardiovascular diseases, necessitating long-term monitoring solutions. Stakeholders are focusing on enhancing the precision of biometric sensors to meet clinical standards, thereby bridging the gap between consumer fitness gadgets and medical-grade diagnostic equipment. The forecast period is expected to see a surge in the integration of 5G connectivity, which facilitates the low-latency transmission of high-resolution physiological data to remote cloud platforms for physician review.
- Dominant Country: The United States remains the leading country contributor, driven by significant R&D investments and a robust regulatory framework favoring digital health innovation.
- Market Driver: The global shift toward value-based care is incentivizing providers to use health sensors for reducing hospital readmission rates through remote patient monitoring.
- Product Innovation: Nanotechnology-based sensors are entering the pilot phase, promising breakthroughs in molecular-level diagnostics and internal physiological monitoring.
- Investment Focus: Venture capital is increasingly flowing toward startups specializing in biosensors for early cancer detection and mental health monitoring via physiological markers.
Health Sensors Market Drivers Analysis
The primary catalysts for the health sensors market include the global demographic shift toward an aging population and the escalating demand for home-based healthcare solutions. As the volume of geriatric patients increases, there is a commensurate need for sensors that can detect falls, monitor heart arrhythmias, and track medication adherence without requiring frequent hospital visits. Furthermore, the post-pandemic emphasis on telehealth has solidified the role of health sensors as indispensable tools for remote diagnosis and consultation.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Remote Patient Monitoring (RPM) | +5.4% | Global (Strongest in North America and Europe) | 2025 - 2034 |
| Advancements in MEMS and Nanotechnology | +4.2% | Japan, South Korea, and Germany | 2026 - 2030 |
| Rising Prevalence of Lifestyle Diseases | +4.8% | India, China, and Middle East | 2025 - 2034 |
Health Sensors Market Restraints Analysis
Market growth is tempered by significant concerns regarding data security and the privacy of sensitive patient information. As sensors collect vast amounts of granular health data, they become prime targets for cyberattacks, leading to stringent regulatory scrutiny. Additionally, the lack of standardized interoperability protocols across different sensor manufacturers and healthcare IT systems often creates data silos, hindering the seamless integration of sensor data into Electronic Health Records (EHR).
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Privacy and Cybersecurity Risks | -2.1% | European Union (GDPR compliance) and USA | 2025 - 2034 |
| High Initial Cost of Specialized Sensors | -1.5% | Developing Economies (Africa, SE Asia) | 2025 - 2028 |
Health Sensors Market Opportunities Analysis
The integration of health sensors with 5G technology and Edge Computing presents a transformative opportunity for real-time, low-latency health monitoring and emergency response. Moreover, there is an untapped potential in the development of multi-modal biosensors capable of simultaneously tracking multiple biomarkers such as glucose, lactate, and electrolytes from sweat or interstitial fluid. The expansion of medical-grade sensors into the corporate wellness sector also offers a significant new revenue stream for market participants.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-driven Predictive Analytics Integration | +6.2% | Global (High Tech Hubs) | 2026 - 2034 |
| Expansion into Mental Health Monitoring | +3.5% | North America and Western Europe | 2027 - 2034 |
Health Sensors Market Challenges Impact Analysis
The primary challenge remains the complex and time-consuming regulatory approval process for clinical-grade sensors, which can delay market entry for innovative products. Furthermore, maintaining sensor accuracy and calibration over long periods of continuous use is a significant technical hurdle. Market fragmentation, with numerous small players offering niche solutions, also makes it difficult for healthcare providers to choose consolidated platforms for large-scale deployment.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Regulatory Approval Cycles (FDA/CE) | -2.4% | United States and Europe | 2025 - 2030 |
| Sensor Sensitivity and Calibration Issues | -1.8% | Global Manufacturers | 2025 - 2034 |
Health Sensors Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global health sensors market, covering various sensor types including physical, chemical, and biological interfaces. It evaluates the technological landscape from basic motion sensing in consumer wearables to sophisticated implantable biosensors used in specialized clinical settings. The report provides a granular breakdown of market dynamics across key geographic regions and identifies the strategic maneuvers of leading industry players to secure market dominance through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 35.7 Billion |
| Market Forecast in 2034 | USD 166.5 Billion |
| Growth Rate | 18.6% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Abbott Laboratories, Medtronic plc, GE HealthCare Technologies Inc., Koninklijke Philips N.V., Honeywell International Inc., TE Connectivity Ltd., Analog Devices Inc., Dexcom Inc., Masimo Corporation, F. Hoffmann-La Roche Ltd, Siemens Healthineers, STMicroelectronics, Texas Instruments, Garmin Ltd., Omron Healthcare, NXP Semiconductors, Smith & Nephew, Terumo Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the health sensors market reflects the diverse clinical and consumer needs for physiological data tracking. The Wearable Health Sensors segment continues to dominate due to the proliferation of smartwatches and medical-grade patches. However, the Implantable Sensors segment is witnessing rapid growth in specialized applications such as cardiac rhythm management and glucose monitoring for Type 1 diabetes. By application, Chronic Disease Management remains the most significant revenue contributor, as health systems prioritize long-term outpatient monitoring to control costs and improve patient outcomes.
- By Sensor Type:
- Blood Pressure Sensors
- Heart Rate & ECG Sensors
- Pulse Oximetry (SpO2) Sensors
- Continuous Glucose Monitoring (CGM) Sensors
- Temperature & Respiratory Sensors
- Motion & Position Sensors (Accelerometer/Gyroscopes)
- By Product Form Factor:
- Wearables (Wristwear, Chest Straps, Footwear)
- Implantable Biosensors
- Ingestible Smart Pills
- Epidermal Electronics (Electronic Skin)
- By Application:
- Chronic Disease Monitoring (Diabetes, CVD, COPD)
- Remote Patient Monitoring (RPM)
- Post-Operative Recovery
- Maternal and Neonatal Care
- Fitness and Sports Performance
- By End User:
- Hospitals, Clinics, and ASCs
- Home Care Settings
- Rehabilitation Centers
- Diagnostic Laboratories
Regional Highlights
- North America: Currently the largest market globally, North America’s dominance is underpinned by high healthcare spending, a supportive reimbursement landscape for remote patient monitoring, and the presence of industry titans in both the technology and medical device sectors. The United States leads the region with intensive R&D in biosensor miniaturization.
- Europe: The second-largest market, with a focus on stringent data protection (GDPR) and public health initiatives that integrate digital health tools. Countries like Germany, the UK, and France are pioneering the use of sensors in state-funded telehealth programs.
- Asia-Pacific: Recognized as the fastest-growing region. This growth is driven by the rapid modernization of healthcare infrastructure in China and India, a large patient pool with chronic conditions, and the presence of major electronics manufacturing hubs that reduce sensor production costs.
- Latin America & MEA: These regions are showing steady growth, particularly in urban centers where mobile health (mHealth) adoption is increasing as a means to overcome geographic barriers to specialized medical care.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Health Sensors Market.
- Abbott Laboratories
- Medtronic plc
- GE HealthCare Technologies Inc.
- Koninklijke Philips N.V.
- Honeywell International Inc.
- TE Connectivity Ltd.
- Analog Devices Inc.
- Dexcom Inc.
- Masimo Corporation
- F. Hoffmann-La Roche Ltd
- Siemens Healthineers
- STMicroelectronics
- Texas Instruments
- Garmin Ltd.
- Omron Healthcare
- NXP Semiconductors
- Smith & Nephew
- Terumo Corporation
- Valencell Inc.
- SENSIRION AG
Frequently Asked Questions
What is the current size of the global Health Sensors market?
The global health sensors market is estimated to be valued at approximately USD 35.7 Billion in 2025 and is expected to reach USD 42.3 Billion by 2026, showing strong upward momentum.
Which sensor type is experiencing the fastest growth?
Continuous Glucose Monitoring (CGM) sensors and ECG sensors are currently among the fastest-growing types due to the rising global incidence of diabetes and cardiovascular diseases.
What are the primary factors driving the adoption of health sensors?
Key drivers include the rise of remote patient monitoring, an aging global population, the integration of AI in healthcare diagnostics, and a growing consumer focus on proactive wellness.
How is AI influencing the health sensors market?
AI is shifting the market from "data collection" to "insight generation" by allowing sensors to provide predictive alerts for potential health crises like heart attacks or hypoglycemic shocks before they occur.
Which region offers the most significant investment opportunities?
While North America offers stability and high value, the Asia-Pacific region offers the most significant long-term growth opportunities due to its massive population base and accelerating digital health adoption.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted