Hand Held Surgical Instruments Market
Hand Held Surgical Instruments Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711064 | Published On : October 03, 2026 |
Format : 


 | Author : Erika Grotto
Hand Held Surgical Instruments Market Size
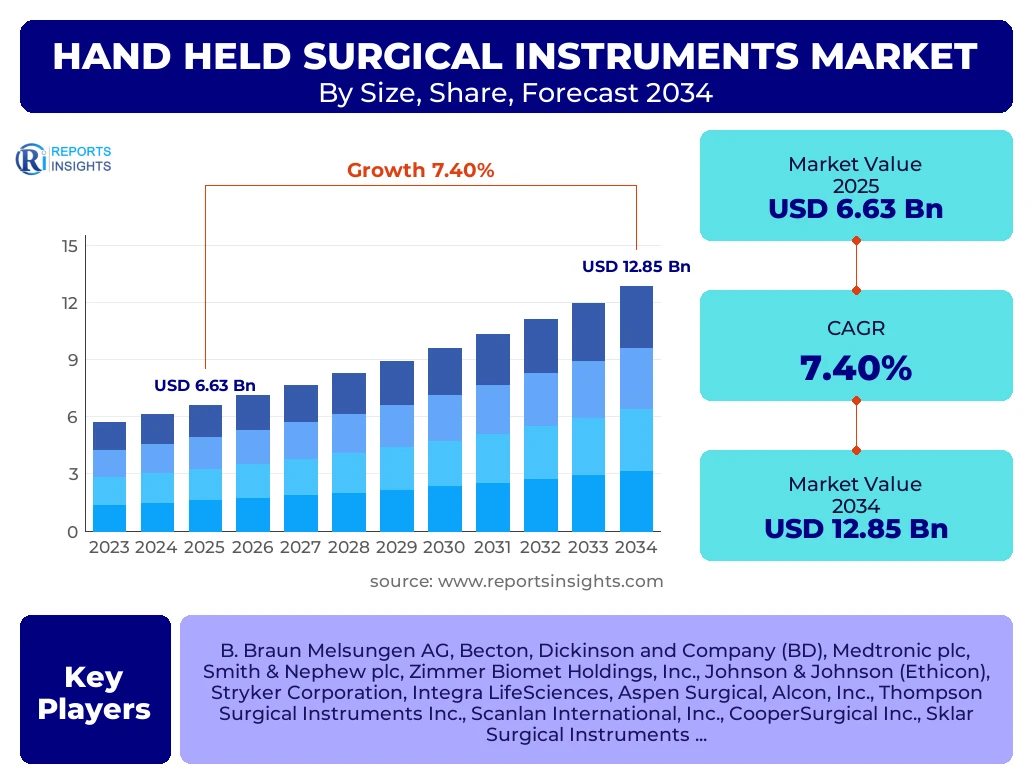
According to Reports Insights Consulting Pvt Ltd, The Hand Held Surgical Instruments Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2026 and 2034. The market is estimated at USD 7.12 Billion in 2026 and is projected to reach USD 12.85 Billion by the end of the forecast period in 2034.
Key Hand Held Surgical Instruments Market Trends & Insights
The global hand held surgical instruments market is undergoing a significant transformation driven by the escalating volume of surgical procedures worldwide and a parallel shift toward minimally invasive surgeries. Modern healthcare systems are increasingly prioritizing instruments that offer higher precision, ergonomic comfort for surgeons, and enhanced durability. The integration of advanced materials, such as high-grade titanium and specialized stainless steel alloys, is a prominent trend aimed at reducing instrument weight while maintaining structural integrity. Furthermore, the market is witnessing a bifurcation between high-quality reusable instruments and the rising adoption of cost-effective, sterile, single-use hand held tools, which address growing concerns regarding hospital-acquired infections (HAIs).
- North America remains the largest regional market due to its advanced healthcare infrastructure and high surgical volume.
- The Asia-Pacific region is identified as the fastest-growing market, fueled by expanding healthcare access and medical tourism.
- The forceps and spatulas segment currently holds the largest market share owing to their ubiquitous use across all surgical disciplines.
- Technological advancements in ergonomic design are reducing surgeon fatigue during prolonged procedures, particularly in neurosurgery and cardiovascular surgery.
Key Takeaways Hand Held Surgical Instruments Market Size & Forecast
The Hand Held Surgical Instruments market is characterized by steady, resilient growth, underpinned by the demographic shift toward an aging population and the subsequent rise in chronic conditions requiring surgical intervention. Stakeholders are focusing on strategic acquisitions and product diversification to maintain competitive advantages. The forecast period indicates a robust CAGR, with substantial capital being channeled into research and development for specialized instruments in oncology, orthopedics, and plastic surgery. The market's expansion is further supported by the increasing number of Ambulatory Surgical Centers (ASCs) which demand high-performance, cost-efficient surgical instrument kits.
- The United States is the leading country contributor to global revenue, supported by high healthcare spending and early adoption of new surgical technologies.
- Orthopedic surgery is a primary application driver, spurred by the rising incidence of sports injuries and degenerative joint diseases.
- There is a critical emphasis on the sterilization and reprocessing segment, influencing the design and material choice of hand held instruments.
- Emerging economies in Latin America and the Middle East are providing lucrative opportunities for market players as they upgrade their public health facilities.
Hand Held Surgical Instruments Market Drivers Analysis
The primary driver for the hand held surgical instruments market is the global surge in surgical volumes, necessitated by an aging population and a higher prevalence of lifestyle-related diseases. As diagnostic capabilities improve, more patients are being referred for surgical treatments, increasing the demand for fundamental instruments like scalpels, forceps, and retractors. Additionally, the proliferation of minimally invasive surgery (MIS) requires specialized hand held tools that can operate through smaller incisions, driving innovation in instrument miniaturization and precision.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Geriatric Population & Chronic Disease Prevalence | +2.1% | Global (High impact in Japan, Germany, USA) | 2025 - 2034 |
| Advancements in Minimally Invasive Surgery (MIS) | +1.8% | North America & Europe | 2025 - 2030 |
| Expansion of Ambulatory Surgical Centers (ASCs) | +1.5% | United States & United Kingdom | 2026 - 2034 |
| Increased Healthcare Expenditure in Emerging Markets | +1.2% | China, India, Brazil | 2027 - 2034 |
Hand Held Surgical Instruments Market Restraints Analysis
Market growth is tempered by stringent regulatory frameworks and the high cost of premium surgical instruments. Regulatory bodies such as the FDA and EMA have intensified their requirements for instrument sterilization and material safety, which increases manufacturing costs and time-to-market. Furthermore, the increasing pressure on healthcare providers to reduce operational costs has led to intensive price negotiations and a preference for low-cost alternatives in certain regions, potentially squeezing profit margins for premium manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Regulatory Approval Processes | -0.8% | European Union & North America | Ongoing |
| Price Erosion and Intense Market Competition | -0.6% | Global | 2025 - 2034 |
| Concerns Over Inadequate Sterilization & HAIs | -0.4% | Developing Regions | 2025 - 2028 |
Hand Held Surgical Instruments Market Opportunities Analysis
There are significant opportunities in the development of "smart" hand held instruments that incorporate sensors or digital feedback mechanisms to assist surgeons during delicate procedures. The shift toward single-use instruments in outpatient settings offers a massive growth avenue for manufacturers who can produce high-quality, disposable tools at scale. Additionally, the untapped potential of rural healthcare markets in Africa and Southeast Asia provides a secondary growth engine as these regions focus on basic surgical infrastructure development.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growth in Medical Tourism | +1.4% | Thailand, Turkey, Mexico | 2026 - 2034 |
| Innovation in Single-Use Surgical Kits | +1.2% | Global | 2025 - 2032 |
| Adoption of Specialty-Specific Instruments | +1.1% | Japan & Western Europe | 2027 - 2034 |
Hand Held Surgical Instruments Market Challenges Impact Analysis
The primary challenge involves maintaining a balance between innovation and cost-effectiveness. As the complexity of surgeries increases, instruments must be more specialized, but healthcare budgets are tightening. Supply chain disruptions and the fluctuating price of raw materials like high-grade steel and titanium also pose significant operational challenges for manufacturers. Moreover, the integration of robotic surgical systems is a long-term challenge that may reduce the reliance on traditional hand held instruments in certain high-end surgical procedures.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -0.5% | Global | 2025 - 2027 |
| Technological Displacement by Robotics | -0.7% | Advanced Economies | 2028 - 2034 |
| Supply Chain Fragmentations | -0.3% | Global | 2025 - 2026 |
Hand Held Surgical Instruments Market - Updated Report Scope
This report provides a comprehensive analysis of the global hand held surgical instruments market, covering various product categories, surgical applications, and end-user segments. It includes detailed revenue forecasts, competitive benchmarking, and an analysis of the socio-economic factors influencing market dynamics across major geographical regions. The scope encompasses reusable and disposable instruments used in inpatient and outpatient settings.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 6.63 Billion |
| Market Forecast in 2034 | USD 12.85 Billion |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | B. Braun Melsungen AG, Becton, Dickinson and Company (BD), Medtronic plc, Smith & Nephew plc, Zimmer Biomet Holdings, Inc., Johnson & Johnson (Ethicon), Stryker Corporation, Integra LifeSciences, Aspen Surgical, Alcon, Inc., Thompson Surgical Instruments Inc., Scanlan International, Inc., CooperSurgical Inc., Sklar Surgical Instruments, Millennium Surgical Corp, Microline Surgical, Wexler Surgical, GSource, LLC |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on product type, application, and end-user to provide a granular view of the industry landscape. Product segmentation highlights the dominance of basic cutting and grasping instruments, while application analysis identifies the fastest-growing surgical fields. The end-user segment differentiates between traditional hospital settings and the rapidly expanding outpatient sector.
- By Product Type:
- Forceps and Spatulas: Essential for tissue manipulation and grasping.
- Scalpels and Blades: Primary cutting instruments for incisions.
- Scissors: Used for tissue dissection and suture cutting.
- Retractors: Crucial for maintaining exposure of the surgical site.
- Trocars and Cannulas: Vital for laparoscopic and minimally invasive access.
- Others: Including dilators, probes, and specialized suction tips.
- By Application:
- Orthopedic Surgery: Driven by joint replacements and trauma cases.
- Cardiovascular Surgery: Focused on specialized clamps and needle holders.
- Neurosurgery: Requires high-precision, fine-tipped micro-instruments.
- Obstetrics & Gynecology: Includes instruments for C-sections and laparoscopic procedures.
- Plastic & Reconstructive Surgery: Demand for aesthetic-grade precision tools.
- Other Applications: General surgery, urology, and ENT.
- By End-User:
- Hospitals: The largest consumer base for comprehensive surgical kits.
- Ambulatory Surgical Centers (ASCs): Increasing demand for specialized, efficient instrument sets.
- Specialized Clinics: Focus on outpatient dermatology, ophthalmology, and dental surgeries.
Regional Highlights
- North America: This region dominates the market share due to a high volume of complex surgeries and presence of major medical device manufacturers. The United States leads in the adoption of advanced ergonomic instruments and single-use technologies.
- Europe: Characterized by a robust regulatory environment and a focus on reusable instrument quality. Germany and the UK are key hubs for surgical instrument manufacturing and innovation.
- Asia-Pacific: This is the fastest-growing region, with China and India expanding their healthcare infrastructure. Rising medical tourism and increasing insurance coverage are significant growth catalysts.
- Latin America: Growth is driven by healthcare reforms and an increase in surgical procedures in countries like Brazil and Mexico.
- Middle East & Africa: Improving healthcare access and investment in new hospital projects are creating a steady demand for foundational surgical instrument sets.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Hand Held Surgical Instruments Market.- B. Braun Melsungen AG
- Becton, Dickinson and Company (BD)
- Medtronic plc
- Smith & Nephew plc
- Zimmer Biomet Holdings, Inc.
- Johnson & Johnson (Ethicon)
- Stryker Corporation
- Integra LifeSciences
- Aspen Surgical
- Alcon, Inc.
- Thompson Surgical Instruments Inc.
- Scanlan International, Inc.
- CooperSurgical Inc.
- Sklar Surgical Instruments
- Millennium Surgical Corp
- Microline Surgical
- Wexler Surgical
- GSource, LLC
- Hu-Friedy Mfg. Co., LLC
- KLS Martin Group
Frequently Asked Questions
What is the projected growth rate of the Hand Held Surgical Instruments Market?
The Hand Held Surgical Instruments Market is projected to grow at a CAGR of 7.4% from 2025 to 2034, driven by the increasing volume of global surgical procedures and advancements in minimally invasive techniques.
Which product segment holds the largest share in the Hand Held Surgical Instruments Market?
The forceps and spatulas segment currently holds the largest market share. These instruments are fundamental to almost every surgical discipline, ensuring consistent demand across all healthcare facilities.
How is the rise of Minimally Invasive Surgery (MIS) impacting the market?
MIS is driving the demand for specialized, smaller, and more precise hand held instruments such as trocars, cannulas, and micro-scissors, as surgeons require tools that can function effectively through small incisions.
Which region is expected to witness the fastest growth during the forecast period?
The Asia-Pacific (APAC) region is expected to be the fastest-growing market due to rapid healthcare infrastructure development, a growing patient population, and the expansion of medical tourism in countries like Thailand and India.
What are the key materials used in high-quality hand held surgical instruments?
High-quality instruments primarily use medical-grade stainless steel and titanium. Titanium is increasingly favored for its high strength-to-weight ratio, corrosion resistance, and non-magnetic properties, which are essential for various surgical environments.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted