Group 2 Powered Mobility Devices Market
Group 2 Powered Mobility Devices Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711578 | Published On : November 07, 2026 |
Format : 


 | Author : Ashraf Shehata
Group 2 Powered Mobility Devices Market Size
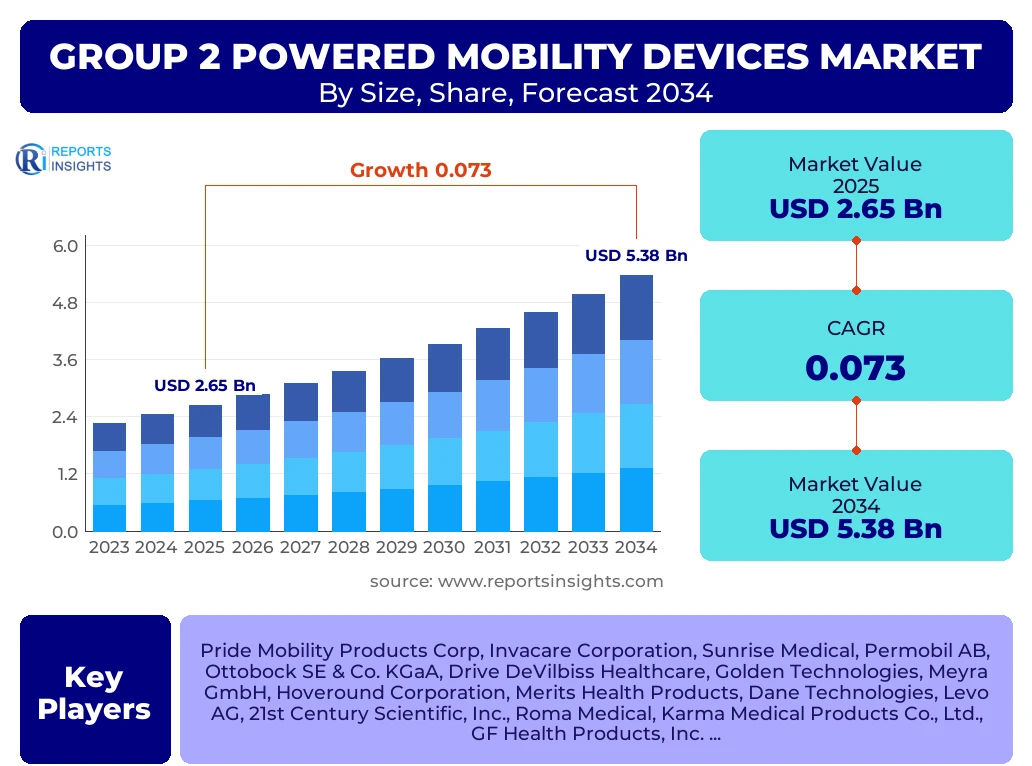
According to Reports Insights Consulting Pvt Ltd, The Group 2 Powered Mobility Devices Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.3% between 2025 and 2034. The market is estimated at USD 2.85 Billion in 2026 and is projected to reach USD 5.38 Billion by the end of the forecast period in 2034.
The Group 2 powered mobility devices segment represents a crucial middle-ground in the assistive technology landscape, specifically targeting patients with limited mobility who require more than a standard manual wheelchair but do not necessitate the complex electronics of Group 3 or 4 units. These devices, primarily categorized as standard power wheelchairs with basic joystick controllers and captain’s or solid seat/back configurations, are witnessing a surge in adoption due to the rising prevalence of orthopedic and neurological disorders. Manufacturers are increasingly focusing on modular designs that allow for minor modifications while maintaining cost-effectiveness for reimbursement through Medicare and private insurance providers.
The valuation of the market is heavily influenced by the aging global demographic, particularly in developed nations where the "silver economy" is driving demand for reliable, long-term mobility solutions. Technological advancements in battery longevity, such as the transition from lead-acid to lithium-ion configurations, are enhancing the range and durability of these devices. Furthermore, the integration of lightweight aluminum and composite frames is making Group 2 devices more portable, addressing a primary consumer pain point regarding transportability. As healthcare infrastructure improves in emerging economies, the market is poised for significant volume growth, supported by localized manufacturing and broader distribution networks.
Key Group 2 Powered Mobility Devices Market Trends & Insights
The current market landscape for Group 2 powered mobility devices is characterized by a significant shift toward user-centric design and the integration of IoT-enabled features for remote monitoring. Users and caregivers are increasingly seeking devices that offer smart diagnostics to predict battery failure or motor issues before they occur. Geographically, North America remains the dominant revenue generator due to established reimbursement codes, while the Asia-Pacific region is experiencing the fastest expansion, driven by rapid urbanization and an increasing middle-class population in China and India. Competitive benchmarking reveals that leading companies are diversifying their portfolios to include "travel-ready" Group 2 chairs that can be disassembled easily, catering to an active aging population that values lifestyle continuity alongside mobility assistance.
- Largest Region: North America, holding a market share of approximately 38% due to favorable healthcare policies and high patient awareness.
- Fastest Growing Region: Asia-Pacific, with a projected CAGR of 8.9% during the forecast period.
- Largest Segment by Share: Standard Power Wheelchairs with Captain’s Seating, accounting for the majority of the market volume.
- Leading End-User: Homecare settings, which dominate as aging-in-place becomes the preferred model for elderly care.
- Technological Trend: Adoption of brushless DC motors to increase energy efficiency and reduce maintenance requirements.
Key Takeaways Group 2 Powered Mobility Devices Market Size & Forecast
The Group 2 Powered Mobility Devices market is entering a phase of sustained growth, anchored by the fundamental need for mobility among patients with chronic conditions like obesity, multiple sclerosis, and advanced arthritis. Stakeholders are focusing on the total cost of ownership, as payers demand more durable and reliable devices to minimize long-term replacement costs. The forecast indicates a steady upward trajectory, with the 2034 valuation reflecting a robust recovery and expansion post-pandemic, where supply chain stabilities have allowed for consistent product rollouts. Insights suggest that manufacturers who prioritize ergonomic seating and intuitive control interfaces will capture the largest market share in the coming decade.
- Leading Country: The United States continues to lead in value, supported by the Medicare Part B benefit for durable medical equipment.
- Forecast Precision: The market is expected to cross the USD 4 billion mark by 2030, showing resilience against inflationary pressures.
- Strategic Shift: Transition from traditional retail models to e-commerce and direct-to-consumer (DTC) channels is accelerating in the European market.
- Product Innovation: Integration of regenerative braking systems to extend battery life per charge cycle.
- Market Driver: Increasing incidence of lifestyle-related disabilities requiring non-complex powered mobility solutions.
Group 2 Powered Mobility Devices Market Drivers Analysis
The primary growth engine for the Group 2 powered mobility devices sector is the global demographic shift toward an older population, which is statistically more likely to experience mobility impairments. Furthermore, the rising incidence of bariatric conditions necessitates high-weight-capacity Group 2 devices that offer stability without the excessive cost of custom Group 3 units. Regulatory support and standardized reimbursement frameworks in Western Europe and North America provide a predictable revenue stream for manufacturers, encouraging long-term R&D investments in motor efficiency and frame durability.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Population & Geriatric Care Demand | +2.1% | Global (High in Japan/Germany) | 2025-2034 |
| Advancements in Battery Technology | +1.5% | North America & Europe | 2026-2030 |
| Expansion of Home Healthcare Infrastructure | +1.2% | Asia-Pacific | 2025-2034 |
| Rise in Obesity and Related Mobility Issues | +1.0% | United States & UK | 2025-2032 |
Group 2 Powered Mobility Devices Market Restraints Analysis
Despite the positive growth outlook, the market faces significant hurdles related to the high initial cost of powered devices compared to manual alternatives, particularly in low-to-middle-income countries where out-of-pocket spending is high. Additionally, stringent and often complex reimbursement criteria can delay market penetration, as physicians must provide extensive documentation to prove medical necessity for a Group 2 device over a less expensive option. Technical limitations regarding the weight of lead-acid batteries also remain a deterrent for users who require frequent device transport.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Purchase Cost | -1.2% | Latin America & Africa | 2025-2034 |
| Stringent Reimbursement Policies | -0.9% | United States (Medicare) | 2025-2028 |
| Lack of Maintenance Infrastructure | -0.5% | Emerging Markets | 2026-2030 |
Group 2 Powered Mobility Devices Market Opportunities Analysis
The emergence of lightweight, foldable Group 2 power wheelchairs presents a massive opportunity for manufacturers to tap into the travel and leisure market for the elderly. By utilizing carbon fiber materials and compact motor designs, companies can offer products that fit into standard vehicle trunks, a feature currently in high demand. Furthermore, the integration of artificial intelligence for collision avoidance and semi-autonomous navigation in indoor environments represents a high-value growth avenue for premium Group 2 models.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Smart Connectivity and IoT Integration | +1.8% | North America & EU5 | 2027-2034 |
| Eco-friendly Recycling Programs for Batteries | +0.6% | Europe | 2026-2034 |
| Customization of Ergonomic Components | +1.1% | Global | 2025-2034 |
Group 2 Powered Mobility Devices Market Challenges Impact Analysis
A major challenge in the industry is the volatility of raw material prices, particularly for lithium and specialized metals used in motor magnets, which can fluctuate based on global trade tensions. Additionally, manufacturers must navigate a fragmented regulatory landscape, where safety standards and certification requirements differ significantly between the FDA in the US, the CE mark in Europe, and the NMPA in China. Ensuring consistent product quality while scaling production to meet rising demand remains a logistical hurdle for mid-sized players.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability for Semiconductors | -0.7% | Global | 2025-2027 |
| Intense Price Competition from Low-Cost Manufacturers | -1.1% | Asia-Pacific | 2025-2034 |
| Rapid Technological Obsolescence | -0.4% | Developed Markets | 2028-2034 |
Group 2 Powered Mobility Devices Market - Updated Report Scope
The report provides a deep-dive analysis into the Group 2 powered mobility devices sector, encompassing a detailed evaluation of product types, battery technologies, and end-user demographics. It covers the transition from traditional lead-acid systems to modern energy solutions and analyzes the impact of regulatory changes on market dynamics. The scope extends to a comprehensive competitive landscape, identifying the strategic maneuvers of top-tier companies and emerging innovators across six major geographical regions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.65 Billion |
| Market Forecast in 2034 | USD 5.38 Billion |
| Growth Rate | 7.3% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Pride Mobility Products Corp, Invacare Corporation, Sunrise Medical, Permobil AB, Ottobock SE & Co. KGaA, Drive DeVilbiss Healthcare, Golden Technologies, Meyra GmbH, Hoveround Corporation, Merits Health Products, Dane Technologies, Levo AG, 21st Century Scientific, Inc., Roma Medical, Karma Medical Products Co., Ltd., GF Health Products, Inc., Heartway Medical Products, Zip'r Mobility. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Group 2 Powered Mobility Devices market is intricately segmented to reflect the diverse clinical needs of the patient population and the technological variations of the devices. The segmentation by product type reveals a growing preference for portable units that do not compromise the stability of a Group 2 frame. Seating segmentation highlights the shift toward ergonomic captain’s seats for long-duration comfort, while the battery segment is currently undergoing a massive transition as lithium-ion technology becomes more affordable and safer for air travel.
- By Product Type:
- Standard Group 2 Power Wheelchairs
- Travel/Portable Group 2 Power Wheelchairs
- Heavy Duty/Bariatric Group 2 Devices
- By Seating Configuration:
- Captain’s Seating (Fixed & Reclining)
- Solid Seat and Back
- Adjustable Tension Back Seating
- By Drive System:
- Rear-Wheel Drive (Stability focus)
- Mid-Wheel Drive (Maneuverability focus)
- Front-Wheel Drive (Obstacle climbing focus)
- By End-User:
- Homecare Settings
- Long-term Care Facilities
- Hospitals and Acute Care
- Rehabilitation Centers
Regional Highlights
- North America: The largest market, driven by the United States, where Medicare and private insurers have established clear HCPCS codes (e.g., K0822, K0823) for Group 2 devices, ensuring high adoption rates.
- Europe: A mature market focused on high-quality engineering and safety standards. Countries like Germany and the UK lead in the adoption of lightweight materials and advanced control systems.
- Asia-Pacific: The fastest-growing region. China and India are seeing a surge in demand due to an expanding geriatric population and increasing government spending on assistive technologies for the disabled.
- Latin America: Growth is concentrated in Brazil and Mexico, where urban development is improving accessibility and rising disposable incomes are allowing for more out-of-pocket mobility purchases.
- Middle East & Africa: An emerging market where infrastructure development and medical tourism are creating new opportunities for premium mobility device suppliers.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Group 2 Powered Mobility Devices Market.
- Pride Mobility Products Corp
- Invacare Corporation
- Sunrise Medical
- Permobil AB
- Ottobock SE & Co. KGaA
- Drive DeVilbiss Healthcare
- Golden Technologies
- Meyra GmbH
- Hoveround Corporation
- Merits Health Products
- Dane Technologies
- Levo AG
- 21st Century Scientific, Inc.
- Roma Medical
- Karma Medical Products Co., Ltd.
- GF Health Products, Inc.
- Heartway Medical Products
- Zip'r Mobility
- Hoveround Corporation
- Kuschall (Invacare)
Frequently Asked Questions
What is the primary difference between Group 1 and Group 2 powered mobility devices?
Group 2 devices offer significantly higher durability, battery range, and speed compared to Group 1. While Group 1 is designed for intermittent use on flat surfaces, Group 2 is built for daily, long-term use and can accommodate more sophisticated seating and electronics, making it suitable for patients with permanent mobility impairments.
Does Medicare cover Group 2 powered wheelchairs?
Yes, Medicare Part B covers Group 2 power wheelchairs as Durable Medical Equipment (DME) if a physician and a physical/occupational therapist perform a face-to-face evaluation and determine that a manual wheelchair or a scooter is insufficient for the patient's activities of daily living (ADLs) within the home.
How long is the typical battery life for a Group 2 device?
On average, a Group 2 powered mobility device provides a range of 10 to 20 miles per charge, depending on the battery type (Lead-Acid vs. Lithium-Ion), user weight, and terrain. The battery lifespan usually ranges from 12 to 24 months with regular daily use.
What are the current technological trends in the Group 2 market?
The market is currently seeing a trend toward smart controllers with Bluetooth connectivity for smartphone integration, the use of magnesium and carbon fiber for weight reduction, and the adoption of high-efficiency motors that extend the travel range by up to 15% per charge.
Which region offers the highest growth potential for investors?
The Asia-Pacific region offers the highest growth potential due to the sheer volume of the aging population and the rapid improvement in healthcare accessibility. While North America provides higher margins, the volume growth in APAC is expected to outpace all other regions through 2034.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
