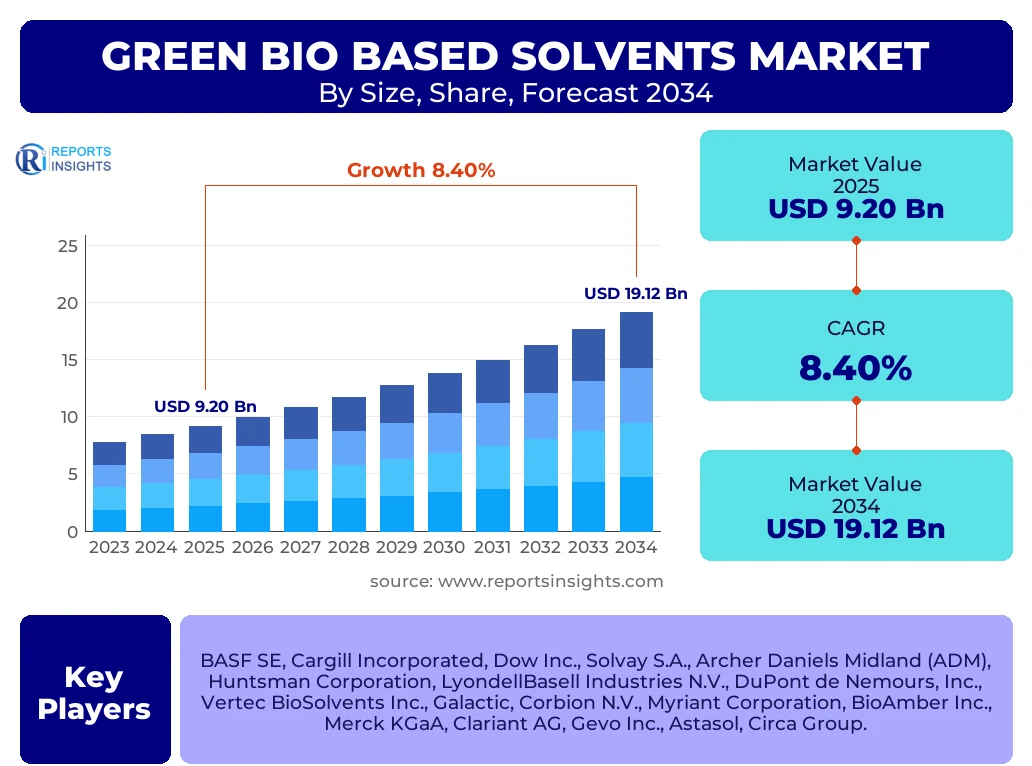
Green Bio Based Solvents Market
Green Bio Based Solvents Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711341 | Published On : October 28, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Green Bio Based Solvents Market Size
According to Reports Insights Consulting Pvt Ltd, The Green Bio Based Solvents Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 9.97 Billion in 2026 and is projected to reach USD 19.12 Billion by the end of the forecast period in 2034.
Key Green Bio Based Solvents Market Trends & Insights
The global shift toward sustainable chemistry is fundamentally altering the industrial solvent landscape, moving away from conventional petroleum-derived chemicals toward bio-based alternatives. User queries and industrial procurement patterns indicate a significant focus on reducing Volatile Organic Compound (VOC) emissions to meet stringent environmental standards such as REACH in Europe and the EPA’s Clean Air Act in the United States. Furthermore, the integration of circular economy principles is driving innovation in feedstock sourcing, with manufacturers increasingly utilizing agricultural waste and non-food biomass to avoid competition with food supply chains. Competitive benchmarking reveals that market leaders are investing heavily in bio-refinery infrastructure to achieve economies of scale, which is essential for narrowing the price gap between green and synthetic solvents.
- Largest Region: North America currently holds the largest market share due to established regulatory frameworks and high demand in the paints and coatings sector.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR, fueled by rapid industrialization in China and India and increasing environmental awareness.
- Largest Segment by Type: Lactate esters represent the largest segment by share, valued for their biodegradability and effectiveness in cleaning applications.
- Largest Segment by Application: Paints and Coatings continue to be the dominant application area, accounting for over 40% of the total market volume.
Key Takeaways Green Bio Based Solvents Market Size & Forecast
The market trajectory for green bio-based solvents is characterized by a transition from niche application to mainstream industrial adoption. Strategic analysis of user concerns highlights that while performance parity with traditional solvents has largely been achieved, the primary market focus is now on supply chain stability and price volatility of bio-feedstocks. The forecast period anticipates a surge in the adoption of soy methyl esters and citrus-based solvents, particularly in the consumer-facing segments like personal care and household detergents. Stakeholders are prioritizing suppliers who can provide life-cycle assessment (LCA) data to prove the carbon footprint reduction of their products.
- The United States and Germany are leading the transition, with significant investments in bio-based chemical clusters.
- Technological advancements in fermentation and catalytic conversion are expected to lower production costs by 15-20% by 2030.
- The pharmaceutical industry is emerging as a high-value consumer of bio-based glycols due to their low toxicity and high purity.
- Regulatory mandates phasing out methylene chloride and N-Methyl-2-pyrrolidone (NMP) are creating immediate replacement opportunities for bio-based alternatives.
Green Bio Based Solvents Market Drivers Analysis
The primary catalysts for the green bio-based solvents market are rooted in regulatory pressure and the corporate sustainability movement. As global governments implement stricter limits on VOCs and hazardous air pollutants, industries are forced to seek safer alternatives. Additionally, the fluctuating price of crude oil makes bio-based solvents an increasingly attractive hedge against petrochemical price spikes. Consumer preference for "green" labels in household and personal care products further incentivizes manufacturers to reformulate their offerings using bio-derived ingredients.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent VOC Regulations (REACH/EPA) | +3.2% | European Union & North America | 2025 - 2034 |
| Consumer Demand for Sustainable Personal Care | +2.1% | Global | 2025 - 2030 |
| Technological Gains in Bio-Refining | +1.8% | Asia-Pacific & Brazil | 2027 - 2034 |
| Fluctuating Petrochemical Feedstock Prices | +1.3% | Global | Continuous |
Green Bio Based Solvents Market Restraints Analysis
Despite the positive growth outlook, the market faces significant hurdles related to production costs and technical limitations. Bio-based solvents often require higher energy inputs for purification and processing, leading to a premium price point that can deter cost-sensitive industries. Furthermore, the seasonal nature of agricultural feedstocks can lead to supply inconsistencies, challenging the reliability of large-scale industrial operations that require year-round availability.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Raw Material Processing | -1.5% | Global | 2025 - 2028 |
| Feedstock Availability & Seasonality | -1.1% | Latin America & Southeast Asia | Short to Medium Term |
Green Bio Based Solvents Market Opportunities Analysis
Emerging opportunities in the green solvent sector are predominantly found in the development of "designer" solvents tailored for specific high-performance applications. The expansion of the electric vehicle (EV) market and electronic manufacturing offers a new frontier for specialized bio-based cleaners and degreasers. Furthermore, the exploration of aquatic biomass (algae) as a feedstock represents a breakthrough opportunity to produce solvents without utilizing arable land, addressing the "food vs. fuel" debate.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption in Electronic Cleaning & Degreasing | +2.5% | Japan, South Korea, Taiwan | 2026 - 2034 |
| Use of Non-Food Feedstocks (Cellulosic Ethanol) | +1.9% | United States & China | 2028 - 2034 |
Green Bio Based Solvents Market Challenges Impact Analysis
The primary challenge lies in the performance gap for specific heavy-duty industrial applications where traditional solvents like toluene or xylene currently offer superior solvency power. Achieving the same level of effectiveness with bio-based alternatives without increasing application time or volume remains a technical hurdle for R&D teams. Additionally, the lack of standardized global certification for "green" solvents can lead to market confusion and greenwashing concerns.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Performance Parity in Heavy-Duty Degreasing | -0.8% | Germany & United States | Long Term |
| Lack of Global Standardization | -0.5% | Global | Short Term |
Green Bio Based Solvents Market - Updated Report Scope
This report provides a comprehensive analysis of the global green bio-based solvents market, covering technical specifications, economic drivers, and competitive dynamics. The scope includes a detailed breakdown of chemical types derived from renewable sources and their multi-sectoral applications. It utilizes data-driven forecasting models to project market evolution through 2034, incorporating regional macroeconomic factors and industry-specific regulatory trends.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 9.20 Billion |
| Market Forecast in 2034 | USD 19.12 Billion |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Cargill Incorporated, Dow Inc., Solvay S.A., Archer Daniels Midland (ADM), Huntsman Corporation, LyondellBasell Industries N.V., DuPont de Nemours, Inc., Vertec BioSolvents Inc., Galactic, Corbion N.V., Myriant Corporation, BioAmber Inc., Merck KGaA, Clariant AG, Gevo Inc., Astasol, Circa Group. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The green bio-based solvents market is segmented based on chemical type, application, and feedstock source. This granularity allows for a deeper understanding of which sectors are driving growth and where technical innovations are most concentrated. Lactate esters and bio-alcohols currently dominate the market due to their versatility and established production pathways. From an application perspective, the paints and coatings sector remains the primary consumer, though the personal care and pharmaceutical sectors are growing at a faster rate due to the non-toxic nature of these solvents.
- By Type:
- Lactate Esters: Primarily ethyl lactate, used extensively in electronics and pharmaceutical cleaning.
- Alcohols: Includes bio-ethanol and bio-butanol, serving as foundational building blocks for various chemical synthesis.
- Glycols: Bio-based propylene glycol used in food, pharma, and de-icing applications.
- Terpenes & D-Limonene: Extracted from citrus and pine, used in high-performance degreasing.
- Soy Methyl Esters: Gaining traction in printing inks and agricultural applications.
- By Application:
- Paints & Coatings: Driven by the transition to low-VOC architectural coatings.
- Industrial & Institutional Cleaners: Replacing harsh chemicals in commercial cleaning agents.
- Personal Care: Used as carriers for active ingredients in cosmetics and sunscreens.
- Pharmaceuticals: High-purity bio-solvents used in drug formulation and extraction.
- By Source:
- Sugarcane & Corn: Main sources for bio-alcohols and lactates.
- Soy & Citrus: Essential for esters and limonene-based products.
- Lignocellulosic Biomass: The next-generation feedstock offering improved sustainability profiles.
Regional Highlights
- North America: The largest market globally, characterized by high adoption in the industrial sector and strong support from the USDA BioPreferred program. The United States leads in soy methyl ester production.
- Europe: The most regulated market with the strictest VOC emission standards. Germany, France, and the Netherlands are hubs for bio-chemical innovation and sustainable manufacturing.
- Asia-Pacific: The fastest-growing region. China and India are shifting from traditional solvents to green alternatives to combat urban air pollution. Increasing capacity in Thailand and Malaysia for palm-derived solvents is a key trend.
- Latin America: Dominated by Brazil, which utilizes its massive sugarcane industry to produce bio-ethanol and related solvents at a competitive cost.
- Middle East & Africa: A developing market where green solvents are beginning to find use in the oil and gas sector for environmentally sensitive cleaning operations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Green Bio Based Solvents Market.- BASF SE
- Cargill Incorporated
- Dow Inc.
- Solvay S.A.
- Archer Daniels Midland (ADM)
- Huntsman Corporation
- LyondellBasell Industries N.V.
- DuPont de Nemours, Inc.
- Vertec BioSolvents Inc.
- Galactic
- Corbion N.V.
- Myriant Corporation
- BioAmber Inc.
- Merck KGaA
- Clariant AG
- Gevo Inc.
- Astasol
- Circa Group
Frequently Asked Questions
What are the primary benefits of using green bio-based solvents over conventional ones?
Green bio-based solvents offer significantly lower toxicity, reduced Volatile Organic Compound (VOC) emissions, and a smaller carbon footprint. They are derived from renewable resources like corn, soy, and sugarcane, making them more sustainable and safer for both human health and the environment compared to petroleum-based solvents.
Which industry is the largest consumer of green bio-based solvents?
The paints and coatings industry is the largest consumer, utilizing these solvents to comply with environmental regulations regarding air quality and to meet the growing consumer demand for eco-friendly home improvement products.
How does the cost of bio-based solvents compare to traditional solvents?
Currently, bio-based solvents often carry a price premium due to higher production costs and smaller economies of scale. However, as bio-refining technology matures and petroleum prices fluctuate, the price gap is narrowing, making green solvents increasingly competitive.
Are green solvents as effective as petroleum-based solvents?
In many applications, such as pharmaceutical manufacturing, personal care, and light industrial cleaning, green solvents offer performance that is equal to or better than traditional options. However, for certain heavy-duty degreasing tasks, research is ongoing to achieve full performance parity.
What is the impact of government regulations on this market?
Regulations are a major driver for growth. Policies like REACH in Europe and various EPA mandates in the U.S. restrict the use of hazardous solvents, effectively forcing manufacturers to adopt bio-based, non-toxic alternatives to maintain market access.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
