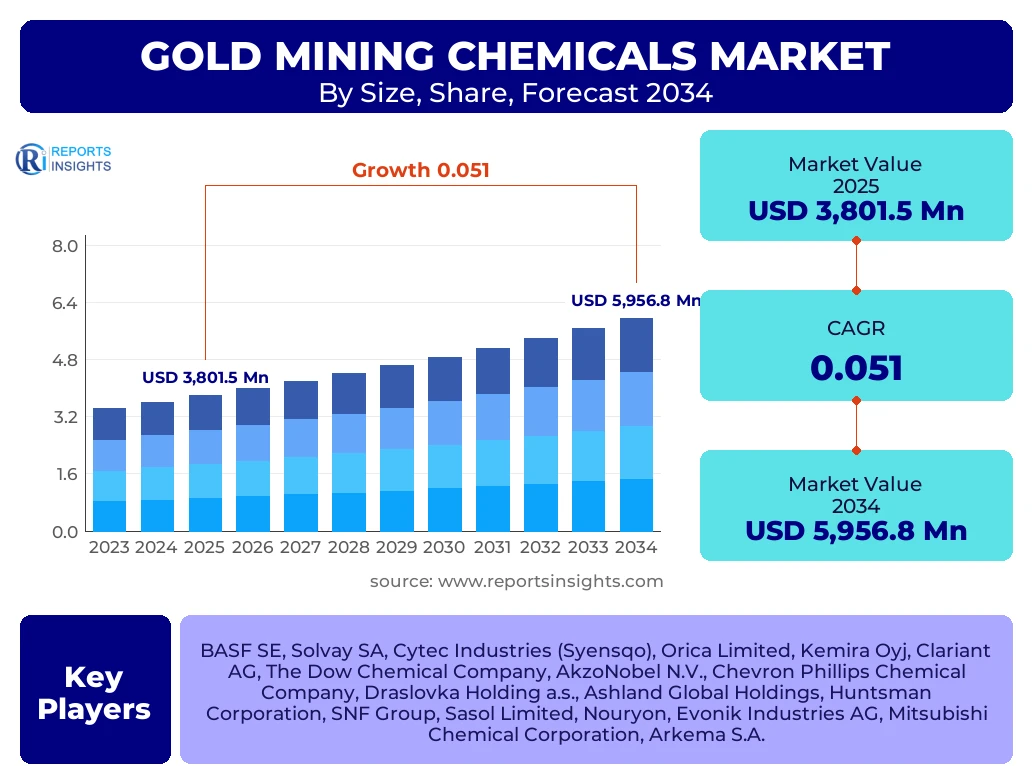
Gold Mining Chemicals Market
Gold Mining Chemicals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711431 | Published On : November 01, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Gold Mining Chemicals Market Size
According to Reports Insights Consulting Pvt Ltd, The Gold Mining Chemicals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.1% between 2025 and 2034. The market is estimated at USD 3,995.4 Million in 2026 and is projected to reach USD 5,956.8 Million by the end of the forecast period in 2034.
Key Gold Mining Chemicals Market Trends & Insights
The global gold mining chemicals sector is undergoing a profound transformation driven by the depletion of high-grade ore reserves and the subsequent need for sophisticated chemical interventions to extract gold from complex, low-grade deposits. Stakeholders are increasingly prioritizing environmentally sustainable chemical alternatives, such as non-cyanide leaching agents and biodegradable collectors, to align with tightening global Environmental, Social, and Governance (ESG) mandates. Additionally, the integration of automated chemical dosing systems and real-time monitoring technologies is optimizing reagent consumption, reducing operational expenditures, and enhancing safety protocols across large-scale mining operations.
- Asia Pacific is the largest region in terms of market share, driven primarily by extensive mining activities in China and Australia.
- Africa is identified as the fastest-growing region, fueled by untapped reserves in the Birimian Greenstone Belt and increasing foreign direct investment in West African mining projects.
- The Sodium Cyanide segment currently holds the largest market share due to its unparalleled efficiency in gold recovery via the cyanidation process, despite rising regulatory scrutiny.
- Innovation in Thiosulfate and Glycine leaching is gaining traction as a viable alternative for refractory ore bodies where traditional methods are less effective.
- The adoption of specialty chemicals, including flocculants and grinding aids, is rising as mines seek to improve throughput and tailings management efficiency.
Key Takeaways Gold Mining Chemicals Market Size & Forecast
The gold mining chemicals market is characterized by a steady upward trajectory, supported by the intrinsic value of gold as a hedge against inflation and geopolitical instability. As mining companies transition toward deeper underground operations and process more mineralogically complex ores, the intensity of chemical usage per ounce of gold produced is expected to rise. This shift necessitates a strategic focus on specialty reagents that can perform under high-pressure and high-temperature conditions while minimizing the environmental footprint of mining effluents.
- China remains the leading country in both production and consumption of gold mining chemicals, followed closely by Australia and Russia.
- The forecast indicates a significant shift toward the use of activated carbon for Carbon-in-Leach (CIL) and Carbon-in-Pulp (CIP) processes to maximize recovery rates.
- Sustainable tailings management is emerging as a critical market driver, boosting the demand for advanced polymers and coagulants.
- Market players are focusing on strategic partnerships with mining conglomerates to provide end-to-end chemical management services.
- The volatility in raw material prices for chemical synthesis remains a key factor influencing the profit margins of manufacturers.
Gold Mining Chemicals Market Drivers Analysis
The primary catalysts for the gold mining chemicals market involve the escalating global demand for gold and the technical necessity of chemical reagents in processing lower-grade ores. As traditional high-grade mines reach maturity, the industry is forced to process larger volumes of material to maintain output, which directly correlates to higher reagent consumption. Furthermore, the expansion of mining infrastructure in developing economies provides a fertile ground for market growth.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Declining Ore Grades | +1.8% | Global (Australia, Canada, USA) | 2025 - 2034 |
| Rising Gold Prices and Investment | +1.5% | Global | 2026 - 2030 |
| Expansion of Mining in Emerging Economies | +1.2% | Africa and Latin America | 2025 - 2034 |
| Technological Advancements in Extraction | +0.6% | North America and Europe | 2027 - 2034 |
Gold Mining Chemicals Market Restraints Analysis
The market faces significant headwinds from environmental regulations that restrict the use of hazardous substances like cyanide and mercury. These regulations often lead to increased compliance costs or the total ban of certain chemicals in sensitive ecological zones. Additionally, the logistical challenges and high costs associated with transporting hazardous chemicals to remote mining sites act as a barrier to market expansion.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental Regulations | -1.2% | European Union and North America | 2025 - 2034 |
| High Logistics and Handling Costs | -0.8% | Russia and Central Asia | 2025 - 2030 |
| Water Scarcity in Mining Hubs | -0.5% | Australia and Chile | 2026 - 2034 |
Gold Mining Chemicals Market Opportunities Analysis
Emerging opportunities in the gold mining chemicals market are centered around the development of green chemistry and the circular economy. The potential for bio-leaching using microbial agents and the recovery of chemicals from tailings presents a significant growth avenue. Furthermore, the rise of digital mining allows for the precise application of chemicals, opening doors for high-value specialty reagent providers to offer integrated solutions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Non-Cyanide Leaching Agents | +1.4% | Global | 2027 - 2034 |
| Digitalization and Precision Dosing | +0.9% | Australia and Canada | 2025 - 2034 |
| Tailings Reprocessing Technologies | +0.7% | South Africa and Ghana | 2028 - 2034 |
Gold Mining Chemicals Market Challenges Impact Analysis
Market participants must navigate complex challenges ranging from geopolitical instability in gold-rich regions to the extreme volatility of raw material prices. The social license to operate is increasingly tied to chemical safety, and any environmental incident can lead to severe legal and financial repercussions for chemical suppliers and mining operators alike.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Geopolitical Instability | -0.9% | Middle East and Parts of Africa | 2025 - 2034 |
| Raw Material Price Volatility | -0.7% | Global | 2025 - 2028 |
| Social License and Safety Concerns | -0.4% | Latin America | 2026 - 2034 |
Gold Mining Chemicals Market - Updated Report Scope
The scope of this report encompasses a detailed quantitative and qualitative analysis of the global gold mining chemicals market across various segments including chemical type, application, and geography. It examines the historical performance from 2020 to 2024 and provides a robust forecast from 2026 to 2034, considering the macroeconomic factors, technological shifts, and regulatory frameworks currently shaping the industry. This report is designed to assist stakeholders in identifying high-growth areas and developing strategies to mitigate risks associated with chemical handling and environmental compliance.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3,801.5 Million |
| Market Forecast in 2034 | USD 5,956.8 Million |
| Growth Rate | 5.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Solvay SA, Cytec Industries (Syensqo), Orica Limited, Kemira Oyj, Clariant AG, The Dow Chemical Company, AkzoNobel N.V., Chevron Phillips Chemical Company, Draslovka Holding a.s., Ashland Global Holdings, Huntsman Corporation, SNF Group, Sasol Limited, Nouryon, Evonik Industries AG, Mitsubishi Chemical Corporation, Arkema S.A. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The gold mining chemicals market is segmented based on chemical functionality and the specific stage of the gold recovery process. The leaching and extraction segment remains the dominant application area, primarily due to the extensive use of cyanides and collectors. However, the milling and flotation segments are witnessing rapid growth as miners deal with increasingly complex polymetallic ores that require advanced separation techniques. Tailings treatment is also a burgeoning segment, driven by environmental mandates to neutralize toxic residues before disposal.
- By Chemical Type:
- Sodium Cyanide (Largest share due to efficacy in leaching)
- Activated Carbon (Essential for CIL/CIP processes)
- Grinding Aids (Used to reduce energy consumption in milling)
- Flocculants & Coagulants (Critical for solid-liquid separation and water recycling)
- Collectors & Frothers (Vital for the flotation of auriferous sulfides)
- Lead Nitrate (Used as an accelerant in cyanidation)
- By Application:
- Extraction & Leaching
- Milling & Grinding
- Flotation & Concentration
- Tailings & Water Treatment
- By Mining Method:
- Open Pit Mining (High volume consumption)
- Underground Mining (High precision chemical usage)
Regional Highlights
The regional distribution of the gold mining chemicals market reveals a strong concentration of demand in areas with significant geological endowments and established mining infrastructures. Asia Pacific, led by China and Australia, dominates the global market share, supported by large-scale open-pit operations and heavy investment in processing technologies. Africa is emerging as a critical growth frontier, with countries like Ghana, Mali, and Burkina Faso attracting substantial exploration capital, which in turn drives the demand for extraction chemicals.
- Asia Pacific: Holds approximately 35% of the global market share, with Australia being a major hub for technical innovation in reagent application.
- Africa: Expected to witness the highest CAGR due to the rapid development of the Birimian Greenstone Belt and increasing mining yields.
- North America: A mature market focused on high-efficiency chemicals and strict environmental compliance, particularly in Nevada (USA) and Ontario (Canada).
- Latin America: Driven by massive projects in Peru, Chile, and Brazil, with a focus on overcoming complex mineralogy in the Andean regions.
- Europe & CIS: Russia remains a key player, contributing significantly to the demand for high-purity sodium cyanide and activated carbon.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Gold Mining Chemicals Market.- BASF SE
- Solvay SA
- Syensqo (formerly Cytec)
- Orica Limited
- Kemira Oyj
- Clariant AG
- The Dow Chemical Company
- AkzoNobel N.V.
- Chevron Phillips Chemical Company
- Draslovka Holding a.s.
- Ashland Global Holdings
- Huntsman Corporation
- SNF Group
- Sasol Limited
- Nouryon
- Evonik Industries AG
- Mitsubishi Chemical Corporation
- Arkema S.A.
- DuPont de Nemours, Inc.
- SUEZ Water Technologies & Solutions
Frequently Asked Questions
What is the current market valuation of the Gold Mining Chemicals Market?
The market is estimated to be valued at USD 3,995.4 Million in 2026 and is projected to grow to USD 5,956.8 Million by 2034, growing at a CAGR of 5.1%.
Which chemical type dominates the gold mining industry?
Sodium Cyanide remains the dominant chemical type due to its cost-effectiveness and high gold recovery rates in the cyanidation process, although alternatives are gaining ground.
How are environmental regulations impacting the market?
Regulations are driving the industry toward green chemistry, resulting in the development of non-toxic leaching agents like thiosulfate and more efficient tailings treatment chemicals to ensure ESG compliance.
Which region is expected to show the fastest growth?
Africa is anticipated to be the fastest-growing region, supported by extensive untapped gold reserves and an increasing number of active mining projects across the continent.
What are the key factors driving the demand for gold mining chemicals?
The primary drivers include the depletion of high-grade ores, the sustained high price of gold, and technological advancements that allow for the processing of complex and refractory ore bodies.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
