Glass Prefilled Syringes Glass Vials Packaging Equipment Market
Glass Prefilled Syringes Glass Vials Packaging Equipment Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711558 | Published On : November 06, 2026 |
Format : 


 | Author : Erika Grotto
Glass Prefilled Syringes Glass Vials Packaging Equipment Market Size
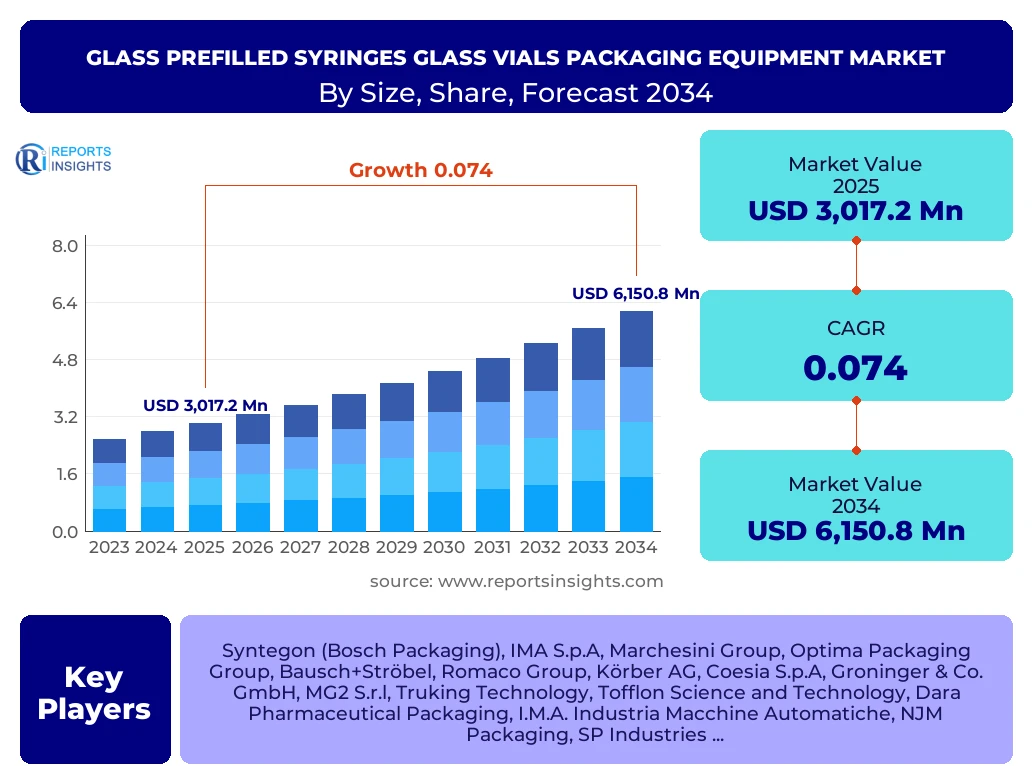
According to Reports Insights Consulting Pvt Ltd, The Glass Prefilled Syringes Glass Vials Packaging Equipment Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2025 and 2034. The market is estimated at USD 3,240.5 Million in 2026 and is projected to reach USD 6,150.8 Million by the end of the forecast period in 2034.
Key Glass Prefilled Syringes Glass Vials Packaging Equipment Market Trends & Insights
The global landscape for pharmaceutical packaging machinery is undergoing a transformative shift characterized by the rapid adoption of Industry 4.0 principles and the increasing demand for high-precision aseptic processing. Current market intelligence reveals that the convergence of biotechnology and advanced manufacturing is driving the necessity for highly flexible, modular packaging lines. Stakeholders are increasingly focusing on reducing total cost of ownership (TCO) while enhancing throughput and compliance with stringent Annex 1 regulatory standards. The integration of artificial intelligence for predictive maintenance and the deployment of robotic pick-and-place systems have become standard benchmarks for competitive differentiation among top-tier equipment manufacturers. Furthermore, the rise of "Ready-to-Use" (RTU) components is significantly altering machine design, moving away from traditional cleaning and sterilization tunnels toward more compact, specialized filling and sealing units.
- North America remains the largest regional market due to heavy investment in biologics and advanced therapeutic medicinal products (ATMPs).
- Asia Pacific is identified as the fastest-growing region, fueled by the expansion of Contract Manufacturing Organizations (CMOs) in India and China.
- The Filling and Closing Machine segment holds the largest market share, as it represents the most critical step in maintaining drug integrity and sterility.
- High-speed automated inspection systems are seeing the highest adoption rate among the sub-segments to meet zero-defect mandates in parenteral drug delivery.
Key Takeaways Glass Prefilled Syringes Glass Vials Packaging Equipment Market Size & Forecast
The market trajectory for glass prefilled syringes and vial packaging equipment is fundamentally linked to the global surge in chronic disease prevalence and the subsequent demand for injectable therapies. Market analysis suggests that the transition from multi-dose vials to single-dose prefilled syringes is a primary catalyst for equipment upgrades across the pharmaceutical sector. Forecasts indicate a robust growth path as healthcare providers prioritize patient safety and dosage accuracy, which are better served by factory-filled delivery systems. Additionally, the shift toward personalized medicine and orphan drugs is forcing equipment manufacturers to pivot from high-volume, low-mix production to low-volume, high-mix capabilities, often necessitating the use of isolator technology and restricted access barrier systems (RABS).
- The United States is the leading country in value, driven by a mature biopharmaceutical ecosystem and high healthcare expenditure.
- Germany serves as the primary hub for equipment innovation and engineering excellence, hosting several of the world’s leading packaging machinery companies.
- Modular machine configurations are becoming the preferred choice for pharmaceutical firms looking to future-proof their production lines against evolving product pipelines.
- Sustainability is emerging as a critical factor, with a growing emphasis on energy-efficient motors and reduced carbon footprints in manufacturing operations.
- The forecast period will see a significant increase in the integration of digital twins and virtual commissioning to reduce lead times for new equipment installation.
Glass Prefilled Syringes Glass Vials Packaging Equipment Market Drivers Analysis
The primary driver for this market is the exponential growth of the biologics and biosimilars sector. Biological drugs are often highly sensitive and require specialized primary packaging like glass vials and prefilled syringes to ensure stability. As more complex molecules enter the clinical pipeline, the demand for sophisticated filling lines that can handle fragile proteins without shear stress or temperature fluctuations is intensifying. This technological necessity is pushing pharmaceutical companies to retire legacy equipment in favor of advanced, nitrogen-purged, and vacuum-sealed packaging solutions.
Another significant driver is the global emphasis on immunization and the expansion of vaccine manufacturing capacities. Following the global health crises of the early 2020s, many nations have prioritized domestic vaccine production. This has led to a surge in orders for high-speed vial filling and labeling lines. Furthermore, the increasing trend of home-based healthcare and self-administration of drugs like insulin and monoclonal antibodies is boosting the prefilled syringe market, directly impacting the demand for specialized assembly and secondary packaging equipment that can integrate safety devices and auto-injectors.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Biologics and Biosimilars | +2.8% | Global (Primary: US & EU) | 2025 - 2034 |
| Adoption of Ready-to-Use (RTU) Components | +1.5% | Europe and Japan | 2026 - 2030 |
| Growth in Self-Administration Therapies | +1.2% | North America | 2025 - 2034 |
| Regulatory Mandates for Serialization | +0.9% | Global | 2025 - 2028 |
Glass Prefilled Syringes Glass Vials Packaging Equipment Market Restraints Analysis
One of the most pressing restraints is the high capital expenditure required for state-of-the-art aseptic packaging lines. The initial investment for an integrated isolator-based filling line can be prohibitive for small-to-medium enterprises and emerging biotech startups. This financial barrier often leads to longer replacement cycles for existing machinery or a heavy reliance on CMOs, which may slow down the overall adoption rate of the newest technologies. Additionally, the complexity of customizing equipment for specific glass containers can lead to extended lead times and higher engineering costs.
Regulatory hurdles and the stringent validation processes required for pharmaceutical equipment also act as a restraint. Each piece of machinery must undergo rigorous IQ/OQ/PQ (Installation, Operational, and Performance Qualification) processes, which are time-consuming and labor-intensive. Any changes in international standards, such as updates to the EU GMP Annex 1, require manufacturers to undergo costly retrofitting or complete system overhauls. These factors, combined with the global shortage of specialized technical labor to operate and maintain high-tech machinery, create significant headwinds for market expansion.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Investment | -1.4% | Emerging Markets (LATAM, MEA) | 2025 - 2034 |
| Stringent Regulatory Validation Processes | -0.8% | Europe and North America | 2025 - 2030 |
| Complex Technical Maintenance Requirements | -0.5% | Global | 2026 - 2034 |
Glass Prefilled Syringes Glass Vials Packaging Equipment Market Opportunities Analysis
The emergence of flexible, multi-format filling lines represents a significant opportunity for equipment manufacturers. Traditionally, lines were dedicated to a single format (either vials or syringes). However, modern pharmaceutical manufacturing demands the ability to switch between different containers with minimal downtime and zero cross-contamination. Developing equipment that can handle vials, syringes, and cartridges on the same platform through rapid changeover kits is a high-growth area. This versatility is particularly attractive to CMOs who manage diverse product portfolios for multiple clients.
Furthermore, the integration of advanced digitalization and Data Integrity (DI) solutions offers a fertile ground for value-added services. Equipment providers can move beyond selling hardware to offering "Packaging-as-a-Service" or comprehensive life-cycle management contracts. Utilizing IoT sensors to monitor machine health in real-time and provide remote troubleshooting can significantly reduce unplanned downtime for pharma manufacturers. This digital transformation also aligns with the growing need for end-to-end traceability and serialization, providing opportunities for software integration and cybersecurity solutions within the packaging ecosystem.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | +1.8% | Germany, Italy, USA | 2025 - 2034 |
|---|---|---|---|---|---|
| Digitalization and Predictive Maintenance Services | +1.3% | Global | 2027 - 2034 | ||
| Expansion in Emerging Biotech Hubs | +1.1% | China, India, South Korea | 2025 - 2034 |
Glass Prefilled Syringes Glass Vials Packaging Equipment Market Challenges Impact Analysis
A major challenge facing the industry is the persistent disruption in global supply chains for specialized components like electronic controllers and high-grade stainless steel. These disruptions can lead to significant delays in equipment delivery, impacting the launch timelines of critical medications. Moreover, the increasing sophistication of cyber threats targets the industrial control systems of packaging lines, posing a risk to both operational continuity and sensitive manufacturing data. Ensuring robust cybersecurity without compromising machine performance is a delicate balance that manufacturers must maintain.
Additionally, the industry faces the challenge of adapting to the evolving landscape of drug delivery systems. The rise of large-volume injectors and wearable delivery devices requires packaging equipment that can handle non-standard glass dimensions and complex assembly processes. Traditional glass vial lines may not be easily adaptable to these new formats, necessitating continuous R&D investment. Finally, the pressure to reduce plastic waste in secondary packaging while maintaining the protective integrity of fragile glass components presents a design challenge that requires innovative material engineering and mechanical handling solutions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability for Key Components | -1.2% | Global | 2025 - 2027 |
| Cybersecurity Vulnerabilities in Connected Lines | -0.6% | North America and Europe | 2025 - 2034 |
| Rapid Evolution of Delivery Device Formats | -0.4% | Global | 2028 - 2034 |
Glass Prefilled Syringes Glass Vials Packaging Equipment Market - Updated Report Scope
The scope of this market research covers the entire value chain of packaging equipment specifically designed for glass primary containers in the pharmaceutical and biotechnology sectors. This includes primary packaging machinery such as washers, sterilizers, fillers, and closers, as well as secondary packaging equipment including labelers, cartoners, and case packers. The report provides a granular analysis of technological trends, such as the shift from RABS to isolator systems, and evaluates the impact of global healthcare policies on equipment procurement. It encompasses a comprehensive regional breakdown and identifies the key competitive strategies employed by market leaders to maintain their positions in a highly regulated and technically demanding environment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3,017.2 Million |
| Market Forecast in 2034 | USD 6,150.8 Million |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Syntegon (Bosch Packaging), IMA S.p.A, Marchesini Group, Optima Packaging Group, Bausch+Ströbel, Romaco Group, Körber AG, Coesia S.p.A, Groninger & Co. GmbH, MG2 S.r.l, Truking Technology, Tofflon Science and Technology, Dara Pharmaceutical Packaging, I.M.A. Industria Macchine Automatiche, NJM Packaging, SP Industries, AST (Automated Systems of Tacoma), Steriline, Colanar, PennTech Machinery. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Glass Prefilled Syringes and Glass Vials Packaging Equipment market reflects the diverse operational requirements of the global pharmaceutical industry. Machine type segmentation is dominated by filling and sealing equipment, which accounts for the largest revenue share due to the precision and sterility standards required. However, inspection systems are the fastest-growing sub-segment, as regulatory bodies increasingly demand 100% inspection of parenteral products to identify particulates or container integrity issues. By containment type, there is a clear migration toward isolator systems, which offer superior protection for both the product and the operator compared to traditional cleanroom environments.
- By Machine Type:
- Filling and Sealing Machines
- Washing and Sterilizing Tunnels
- Automatic Inspection Systems
- Labeling and Serialization Equipment
- Secondary Packaging (Cartoners and Case Packers)
- By Container Type:
- Glass Prefilled Syringes (PFS)
- Glass Vials
- Cartridges and Ampoules
- By Containment Technology:
- Isolator Technology
- Restricted Access Barrier Systems (RABS)
- Open Systems
- By End-User:
- Large Pharmaceutical Enterprises
- Biotechnology Firms
- Contract Manufacturing Organizations (CMOs)
- Academic and Research Institutes
Regional Highlights
- North America: The United States leads the world in pharmaceutical innovation, particularly in high-value biologics and cell therapies. The region boasts the largest concentration of R&D investment and a strict regulatory environment (FDA), which drives the early adoption of advanced packaging technologies like isolators and AI-driven inspection.
- Europe: This region is the global hub for packaging machinery manufacturing, with Germany and Italy hosting the majority of world-leading equipment providers. Europe is also at the forefront of sustainability initiatives, pushing for eco-friendly packaging processes and energy-efficient machinery designs.
- Asia Pacific: Characterized as the fastest-growing market, APAC is seeing massive investment in pharmaceutical infrastructure. Countries like China and India are transitioning from basic manufacturing to high-end drug production, resulting in a surge in demand for automated, high-speed filling lines to support global export requirements.
- Latin America: Growth is driven by the expansion of local pharmaceutical production and the increasing presence of multinational corporations establishing regional manufacturing hubs in Brazil and Mexico.
- Middle East and Africa: The market is emerging as governments focus on localizing drug production to ensure medical security. This is leading to initial investments in semi-automated and mid-range packaging equipment.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Glass Prefilled Syringes Glass Vials Packaging Equipment Market.- Syntegon Technology GmbH
- IMA S.p.A.
- Marchesini Group S.p.A.
- Optima Packaging Group GmbH
- Bausch+Ströbel Maschinenfabrik Ilshofen GmbH+Co. KG
- Körber AG
- Romaco Group
- Coesia S.p.A.
- Groninger & Co. GmbH
- MG2 S.r.l.
- Truking Technology Ltd.
- Tofflon Science and Technology Co., Ltd.
- Dara Pharmaceutical Packaging
- NJM Packaging (ProMach)
- SP Industries, Inc.
- AST (Automated Systems of Tacoma)
- Steriline S.r.l.
- Colanar
- PennTech Machinery Corporation
- Vanrx Pharmasystems (Cytiva)
Frequently Asked Questions
What is driving the transition from vials to prefilled syringes?
The transition is primarily driven by the need for enhanced patient safety, reduced medication errors, and the convenience of self-administration. Prefilled syringes provide a precise dose, eliminate the risk of cross-contamination from multi-dose vials, and reduce drug overfill requirements, which is particularly critical for expensive biological drugs.
How does EU GMP Annex 1 affect the packaging equipment market?
EU GMP Annex 1 provides stringent guidelines for aseptic processing and contamination control. This regulation has forced many manufacturers to upgrade their existing lines to include better barrier technologies (like isolators or RABS) and more robust environmental monitoring systems, thereby driving the demand for advanced, compliant packaging equipment.
What are the advantages of modular packaging lines?
Modular packaging lines allow pharmaceutical companies to handle multiple product formats (vials, syringes, cartridges) on a single platform with minimal changeover time. This flexibility is essential for handling small batches of specialized medicines and biologics, providing a higher return on investment and the ability to scale production as needed.
What role does automation play in pharmaceutical inspection?
Automation in inspection utilizes high-speed cameras and AI-based image processing to detect minute particulates, cracks in glass, and improper seal integrity. This eliminates human error associated with manual inspection, ensures 100% compliance with quality standards, and maintains high throughput in production lines.
Why is "Ready-to-Use" (RTU) glass packaging becoming popular?
RTU packaging comes pre-cleaned and pre-sterilized from the glass manufacturer, allowing pharmaceutical companies to bypass the washing and sterilization phases of the packaging line. This reduces the footprint of the manufacturing facility, lowers energy consumption, and simplifies the overall production process, making it highly attractive for biotech companies.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
