Glass Curtain Wall Market
Glass Curtain Wall Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711488 | Published On : November 03, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Glass Curtain Wall Market Size
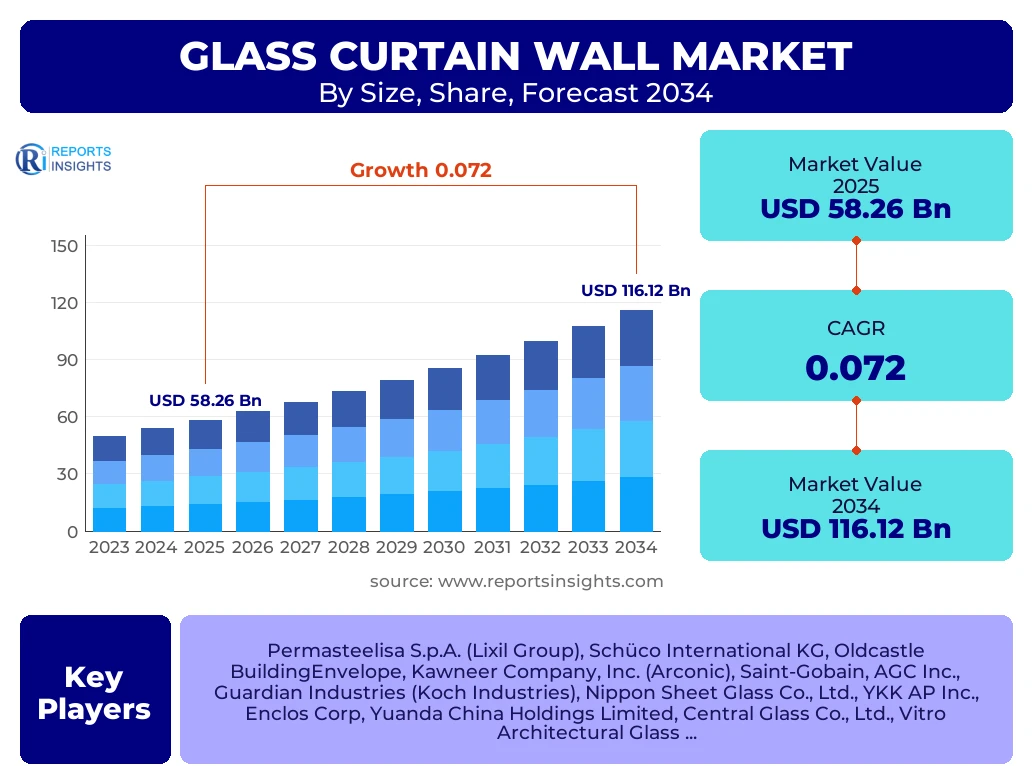
According to Reports Insights Consulting Pvt Ltd, The Glass Curtain Wall Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 62.45 Billion in 2026 and is projected to reach USD 116.12 Billion by the end of the forecast period in 2034.
Key Glass Curtain Wall Market Trends & Insights
The contemporary architectural landscape is undergoing a paradigm shift toward high-performance building envelopes that prioritize both aesthetic transparency and thermal efficiency. Current market dynamics are heavily influenced by the global transition toward Net-Zero Energy Buildings (NZEB), prompting a surge in demand for triple-glazed unitized systems and smart glass integration. Stakeholders are increasingly focusing on carbon footprint reduction, leading to the adoption of low-carbon glass and recycled aluminum frames. Regionally, the Asia-Pacific region maintains its dominance due to rapid urbanization, while North America and Europe are witnessing a significant uptick in the retrofitting of aging commercial structures with modern, energy-efficient curtain wall solutions.
- Largest Region: Asia-Pacific, driven by massive infrastructure projects in China, India, and Southeast Asia, currently holds over 40% of the global market share.
- Fastest Growing Region: The Middle East and Africa (MEA) region is exhibiting the highest growth rate, fueled by luxury real estate developments and diversification into non-oil sectors.
- Largest Segment by System: Unitized systems remain the largest segment due to their rapid installation capabilities and superior quality control in factory settings.
- Leading Glazing Segment: Double-glazed units dominate the market, though triple-glazing is gaining traction in colder climates and high-performance certifications.
Key Takeaways Glass Curtain Wall Market Size & Forecast
The trajectory of the Glass Curtain Wall Market is intrinsically linked to the evolution of building codes and the commercial real estate recovery post-2024. As metropolitan areas become denser, the vertical expansion of cities necessitates lightweight yet durable facade solutions. The market is transitioning from traditional stick-built applications to sophisticated, prefabricated unitized modules that reduce on-site labor costs and mitigate safety risks. Furthermore, the integration of Building Integrated Photovoltaics (BIPV) within curtain wall systems is emerging as a critical factor for developers aiming for LEED and BREEAM certifications.
- The global market value is set to nearly double over the next decade, reflecting a strong recovery in the commercial construction sector.
- China remains the single largest national market, accounting for a significant portion of the total APAC revenue.
- Technological advancements in vacuum-insulated glass (VIG) are expected to disrupt the traditional multi-pane market by offering thinner, more efficient alternatives.
- Sustainability mandates in the European Union are forcing manufacturers to adopt circular economy principles, focusing on the end-of-life recyclability of facade components.
- Rising raw material costs, particularly for aluminum and specialized glass, remain a primary concern for bottom-line margins across the value chain.
Glass Curtain Wall Market Drivers Analysis
The primary catalysts for market expansion involve a confluence of regulatory pressures and technological innovations. Governments worldwide are implementing stricter energy codes, such as the Energy Performance of Buildings Directive (EPBD) in Europe, which mandates the use of high-performance building envelopes to reduce heating and cooling loads. Additionally, the urbanization of emerging economies requires high-rise commercial spaces that utilize curtain walls for their structural efficiency and speed of assembly. The growing preference for daylighting in office environments to enhance occupant well-being also drives the demand for expansive glass surfaces.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Energy Efficiency Regulations | +2.4% | European Union, USA, Canada | 2025 - 2034 |
| Rapid Urbanization and High-rise Construction | +2.1% | China, India, Vietnam | 2025 - 2030 |
| Adoption of BIPV Systems | +1.5% | Germany, Japan, South Korea | 2027 - 2034 |
| Demand for Premium Commercial Office Space | +1.2% | UAE, Saudi Arabia, USA | 2025 - 2032 |
Glass Curtain Wall Market Restraints Analysis
Despite robust growth, the market faces significant headwinds from volatile raw material pricing and the high initial capital expenditure required for premium systems. The complexity of installation and the requirement for highly skilled labor can lead to project delays and increased costs. Furthermore, the inherent thermal bridges in traditional curtain wall designs can sometimes conflict with extremely stringent zero-carbon mandates if not addressed with expensive thermal break technologies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Installation and Maintenance Costs | -1.1% | Global | 2025 - 2034 |
| Volatility in Aluminum and Float Glass Prices | -0.9% | Global | 2025 - 2028 |
| Environmental Concerns regarding Glass Production | -0.5% | Europe, North America | 2026 - 2034 |
Glass Curtain Wall Market Opportunities Analysis
The market presents substantial opportunities in the retrofitting of existing building stock, particularly in mature economies where older glass facades lack modern thermal properties. The development of self-cleaning glass and anti-reflective coatings opens new niches in the luxury residential and high-end retail sectors. Additionally, the fusion of Internet of Things (IoT) sensors within curtain wall frames to monitor structural health and thermal performance represents a significant technological frontier for high-tech maintenance services.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Retrofitting of Aging Commercial Buildings | +1.8% | USA, UK, Germany, France | 2025 - 2034 |
| Expansion in Luxury Residential High-rises | +1.3% | UAE, Singapore, Australia | 2026 - 2032 |
| Smart Glass and Dynamic Glazing Integration | +1.6% | Japan, USA, Northern Europe | 2027 - 2034 |
Glass Curtain Wall Market Challenges Impact Analysis
Addressing the challenge of acoustic insulation in densely populated urban centers is becoming critical, as glass facades are often perceived as less effective than solid walls at blocking noise. Additionally, extreme weather events, including high-velocity winds and seismic activities, require increasingly complex engineering solutions that can inflate project costs. The logistical challenge of transporting large, fragile unitized panels to congested city sites also remains a significant operational hurdle for contractors.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Acoustic Insulation Requirements in Cities | -0.7% | Tokyo, New York, London | 2025 - 2034 |
| Stringent Seismic and Wind Load Standards | -0.8% | Japan, West Coast USA, Chile | 2025 - 2034 |
| Complexity in Supply Chain Logistics | -0.6% | Global Metropolitan Areas | 2025 - 2030 |
Glass Curtain Wall Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global glass curtain wall industry, detailing the technological shifts, regulatory landscapes, and competitive dynamics. It segments the market by system type, glazing type, and end-use application, providing granular data for both established and emerging markets. The study covers the entire value chain, from raw material suppliers to specialized installation contractors, offering a holistic view of the forces driving the industry forward through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 58.26 Billion |
| Market Forecast in 2034 | USD 116.12 Billion |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 258 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Permasteelisa S.p.A. (Lixil Group), Schüco International KG, Oldcastle BuildingEnvelope, Kawneer Company, Inc. (Arconic), Saint-Gobain, AGC Inc., Guardian Industries (Koch Industries), Nippon Sheet Glass Co., Ltd., YKK AP Inc., Enclos Corp, Yuanda China Holdings Limited, Central Glass Co., Ltd., Vitro Architectural Glass, Xinyi Glass Holdings Limited, China State Construction Development Holdings Limited, AVIC Sanxin Co., Ltd., Kalwall Corporation, Josef Gartner GmbH, Reynaers Aluminium |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The glass curtain wall market is segmented based on construction methodology and functional characteristics to provide a clear understanding of market preferences. The unitized system segment currently dominates the market due to its logistical advantages and quality assurance. As labor costs rise in developed nations, the move toward factory-assembled modules that can be quickly hung on building structures is accelerating. In contrast, stick-built systems remain prevalent in smaller-scale projects or where complex geometries require on-site customization. Furthermore, the segmentation by glazing type highlights a significant move toward double and triple glazing as building owners seek to optimize operational costs through better thermal insulation.
- By System Type:
- Unitized Systems (Largest market share)
- Stick-built Systems (Cost-effective for smaller projects)
- Semi-unitized Systems (Hybrid approach)
- By Glazing Type:
- Double Glazed (Industry standard)
- Triple Glazed (High-growth in cold climates)
- Single Glazed (Declining in modern commercial use)
- Monolithic and Laminated Glass
- By End-use Sector:
- Commercial Office Buildings (Dominant sector)
- Retail and Shopping Malls
- Institutional (Schools, Hospitals, Government)
- Residential (Luxury and High-density)
Regional Highlights
- Asia-Pacific: The region is the largest market, driven by the massive vertical expansion of cities like Shanghai, Mumbai, and Jakarta. China accounts for the lion's share of regional production and consumption.
- North America: A major market for retrofitting. The United States is seeing a surge in demand for energy-efficient glass facades to meet local "Green New Deal" style city mandates.
- Europe: The leader in technological innovation and sustainability standards. Countries like Germany and the UK are pioneers in triple-glazing and smart glass adoption.
- Middle East: Characterized by high-value, iconic skyscraper projects. The focus here is on advanced solar control coatings to mitigate extreme heat.
- Latin America & Africa: Emerging markets with growing commercial footprints in Brazil, Mexico, and South Africa, though growth is more sensitive to economic volatility.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Glass Curtain Wall Market.- Permasteelisa S.p.A.
- Schüco International KG
- Oldcastle BuildingEnvelope
- Kawneer Company, Inc. (Arconic)
- Saint-Gobain
- AGC Inc.
- Guardian Industries
- Nippon Sheet Glass Co., Ltd.
- YKK AP Inc.
- Enclos Corp
- Yuanda China Holdings Limited
- Central Glass Co., Ltd.
- Vitro Architectural Glass
- Xinyi Glass Holdings Limited
- China State Construction Development Holdings Limited
- AVIC Sanxin Co., Ltd.
- Kalwall Corporation
- Josef Gartner GmbH
- Reynaers Aluminium
- Alumil S.A.
Frequently Asked Questions
What is the difference between unitized and stick-built glass curtain walls?
Unitized systems are factory-assembled into large panels and shipped to the site for rapid installation using cranes, offering higher quality and faster timelines. Stick-built systems are assembled on-site piece-by-piece, which is more labor-intensive but allows for more flexibility in adjusting to building variations during construction.
How do glass curtain walls contribute to LEED and BREEAM certifications?
Curtain walls contribute by improving thermal performance, maximizing natural daylight, and utilizing low-emissivity (Low-E) coatings. Advanced systems may also incorporate recycled materials or photovoltaic cells, directly impacting the energy efficiency and sustainability categories of these green building certifications.
What are the primary factors driving the growth of the glass curtain wall market in Asia-Pacific?
The primary drivers include rapid urbanization, the proliferation of high-rise commercial and residential buildings, government investments in infrastructure, and a growing emphasis on modern architectural aesthetics in emerging economies like India and Southeast Asia.
What is the typical lifespan of a modern glass curtain wall system?
A well-maintained glass curtain wall system typically has a lifespan of 30 to 50 years. However, individual components like gaskets and sealants may require replacement every 15 to 25 years to maintain airtightness and water resistance.
How is smart glass technology being integrated into glass curtain walls?
Smart glass, or electrochromic glass, allows the building's facade to change its tint based on external light conditions or user preferences. This integration reduces the need for external shading devices and significantly lowers HVAC energy consumption by controlling solar heat gain.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
