Geosynthetics Market
Geosynthetics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711033 | Published On : September 30, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Geosynthetics Market Size
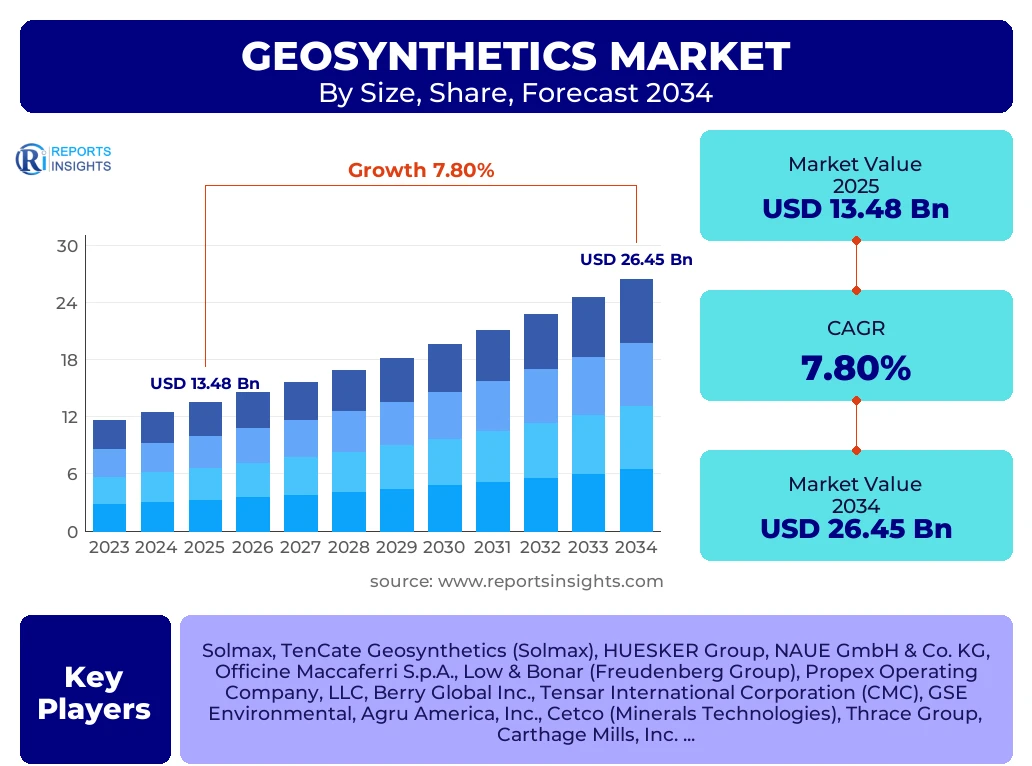
According to Reports Insights Consulting Pvt Ltd, The Geosynthetics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2026 and 2034. The market is estimated at USD 14.53 Billion in 2026 and is projected to reach USD 26.45 Billion by the end of the forecast period in 2034.
Key Geosynthetics Market Trends & Insights
The global geosynthetics market is undergoing a significant transformation driven by the integration of advanced material science and a global shift toward sustainable infrastructure. Current market trends indicate a move away from traditional soil stabilization methods toward polymer-based solutions that offer superior longevity and reduced environmental impact. Regional insights reveal that the Asia-Pacific region continues to dominate market volume, fueled by massive public sector investments in transportation and water management projects. Competitive benchmarking shows that market leaders are increasingly focusing on the development of "smart geosynthetics" embedded with fiber-optic sensors to monitor structural integrity in real-time. Furthermore, the industry is witnessing a surge in the use of recycled polyethylene and polypropylene resins to meet stringent green building certifications and circular economy mandates across Europe and North America.
- Largest Region: Asia-Pacific, holding over 40% of the total market share due to rapid urbanization in China and India.
- Fastest Growing Region: Southeast Asia and parts of Africa, where infrastructure deficits are being addressed through international developmental loans.
- Largest Segment by Type: Geotextiles, which account for the majority of the market value due to their versatile applications in filtration, drainage, and separation.
- Highest Growth Segment: Geomembranes, driven by strict environmental regulations regarding waste containment and groundwater protection.
- Key Material Trend: Shift toward high-density polyethylene (HDPE) and polypropylene (PP) for enhanced chemical resistance in mining and industrial applications.
Key Takeaways Geosynthetics Market Size & Forecast
The Geosynthetics market is entering a phase of high-value growth characterized by technical specialization and application-specific product development. Users and stakeholders are increasingly concerned with the total cost of ownership rather than just the initial procurement price, leading to a higher adoption of high-performance geocomposites and geogrids. Forecasts indicate that the road construction and maintenance sector will remain the primary consumer of geosynthetic materials, as governments prioritize resilient infrastructure that can withstand climate-related stressors. Additionally, the mining industry is emerging as a critical vertical, utilizing specialized geomembranes for heap leaching and tailing pond management to prevent hazardous runoff.
- The global market value is set to nearly double by 2034, reflecting the essential role of geosynthetics in modern civil engineering.
- China remains the leading country in both production and consumption, followed closely by the United States and Germany.
- Environmental containment applications, including landfill closures and wastewater treatment, are expected to see a CAGR of over 8% during the forecast period.
- Rising crude oil prices significantly impact the profit margins of manufacturers, as polymers are the primary raw materials.
- Innovation in bio-based and biodegradable geosynthetics for temporary erosion control is opening new niche markets in sensitive ecological zones.
Geosynthetics Market Drivers Analysis
The primary driver for the geosynthetics market is the global surge in infrastructure development, particularly in emerging economies where road networks, railways, and airports are being expanded at an unprecedented scale. Geosynthetics provide a cost-effective and durable alternative to traditional construction materials like aggregate and concrete, allowing for faster project completion and reduced maintenance cycles. Additionally, increasing environmental regulations regarding waste management and liquid containment are forcing industries to adopt high-standard lining systems, directly boosting the demand for geomembranes and geosynthetic clay liners.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Infrastructure Expansion | +3.2% | Global (Strongest in India/China) | 2025–2034 |
| Strict Environmental Regulations | +2.1% | Europe and North America | 2025–2030 |
| Mining Sector Modernization | +1.5% | Australia, Chile, and South Africa | 2026–2032 |
| Coastal Protection Projects | +1.0% | Low-lying Coastal Nations | 2027–2034 |
Geosynthetics Market Restraints Analysis
The geosynthetics market faces significant headwinds from the volatility of raw material prices, specifically petrochemical-derived resins like polyethylene and polypropylene. Since these materials constitute a large portion of the manufacturing cost, fluctuations in global oil prices can lead to unpredictable pricing for end-users. Furthermore, a lack of standardized testing protocols in some developing regions leads to the use of inferior quality products, which can cause project failures and damage the reputation of geosynthetic solutions. Additionally, the high level of technical expertise required for the proper installation of geomembranes and geocomposites limits adoption in markets where skilled labor is scarce.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -1.8% | Global | 2025–2034 |
| Lack of Skilled Installation Labor | -1.2% | Southeast Asia and Africa | 2025–2029 |
| Competition from Conventional Methods | -0.7% | Conservative Markets (Construction) | 2025–2028 |
Geosynthetics Market Opportunities Analysis
There is a massive opportunity for market players to develop "green" or sustainable geosynthetics made from recycled ocean plastics or bio-polymers, catering to the growing demand for carbon-neutral construction projects. As the world shifts toward renewable energy, the construction of offshore wind farms and large-scale solar arrays requires specialized geosynthetic solutions for subsea cable protection and soil stabilization. Moreover, the integration of IoT and sensor technology into geosynthetic fabrics offers a lucrative path for value-added services, allowing manufacturers to transition from product providers to structural health monitoring partners.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Sustainable/Bio-based Geosynthetics | +2.5% | EU and North America | 2026–2034 |
| Renewable Energy Infrastructure | +1.8% | UK, China, and USA | 2025–2034 |
| Smart Geosynthetics (IoT Integration) | +1.2% | Developed Economies | 2028–2034 |
Geosynthetics Market Challenges Impact Analysis
One of the most pressing challenges is the long product approval and certification cycles required by government transportation departments, which can delay the market entry of innovative materials. Additionally, the lack of awareness among project consultants and design engineers in certain regions regarding the long-term benefits of geosynthetics over traditional soil and aggregate methods remains a barrier. Ensuring consistent quality across global manufacturing sites while maintaining competitive pricing also poses a significant challenge for multinational corporations operating in diverse regulatory environments.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lengthy Certification Processes | -1.0% | USA and European Union | 2025–2034 |
| Resistance to Technological Change | -0.8% | Middle East and Latin America | 2025–2030 |
| Global Logistics & Supply Chain Disruption | -0.5% | International Trade Routes | 2025–2027 |
Geosynthetics Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis of the global geosynthetics industry, covering the historical period of 2020 to 2024 and providing detailed forecasts from 2026 to 2034. The scope encompasses a variety of material types, including geotextiles, geomembranes, geogrids, geonets, and geocomposites, analyzed across diverse applications such as road construction, waste management, mining, and water hydraulic structures. The report evaluates the impact of macroeconomic factors, technological advancements, and regulatory shifts on market dynamics, offering stakeholders a clear roadmap for investment and strategic planning. Detailed competitive profiling of the top 20 industry players is included to provide a clear view of the market's competitive landscape.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 13.48 Billion |
| Market Forecast in 2034 | USD 26.45 Billion |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 254 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Solmax, TenCate Geosynthetics (Solmax), HUESKER Group, NAUE GmbH & Co. KG, Officine Maccaferri S.p.A., Low & Bonar (Freudenberg Group), Propex Operating Company, LLC, Berry Global Inc., Tensar International Corporation (CMC), GSE Environmental, Agru America, Inc., Cetco (Minerals Technologies), Thrace Group, Carthage Mills, Inc., Fibertex Nonwovens A/S, Kaytech, Mattex, Hanes Geo Components, Leggett & Platt, Global Synthetics |
| Regions Covered | North America (USA, Canada, Mexico), Europe (Germany, UK, France, Russia, Italy), Asia Pacific (China, India, Japan, South Korea, Southeast Asia), Latin America (Brazil, Argentina, Colombia), Middle East and Africa (Saudi Arabia, UAE, South Africa, Nigeria) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The geosynthetics market is segmented based on product type, material composition, and end-use application, reflecting the technical complexity of the industry. Product-based segmentation is critical as different geosynthetics serve distinct functions such as separation, filtration, reinforcement, protection, or drainage. Geotextiles represent the largest segment due to their widespread use in almost every civil engineering project. Geogrids are witnessing high demand for soil stabilization in soft-soil areas, while geomembranes are indispensable for environmental protection in landfills and mining sites. The material-based segmentation highlights the dominance of synthetic polymers like polypropylene and polyethylene, which offer the chemical and physical durability required for long-term subsurface applications.
- By Product Type:
- Geotextiles: Divided into woven, non-woven, and knitted fabrics, widely used in road construction and filtration.
- Geomembranes: Low-permeability synthetic membrane liners used for liquid and solid waste containment.
- Geogrids: Used primarily for reinforcement to stabilize soil and aggregate in roads and retaining walls.
- Geocomposites: Combinations of two or more geosynthetic materials designed for specific multifunctional needs.
- Geosynthetic Clay Liners (GCL): Factory-manufactured hydraulic barriers consisting of bentonite clay between geotextiles.
- By Material:
- Polypropylene (PP): Preferred for its high strength-to-weight ratio and chemical resistance.
- Polyethylene (PE): Available in High-Density (HDPE) and Linear Low-Density (LLDPE) for lining and drainage applications.
- Polyester (PET): Utilized in high-load geogrids due to its creep resistance and high tensile modulus.
- Polyvinyl Chloride (PVC): Often used in flexible geomembranes for water storage and tunneling.
- By Application:
- Road & Pavement Construction: Largest application area, focusing on subgrade stabilization and asphalt reinforcement.
- Waste Management: Essential for landfill base liners and capping systems to prevent leachate migration.
- Mining: Used in heap leach pads and tailing dams to protect groundwater from toxic chemicals.
- Water Management: Includes canal linings, dam waterproofing, and reservoir protection.
Regional Highlights
- Asia-Pacific: The regional market leader, driven by the Chinese government’s "Belt and Road Initiative" and India’s massive "Bharatmala" highway project. The region accounts for the highest volume consumption of geotextiles and geogrids.
- North America: A mature market focused on the rehabilitation of aging infrastructure and strict EPA regulations for waste management. The US is a major hub for geomembrane innovation and high-performance geosynthetic applications in the shale gas industry.
- Europe: Driven by environmental sustainability and circular economy initiatives. European manufacturers are leading the way in producing geosynthetics with lower carbon footprints and higher recycled content.
- Middle East and Africa: Growing rapidly due to large-scale urban development projects (e.g., NEOM in Saudi Arabia) and the expansion of the mining sector in Sub-Saharan Africa.
- Latin America: The market is supported by mining activities in Chile and Peru, along with emerging infrastructure projects in Brazil and Mexico.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Geosynthetics Market.- Solmax
- TenCate Geosynthetics
- HUESKER Group
- NAUE GmbH & Co. KG
- Officine Maccaferri S.p.A.
- Low & Bonar (Freudenberg Group)
- Propex Operating Company, LLC
- Berry Global Inc.
- Tensar International Corporation (CMC)
- GSE Environmental
- Agru America, Inc.
- Cetco (Minerals Technologies)
- Thrace Group
- Carthage Mills, Inc.
- Fibertex Nonwovens A/S
- Kaytech
- Mattex
- Hanes Geo Components
- Leggett & Platt
- Global Synthetics
Frequently Asked Questions
What is the current market size of the global Geosynthetics market?
The global geosynthetics market is estimated to be valued at approximately USD 13.48 Billion in 2025 and is projected to reach USD 26.45 Billion by 2034, growing at a CAGR of 7.8%.
Which product segment dominates the Geosynthetics market?
Geotextiles represent the largest product segment due to their versatility in filtration, drainage, and soil separation across various civil engineering and construction applications.
Who are the leading players in the Geosynthetics industry?
Key market leaders include Solmax (including TenCate), HUESKER Group, NAUE, Officine Maccaferri, and Berry Global, who collectively hold a significant portion of the global market share.
What are the primary growth drivers for this market?
The primary drivers include increasing government investment in infrastructure, stringent environmental regulations for waste management, and the cost-efficiency of geosynthetics compared to traditional materials.
Which region is expected to grow the fastest during the forecast period?
Asia-Pacific is expected to be the fastest-growing region, fueled by large-scale infrastructure projects and rapid industrialization in countries like China, India, and Vietnam.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
