Genetic Testing Market
Genetic Testing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711779 | Published On : November 16, 2026 |
Format : 


 | Author : Jonathan Sikka
Genetic Testing Market Size
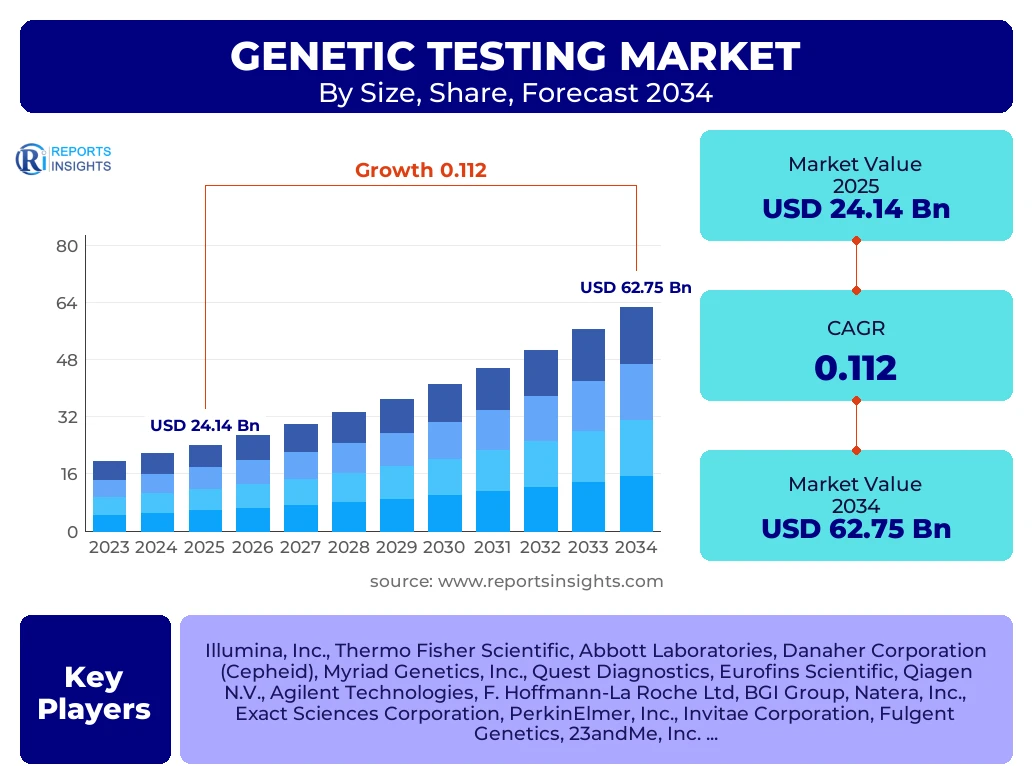
According to Reports Insights Consulting Pvt Ltd, The Genetic Testing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 11.2% between 2025 and 2034. The market is estimated at USD 26.84 Billion in 2026 and is projected to reach USD 62.75 Billion by the end of the forecast period in 2034.
Key Genetic Testing Market Trends & Insights
The global genetic testing landscape is currently defined by a paradigm shift toward precision medicine and the democratization of genomic data. Stakeholders are witnessing a transition from traditional reactive diagnostics to proactive, preventive health management. This evolution is driven by the significant reduction in the cost of Next-Generation Sequencing (NGS) and the integration of advanced bioinformatics that allow for the interpretation of complex genetic datasets. Market participants are increasingly focusing on oncology, specifically liquid biopsies, and non-invasive prenatal testing (NIPT), which offer high accuracy with minimal procedural risk. Furthermore, the convergence of artificial intelligence with genomics is streamlining variant interpretation, reducing the turnaround time for clinical reports and enhancing the scalability of genetic services across decentralized healthcare settings.
- Largest Region: North America remains the dominant market, holding over 42% of the global share due to high healthcare expenditure and early adoption of personalized medicine.
- Fastest Growing Region: Asia-Pacific is expected to exhibit the highest CAGR, fueled by improving genomic infrastructure in China and India and rising awareness of hereditary diseases.
- Largest Segment by Type: The Diagnostic Testing segment currently holds the largest revenue share, driven by the increasing prevalence of chronic diseases and the necessity for early clinical intervention.
- Emerging Technology Trend: Single-cell sequencing and spatial genomics are gaining traction in research environments, promising future clinical applications for complex heterogeneous tumors.
- Market Maturity: While developed markets focus on specialized rare disease panels, emerging markets are seeing high demand for newborn screening and basic carrier testing.
Key Takeaways Genetic Testing Market Size & Forecast
The long-term outlook for the genetic testing sector remains robust, supported by systemic shifts in reimbursement policies and the expansion of clinical applications beyond traditional oncology. As payers increasingly recognize the cost-benefit ratio of early genetic intervention—particularly in oncology and rare pediatric conditions—insurance coverage is expanding, thereby reducing out-of-pocket costs for patients. The forecast period will likely see a surge in the integration of pharmacogenomics into primary care, allowing physicians to tailor drug dosages based on individual genetic profiles, effectively reducing adverse drug reactions and improving therapeutic efficacy across global populations.
- The global market value is set to more than double by 2034, reflecting a fundamental integration of genetics into standard clinical workflows.
- Predictive and pre-symptomatic testing segments are anticipated to witness accelerated growth as consumer interest in wellness and preventative healthcare climbs.
- Direct-to-Consumer (DTC) genetic testing is evolving from ancestry-focused kits to health-risk assessment tools, though regulatory scrutiny remains a critical factor for market entry.
- Oncology applications account for approximately 35% of the market share, with hereditary cancer panels seeing the highest clinical uptake.
- Strategic collaborations between pharmaceutical companies and diagnostic labs are becoming the primary driver for companion diagnostic development.
Genetic Testing Market Drivers Analysis
The expansion of the genetic testing market is fundamentally underpinned by the rising global burden of chronic and genetic disorders. As the aging population grows, the incidence of cancer and cardiovascular diseases necessitates precise diagnostic tools that can guide targeted therapies. Additionally, technological advancements in sequencing platforms have drastically lowered the "per-genome" cost, making genetic insights accessible to a broader demographic and encouraging large-scale population genomics initiatives sponsored by various governments.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Next-Generation Sequencing (NGS) | +3.8% | Global (Strongest in US/Germany) | 2025 - 2034 |
| Increasing Prevalence of Rare Genetic Diseases | +2.5% | Europe and North America | 2025 - 2030 |
| Rising Demand for Personalized Medicine in Oncology | +3.2% | China, Japan, and USA | 2026 - 2034 |
| Growth in Prenatal and Newborn Screening Programs | +1.7% | India and Southeast Asia | 2025 - 2034 |
Genetic Testing Market Restraints Analysis
Despite the high growth potential, the market faces significant headwinds primarily related to the complex regulatory environment and ethical concerns. The lack of standardized clinical guidelines for interpreting genetic variants can lead to inconsistent results, creating skepticism among healthcare providers. Furthermore, the high cost of specialized genetic tests in developing regions, coupled with inadequate insurance coverage for certain preventive screens, remains a major barrier to universal adoption.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Specialized Genetic Equipment | -1.5% | Africa and Latin America | 2025 - 2028 |
| Stringent Regulatory Approval Processes (FDA/EMA) | -2.1% | United States and EU | 2025 - 2034 |
| Ethical and Data Privacy Concerns | -0.8% | Global (Impact on DTC) | 2026 - 2034 |
Genetic Testing Market Opportunities Analysis
The integration of pharmacogenomics into routine clinical practice presents a transformative opportunity for the market. By identifying how patients respond to specific medications based on their genetic makeup, healthcare providers can optimize treatment efficacy and safety. Additionally, the emergence of liquid biopsy as a non-invasive tool for early cancer detection and monitoring represents a high-growth vertical, potentially replacing traditional tissue biopsies in several oncological applications over the next decade.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Pharmacogenomics in Primary Care | +2.9% | UK, Canada, and USA | 2027 - 2034 |
| AI-Driven Genomic Data Interpretation | +2.4% | Israel, USA, and South Korea | 2026 - 2034 |
| Direct-to-Consumer (DTC) Health Risk Testing | +1.8% | Global (Emerging Markets Focus) | 2025 - 2032 |
Genetic Testing Market Challenges Impact Analysis
One of the most persistent challenges in the genetic testing market is the shortage of skilled genetic counselors and bioinformaticians capable of translating raw genomic data into actionable clinical insights. As the volume of data generated by NGS continues to scale, the bottleneck shifts from data generation to data interpretation. Additionally, regional disparities in healthcare infrastructure and the presence of localized data protection laws (such as GDPR) complicate the cross-border sharing of genomic datasets for collaborative research.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Bioinformaticians | -1.2% | Global | 2025 - 2034 |
| Interoperability of Genomic Databases | -1.0% | European Union and Japan | 2025 - 2030 |
| Varying Reimbursement Landscapes | -1.9% | Multi-regional | 2025 - 2034 |
Genetic Testing Market - Updated Report Scope
The scope of this report encompasses a detailed quantitative and qualitative analysis of the global genetic testing market, segmented by test type, technology, application, and end-user. It provides a comprehensive evaluation of the competitive landscape, identifying key strategic maneuvers such as mergers, acquisitions, and technological partnerships that are shaping the industry. The report also explores the influence of evolving regulatory frameworks and the impact of public-private genomic initiatives on market dynamics across six major geographical regions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 24.14 Billion |
| Market Forecast in 2034 | USD 62.75 Billion |
| Growth Rate | 11.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Illumina, Inc., Thermo Fisher Scientific, Abbott Laboratories, Danaher Corporation (Cepheid), Myriad Genetics, Inc., Quest Diagnostics, Eurofins Scientific, Qiagen N.V., Agilent Technologies, F. Hoffmann-La Roche Ltd, BGI Group, Natera, Inc., Exact Sciences Corporation, PerkinElmer, Inc., Invitae Corporation, Fulgent Genetics, 23andMe, Inc., PacBio (Pacific Biosciences), Oxford Nanopore Technologies |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The genetic testing market is segmented into several critical categories that reflect the diverse clinical and commercial applications of genomic science. The diagnostic segment remains the largest due to its vital role in identifying symptomatic patients, whereas the pharmacogenomics segment is identified as a high-growth area as pharmaceutical companies and clinicians seek to minimize adverse drug reactions. Technology-wise, NGS continues to gain share from PCR and Sanger sequencing due to its high-throughput capabilities and falling operational costs.
- By Type of Test: Diagnostic Testing, Predictive and Pre-symptomatic Testing, Carrier Testing, Prenatal and Newborn Screening, Pharmacogenomic Testing, Nutrigenomics.
- By Technology: Next-Generation Sequencing (NGS), Polymerase Chain Reaction (PCR), Microarrays, Sanger Sequencing, Fluorescence In Situ Hybridization (FISH).
- By Application: Oncology (Hereditary Cancer Panels, Somatic Mutation Testing), Rare Diseases, Cardiovascular Diseases, Neurological Disorders, Infectious Diseases.
- By End-User: Diagnostic Laboratories (Reference Labs), Hospitals and Specialty Clinics, Academic and Research Centers, Pharmaceutical and Biotechnology Companies.
Regional Highlights
- North America: Dominates the global market in terms of value, driven by an advanced clinical laboratory network, favorable reimbursement for genomic profiling, and a high concentration of leading market players.
- Asia-Pacific: Positioned as the fastest-growing region, with China and Japan leading investments in large-scale population health studies and an increasing middle-class population demanding better diagnostic access.
- Europe: Exhibits steady growth characterized by strong regulatory oversight and a focus on integrating genomics into public health systems, particularly in the UK, Germany, and France.
- Latin America & MEA: These regions represent emerging opportunities, with growth centered around infectious disease screening and newborn testing programs as healthcare infrastructure improves.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Genetic Testing Market.- Illumina, Inc.
- Thermo Fisher Scientific
- Abbott Laboratories
- Danaher Corporation
- Myriad Genetics, Inc.
- Quest Diagnostics
- Eurofins Scientific
- Qiagen N.V.
- Agilent Technologies
- F. Hoffmann-La Roche Ltd
- BGI Group
- Natera, Inc.
- Exact Sciences Corporation
- PerkinElmer, Inc.
- Invitae Corporation
- Fulgent Genetics
- 23andMe, Inc.
- Pacific Biosciences
- Oxford Nanopore Technologies
Frequently Asked Questions
What is the current market size and growth rate of the Genetic Testing market?
The Genetic Testing market is estimated to reach USD 26.84 Billion by 2026, growing at a CAGR of 11.2% to reach approximately USD 62.75 Billion by 2034.
Which technology segment is expected to lead the market?
Next-Generation Sequencing (NGS) is the leading technology segment due to its high-throughput nature, cost efficiency for multi-gene panels, and broad clinical utility across oncology and rare diseases.
What are the primary drivers for the Genetic Testing market growth?
The primary drivers include the rising incidence of cancer and rare genetic disorders, advancements in genomic sequencing technologies, and the increasing global shift toward personalized and precision medicine.
How does the regulatory environment impact the market?
The regulatory environment, led by bodies like the FDA and EMA, ensures clinical validity and safety but can act as a restraint due to the long and costly approval cycles required for new diagnostic tests.
Which region offers the most growth potential for stakeholders?
The Asia-Pacific region offers the highest growth potential due to rapid healthcare modernization, government support for genomic research, and an increasing awareness of genetic health among the expanding population.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
