Generic Pharmaceuticals Market
Generic Pharmaceuticals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711482 | Published On : November 03, 2026 |
Format : 


 | Author : Erika Grotto
Generic Pharmaceuticals Market Size
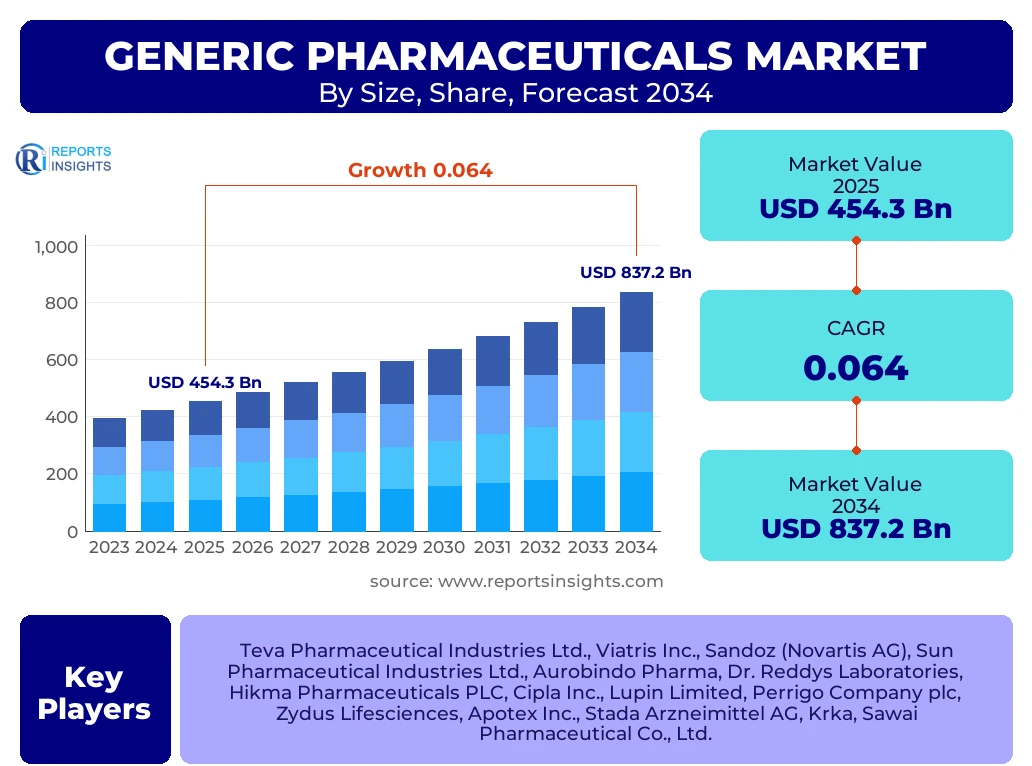
According to Reports Insights Consulting Pvt Ltd, The Generic Pharmaceuticals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 482.5 Billion in 2026 and is projected to reach USD 837.2 Billion by the end of the forecast period in 2034.
The global generic pharmaceuticals landscape is undergoing a significant transformation, driven by the dual pressures of healthcare cost containment and the expiration of patents for high-value biologic and synthetic drugs. As governments across North America, Europe, and Asia-Pacific seek to reduce the financial burden on public health systems, generic medications have emerged as a primary solution for maintaining patient access to essential treatments. The market is characterized by a shift from simple small-molecule generics toward complex generics and biosimilars, which require higher technical expertise and offer more sustainable profit margins for manufacturers.
The expansion of the generic drugs sector is also heavily influenced by the increasing prevalence of chronic diseases such as diabetes, cardiovascular conditions, and oncology. These therapeutic areas require long-term medication adherence, making affordable generic versions indispensable. Furthermore, the pharmaceutical supply chain is witnessing a structural realignment, with companies diversifying their active pharmaceutical ingredient (API) sourcing to mitigate risks identified during global disruptions. This evolution is fostering a more resilient and technologically advanced manufacturing ecosystem that supports the sustained growth projected through 2034.
Key Generic Pharmaceuticals Market Trends & Insights
The market is increasingly defined by the rise of specialty and complex generics, which offer a competitive advantage over traditional commodity generics. Manufacturers are investing heavily in research and development to produce difficult-to-make formulations, including long-acting injectables, transdermal patches, and inhalational products. This trend is a response to the saturation and intense price competition in the oral solids segment. Additionally, the digital transformation of manufacturing, often referred to as Pharma 4.0, is enabling producers to optimize yields and ensure more rigorous compliance with evolving regulatory standards across different jurisdictions.
- Largest Region: North America remains the largest market by value, primarily due to the high volume of prescription drug consumption and the established regulatory framework of the FDA’s Abbreviated New Drug Application (ANDA) process.
- Fastest-Growing Region: Asia-Pacific is the fastest-growing region, fueled by expanding healthcare infrastructure in India and China, coupled with supportive government policies aimed at increasing the penetration of low-cost medicines.
- Leading Segment by Type: Simple Generics currently hold the largest market share, but Complex Generics are exhibiting the highest growth rate due to higher barriers to entry and reduced competition.
- Dominant Therapeutic Area: Cardiovascular and CNS (Central Nervous System) diseases represent the largest therapeutic segments, while Oncology is seeing the most rapid genericization as major cancer therapies lose patent protection.
Key Takeaways Generic Pharmaceuticals Market Size & Forecast
The forecast period from 2025 to 2034 highlights a robust trajectory for the industry, where volume growth will be the primary driver despite ongoing price erosion in developed markets. Stakeholders are focusing on vertical integration—controlling the production from API to finished dosage—to protect margins. The integration of artificial intelligence in drug development and supply chain management is expected to further reduce time-to-market for new generic entries, ensuring that cost-effective alternatives are available immediately upon patent expiry of brand-name counterparts.
- The United States continues to be the most influential market globally, dictating pricing trends and quality standards that are often mirrored in other regions.
- Germany and Germany lead the European sector, characterized by a high adoption rate of generic substitutions in retail pharmacies.
- Patent Cliff Impact: Over USD 200 billion worth of branded drugs are expected to go off-patent by 2030, providing a massive pipeline for generic manufacturers.
- Biosimilars Integration: While distinct from traditional generics, the biosimilars market is increasingly intertwined with generic business strategies, representing the next frontier of high-value growth.
- Regulatory Harmonization: Efforts by organizations like the International Council for Harmonisation (ICH) are simplifying the cross-border approval process, allowing for more efficient global launches.
Generic Pharmaceuticals Market Drivers Analysis
The primary growth engine for the generic pharmaceuticals market is the relentless pressure on global healthcare budgets. As aging populations in developed nations increase the demand for chronic disease management, payers are mandating the use of generics to ensure system sustainability. This is complemented by the "Patent Cliff," where a significant number of blockbuster drugs are losing exclusivity, opening doors for rapid market entry by generic players who can offer these therapies at a fraction of the original cost.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Patent Expirations of Blockbuster Drugs | +2.1% | Global (US & EU focus) | 2025 - 2030 |
| Rising Prevalence of Chronic Diseases | +1.8% | Global | 2025 - 2034 |
| Government Incentives for Generic Substitution | +1.5% | Asia-Pacific & Latin America | 2026 - 2034 |
| Technological Advances in Manufacturing | +0.8% | North America & Europe | 2027 - 2034 |
Generic Pharmaceuticals Market Restraints Analysis
Despite the positive growth outlook, the market faces significant headwinds from intensified price competition and aggressive "pay-for-delay" litigation from brand-name manufacturers. Regulatory scrutiny is also intensifying, with agencies like the FDA and EMA increasing the frequency of facility inspections, particularly in offshore manufacturing hubs. Any compliance failure can lead to import bans or product recalls, which severely disrupt supply chains and damage corporate reputations.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory & Quality Compliance | -1.2% | India, China, & US | 2025 - 2034 |
| Price Erosion in Developed Markets | -0.9% | USA & Western Europe | 2025 - 2030 |
| High R&D Costs for Complex Generics | -0.5% | Global | 2026 - 2032 |
Generic Pharmaceuticals Market Opportunities Analysis
The move toward complex generics and specialty medicines offers the most lucrative opportunity for forward-thinking pharmaceutical companies. Unlike standard tablets, products like sterile injectables and respiratory medications have higher barriers to entry, which protects against the rapid price depreciation common in the commodity segment. Furthermore, the emerging middle class in developing economies represents a vast, untapped patient base that is increasingly demanding affordable healthcare solutions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Complex & Specialty Generics | +2.4% | USA, Japan, & Germany | 2026 - 2034 |
| Growth in Biosimilars Segment | +1.9% | Europe & South Korea | 2025 - 2034 |
| Untapped Markets in MEA and LATAM | +1.1% | Brazil, UAE, & South Africa | 2027 - 2034 |
Generic Pharmaceuticals Market Challenges Impact Analysis
One of the most persistent challenges is the volatility of the global supply chain for raw materials. The concentration of API manufacturing in a few geographic clusters makes the entire industry vulnerable to geopolitical tensions or environmental regulations in those specific areas. Additionally, the generic industry must navigate a complex web of intellectual property (IP) laws that vary significantly by country, often leading to prolonged legal battles that delay product launches and increase operational costs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability & API Sourcing | -1.0% | Global | 2025 - 2029 |
| Intellectual Property Litigation | -0.7% | United States & EU | 2025 - 2034 |
| Environmental & Sustainability Mandates | -0.4% | Europe & North America | 2028 - 2034 |
Generic Pharmaceuticals Market - Updated Report Scope
This report provides an exhaustive analysis of the generic pharmaceuticals sector, covering the full spectrum of product types, therapeutic categories, and distribution pathways. It integrates macroeconomic indicators with granular industry data to offer a 360-degree view of the market dynamics. The scope includes a detailed assessment of the competitive landscape, identifying the strategic moves of key players, from mergers and acquisitions to investments in advanced manufacturing technologies and sustainable practices.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 454.3 Billion |
| Market Forecast in 2034 | USD 837.2 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Teva Pharmaceutical Industries Ltd., Viatris Inc., Sandoz (Novartis AG), Sun Pharmaceutical Industries Ltd., Aurobindo Pharma, Dr. Reddys Laboratories, Hikma Pharmaceuticals PLC, Cipla Inc., Lupin Limited, Perrigo Company plc, Zydus Lifesciences, Apotex Inc., Stada Arzneimittel AG, Krka, Sawai Pharmaceutical Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Generic Pharmaceuticals Market reveals a diversifying landscape where traditional oral solids are being supplemented by more sophisticated delivery mechanisms. The "Product Type" segment is currently dominated by simple generics, but the "Complex Generics" sub-segment is witnessing the most aggressive R&D investment. In terms of "Route of Administration," the oral segment remains the most common due to patient preference and ease of manufacture, yet "Injectables" are gaining traction within hospital settings for critical care and oncology. The "Distribution Channel" analysis indicates a significant shift toward online pharmacies, accelerated by digital health trends and the increasing comfort of consumers with home-delivery healthcare services.
- By Product Type:
- Simple Generics (Standard tablets and capsules)
- Super Generics (Improved versions of existing drugs with better delivery)
- Complex Generics (Difficult-to-replicate formulations like inhalers or patches)
- By Therapeutic Area:
- Oncology (Fastest growing due to high costs of branded cancer drugs)
- Cardiovascular Diseases (Largest volume segment)
- Diabetes & Metabolic Disorders
- Central Nervous System (CNS)
- Infectious Diseases
- Respiratory Diseases
- By Route of Administration:
- Oral Solids & Liquids
- Parenteral/Injectables
- Topical Formulations
- Inhalational Agents
- By Distribution Channel:
- Hospital Pharmacies (Focus on high-value injectables)
- Retail Pharmacies (Mainstay for chronic disease medications)
- Online Pharmacies (Rapidly expanding consumer reach)
Regional Highlights
The regional distribution of the Generic Pharmaceuticals Market reflects a balance between established healthcare systems and emerging economic powerhouses. North America and Europe provide the stability and high-value opportunities, particularly in the realm of complex generics and biosimilars, where regulatory standards are the most stringent. Conversely, the Asia-Pacific region offers high-volume growth, driven by massive population bases and the "Make in India" and "China 2025" initiatives that prioritize domestic pharmaceutical production. Latin America and the Middle East are emerging as significant secondary markets, with Brazil and Saudi Arabia leading the way in adopting pro-generic policies to manage public health expenditures.
- North America (United States & Canada): The largest market by value. The US market is characterized by high generic substitution rates (over 90% of prescriptions) but faces ongoing challenges regarding pricing transparency and supply chain security.
- Europe (Germany, UK, France, Italy): A mature market with strong government-led generic programs. Germany is a key hub for generic R&D and manufacturing.
- Asia-Pacific (China, India, Japan, Australia): The fastest-growing region. India is the "pharmacy of the world," supplying a large portion of the global generic volume, while China is rapidly upgrading its quality standards to enter Western markets.
- Latin America (Brazil, Mexico): Significant potential for growth as healthcare coverage expands to lower-income segments of the population.
- Middle East & Africa: Increasing investment in local manufacturing facilities to reduce reliance on imports and improve drug security.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Generic Pharmaceuticals Market.- Teva Pharmaceutical Industries Ltd.
- Viatris Inc.
- Sandoz (A Novartis Division)
- Sun Pharmaceutical Industries Ltd.
- Aurobindo Pharma Limited
- Dr. Reddys Laboratories Ltd.
- Hikma Pharmaceuticals PLC
- Cipla Inc.
- Lupin Limited
- Perrigo Company plc
- Zydus Lifesciences Limited
- Apotex Inc.
- Stada Arzneimittel AG
- Krka, d. d., Novo mesto
- Sawai Pharmaceutical Co., Ltd.
- Amneal Pharmaceuticals, Inc.
- Glenmark Pharmaceuticals Limited
- Aspen Pharmacare Holdings Limited
- Fresenius Kabi AG
- Torrent Pharmaceuticals Ltd.
Frequently Asked Questions
What is driving the growth of the global Generic Pharmaceuticals Market through 2034?
The primary growth drivers include the upcoming "patent cliff" where numerous blockbuster drugs will lose exclusivity, the rising global prevalence of chronic diseases requiring long-term treatment, and government initiatives worldwide to reduce healthcare costs by promoting the use of affordable generic alternatives.
Which therapeutic area is expected to see the highest growth in the generic segment?
The Oncology segment is expected to witness the highest growth rate. As expensive branded biologics and targeted therapies for cancer lose patent protection, the entry of lower-cost generic and biosimilar versions is crucial for expanding patient access to life-saving treatments.
What are complex generics and why are they important for market stakeholders?
Complex generics involve drugs that are difficult to manufacture due to their formulation, route of delivery (like inhalers or injectables), or complex active ingredients. They are important because they have higher barriers to entry, which results in less competition and better profit margins compared to standard oral tablets.
How does the Asia-Pacific region compare to North America in terms of market dynamics?
North America is currently the largest market by value due to high drug prices and established healthcare infrastructure. However, Asia-Pacific is the fastest-growing region because of its massive population, increasing healthcare spending, and its role as a global hub for generic manufacturing and API production.
What are the biggest challenges facing generic pharmaceutical manufacturers today?
Key challenges include stringent and evolving regulatory requirements, significant price erosion in highly competitive markets, supply chain vulnerabilities for raw materials, and prolonged intellectual property litigation from brand-name drug manufacturers seeking to delay generic entry.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
