Gastroenterology Ambulatory Surgery Center Market
Gastroenterology Ambulatory Surgery Center Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711070 | Published On : October 03, 2026 |
Format : 


 | Author : Erika Grotto
Gastroenterology Ambulatory Surgery Center Market Size
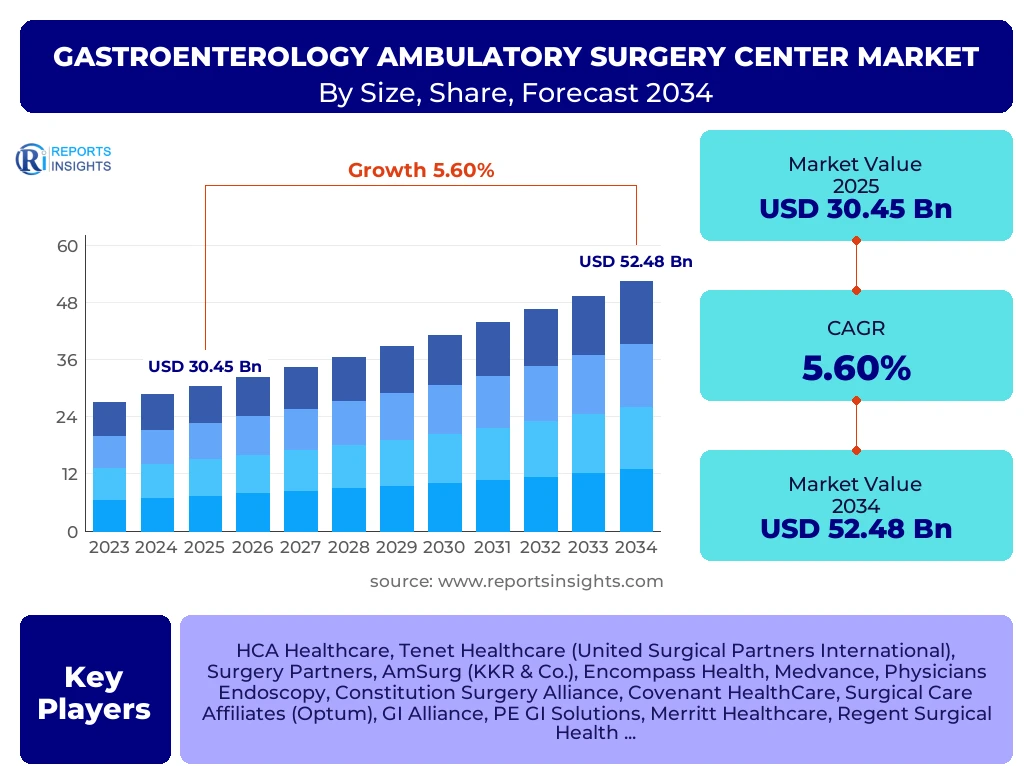
According to Reports Insights Consulting Pvt Ltd, The Gastroenterology Ambulatory Surgery Center Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.6% between 2026 and 2034. The market is estimated at USD 32.15 Billion in 2026 and is projected to reach USD 52.48 Billion by the end of the forecast period in 2034.
Key Gastroenterology Ambulatory Surgery Center Market Trends & Insights
The global Gastroenterology (GI) Ambulatory Surgery Center (ASC) market is undergoing a significant transformation driven by the migration of high-volume procedures from inpatient hospital settings to specialized outpatient facilities. Market analysis indicates that cost-efficiency, improved patient outcomes, and advancements in endoscopic technologies are the primary catalysts for this shift. Payers, including government programs and private insurers, are increasingly incentivizing the use of ASCs for routine screenings such as colonoscopies and diagnostic endoscopies due to their lower overhead costs compared to traditional hospitals. Furthermore, the integration of Artificial Intelligence (AI) for real-time lesion detection during colonoscopies is enhancing diagnostic accuracy, thereby increasing the value proposition of specialized GI centers.
- Largest Region: North America currently holds the largest market share, driven by a well-established ASC infrastructure and favorable reimbursement policies.
- Fastest Growing Region: Asia-Pacific is anticipated to be the fastest-growing region due to increasing healthcare expenditure and the rising prevalence of gastrointestinal disorders in emerging economies.
- Largest Segment: The physician-owned ASC segment remains the largest in terms of market share, offering clinicians greater autonomy and financial participation.
- Technological Trend: The adoption of Computer-Aided Detection (CADe) systems and high-definition visualization tools is becoming a standard in modern gastroenterology centers.
Key Takeaways Gastroenterology Ambulatory Surgery Center Market Size & Forecast
The forecast for the Gastroenterology ASC market remains robust, reflecting a fundamental change in the healthcare delivery model. Stakeholders are focusing on geographic expansion and service diversification to capture a larger share of the growing volume of colorectal cancer screenings. The market is also seeing a trend toward corporate-physician partnerships, where large healthcare management firms provide the capital and administrative expertise while physicians maintain clinical oversight. This synergy is expected to drive operational efficiency and market consolidation through 2034.
- Leading Country: The United States leads the global market, accounting for a significant portion of the total ASC procedure volume worldwide.
- Demographic Impact: The aging global population is a primary driver, as the risk of GI cancers and digestive disorders increases significantly with age.
- Regulatory Support: Ongoing updates to the Centers for Medicare and Medicaid Services (CMS) Outpatient Prospective Payment System (OPPS) continue to support the expansion of the ASC procedure list.
- Strategic Consolidation: Increased Private Equity (PE) investment in GI practices is accelerating the growth of multi-site ASC networks.
Gastroenterology Ambulatory Surgery Center Market Drivers Analysis
Market drivers for Gastroenterology ASCs are centered on the trifecta of cost, convenience, and clinical advancement. As the global healthcare burden increases, outpatient centers offer a sustainable alternative to hospital-based care without compromising safety. The rising awareness of colorectal cancer screening programs worldwide has significantly increased the demand for colonoscopies, which are ideally suited for the ASC environment.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift from Inpatient to Outpatient Care | +1.8% | Global (High in North America) | 2025 - 2034 |
| Rising Incidence of Colorectal Cancer | +1.5% | Global | 2025 - 2034 |
| Technological Advancements in Endoscopy | +1.2% | Developed Markets | 2026 - 2030 |
| Favorable Reimbursement Landscape | +1.1% | United States / Germany | 2025 - 2034 |
Gastroenterology Ambulatory Surgery Center Market Restraints Analysis
Despite strong growth prospects, the market faces constraints related to high initial capital requirements and stringent regulatory compliance. The cost of state-of-the-art endoscopic equipment and the need for specialized sterilization facilities can be prohibitive for independent practitioners looking to establish new centers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Setup Costs | -0.8% | Emerging Markets | 2025 - 2028 |
| Shortage of Specialized GI Professionals | -0.6% | Global | 2025 - 2034 |
| Regulatory Hurdles and Licensing | -0.4% | European Union | 2025 - 2030 |
Gastroenterology Ambulatory Surgery Center Market Opportunities Analysis
The integration of digital health and telehealth services within the ASC workflow presents a massive opportunity for market players. Pre-operative consultations and post-operative follow-ups conducted virtually can significantly improve patient throughput and satisfaction. Furthermore, expansion into untapped markets in the APAC region offers a long-term growth runway.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Digital Health & AI Integration | +1.4% | United Kingdom / USA | 2027 - 2034 |
| Expansion in Emerging Economies | +1.2% | China / India / Brazil | 2028 - 2034 |
| Value-Based Care Partnerships | +0.9% | North America | 2026 - 2034 |
Gastroenterology Ambulatory Surgery Center Market Challenges Impact Analysis
Maintaining profitability in an environment of fluctuating reimbursement rates and increasing competition is a primary challenge. ASCs must also navigate evolving patient expectations regarding the use of non-invasive screening alternatives, which could potentially divert some volume away from traditional colonoscopies.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Reimbursement Volatility | -0.7% | United States | 2025 - 2034 |
| Competition from Non-Invasive Tests | -0.5% | Global | 2026 - 2034 |
Gastroenterology Ambulatory Surgery Center Market - Updated Report Scope
The updated report scope provides a comprehensive analysis of the gastroenterology ASC ecosystem, covering ownership models, procedure types, and geographic performance. It incorporates the latest data on procedure volumes, pricing trends, and the impact of recent healthcare policy changes on ASC profitability. The report serves as a strategic roadmap for investors, hospital administrators, and medical device manufacturers looking to capitalize on the outpatient gastroenterology trend.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 30.45 Billion |
| Market Forecast in 2034 | USD 52.48 Billion |
| Growth Rate | 5.6% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | HCA Healthcare, Tenet Healthcare (United Surgical Partners International), Surgery Partners, AmSurg (KKR & Co.), Encompass Health, Medvance, Physicians Endoscopy, Constitution Surgery Alliance, Covenant HealthCare, Surgical Care Affiliates (Optum), GI Alliance, PE GI Solutions, Merritt Healthcare, Regent Surgical Health, Medical Facilities Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Gastroenterology ASC market is categorized by ownership, procedure type, and service level. The physician-owned model continues to be the dominant segment because it aligns the financial incentives of the surgeons with the operational efficiency of the facility. However, the corporate-owned segment is seeing rapid growth as investment firms consolidate independent practices into larger, more efficient networks. Procedural segmentation shows that colonoscopies represent the highest volume of cases, followed by upper GI endoscopies. Emerging segments include specialized biliary and pancreatic procedures that are increasingly being performed in high-acuity ASCs.
- By Ownership Type: Includes Physician-owned facilities, Hospital-owned facilities, and Corporate/Private Equity-owned facilities. The joint venture model is increasingly popular for risk-sharing.
- By Procedure Category: Focuses on Colonoscopy, Esophagogastroduodenoscopy (EGD), Polypectomy, and complex procedures like ERCP performed in advanced outpatient settings.
- By Equipment Used: Analyzes the market based on the adoption of High-Definition endoscopes, AI-assisted diagnostic tools, and therapeutic GI devices.
- By Patient Demographics: Segments data based on pediatric, adult, and geriatric gastroenterology volumes.
Regional Highlights
- North America: Dominates the market due to the high density of ASCs, particularly in the United States. The shift is supported by CMS policies that favor lower-cost settings for diagnostic procedures.
- Europe: Witnessing steady growth as public health systems in countries like the UK and Germany look to reduce hospital waiting lists by utilizing private outpatient surgery centers.
- Asia-Pacific: The fastest-growing region, driven by the expansion of private healthcare infrastructure in China, India, and Southeast Asia, coupled with a rising middle class seeking quality preventive care.
- Latin America: Growth is concentrated in urban centers of Brazil and Mexico, where private healthcare insurance penetration is increasing.
- Middle East & Africa: Developing markets with significant potential in the UAE and Saudi Arabia as they invest heavily in medical cities and outpatient clinics.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Gastroenterology Ambulatory Surgery Center Market.- HCA Healthcare
- Tenet Healthcare (United Surgical Partners International)
- Surgery Partners
- AmSurg (Division of Envision Healthcare)
- Surgical Care Affiliates (Optum / UnitedHealth Group)
- GI Alliance
- Physicians Endoscopy (PE GI Solutions)
- Encompass Health
- Constitution Surgery Alliance
- Regent Surgical Health
- Merritt Healthcare
- Covenant Physician Partners
- Medical Facilities Corporation
- Nobilis Health Corp
- ValueHealth
Frequently Asked Questions
What is driving the growth of the Gastroenterology ASC market?
The growth is primarily driven by the migration of GI procedures from hospitals to outpatient settings to reduce costs, the aging global population requiring more screenings, and technological advancements that make outpatient endoscopy safer and more accurate.
Which procedure is most commonly performed in Gastroenterology ASCs?
Colonoscopy remains the most common procedure performed in these centers, accounting for a significant majority of the volume due to national colorectal cancer screening mandates and its effectiveness as a preventive measure.
How do reimbursement rates affect ASC operations?
ASCs typically receive lower reimbursement rates than hospital outpatient departments (HOPDs) for the same procedure. However, their lower overhead costs and higher efficiency allow them to remain profitable, though they are sensitive to changes in CMS and private insurer fee schedules.
What is the role of Private Equity in the GI ASC market?
Private Equity firms are actively consolidating independent gastroenterology practices and ASCs to create regional networks. This provides physicians with capital for technology upgrades and administrative support while allowing the PE firms to benefit from economies of scale.
Are ASCs as safe as hospitals for gastroenterology procedures?
Yes, studies consistently show that ASCs provide a high level of safety for gastrointestinal procedures. They are subject to rigorous state and federal regulations, and their specialized focus often leads to lower infection rates and high patient satisfaction scores.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted