Frame Grabber Market
Frame Grabber Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710922 | Published On : September 18, 2026 |
Format : 


 | Author : Shamin Verma
Frame Grabber Market Size
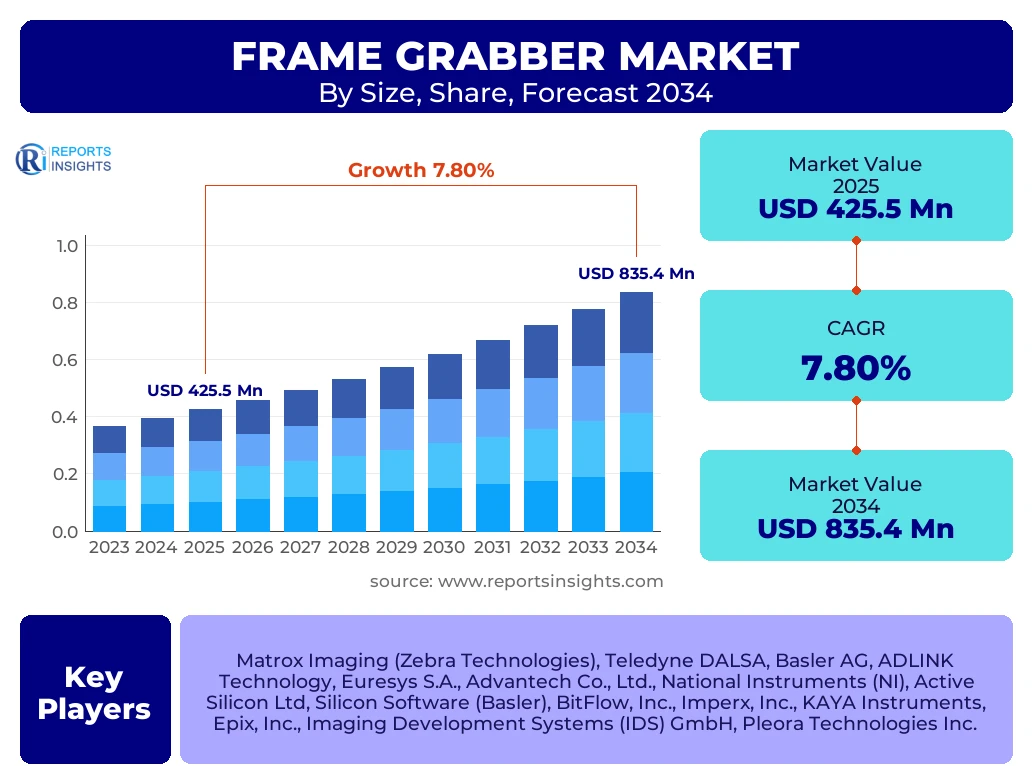
According to Reports Insights Consulting Pvt Ltd, The Frame Grabber Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2026 and 2034. The market is estimated at USD 458.7 Million in 2026 and is projected to reach USD 835.4 Million by the end of the forecast period in 2034.
Key Frame Grabber Market Trends & Insights
The global Frame Grabber market is undergoing a significant transformation driven by the rapid evolution of machine vision systems and the increasing demand for high-resolution, high-speed data acquisition in industrial automation. Historically, frame grabbers were simple hardware interfaces; however, modern iterations have evolved into sophisticated processing units equipped with on-board FPGAs (Field Programmable Gate Arrays) that allow for real-time image pre-processing. This shift is primarily fueled by the rise of Industry 4.0, where high-speed manufacturing lines require instantaneous defect detection and quality assurance. Regional insights indicate that while North America remains a powerhouse for high-end aerospace and defense applications, the Asia-Pacific region is experiencing the fastest growth due to the massive expansion of semiconductor and electronics manufacturing hubs. Competitive benchmarking reveals a strategic move among top-tier players to provide multi-protocol support, ensuring compatibility with various standards like CoaXPress 2.0 and Camera Link HS to cater to a diverse range of high-bandwidth industrial cameras.
- Largest Region: North America holds the largest market share due to early adoption of advanced automation and a robust presence of key aerospace and medical imaging industries.
- Fastest Growing Region: Asia-Pacific is the fastest-growing market, propelled by rapid industrialization in China, India, and South Korea, and the relocation of manufacturing facilities to these cost-effective hubs.
- Leading Interface Segment: CoaXPress (CXP) is emerging as the fastest-growing segment in terms of share, owing to its ability to handle extremely high data rates over long cable lengths.
- Dominant Application Segment: Industrial and Manufacturing continues to be the largest end-user segment, driven by the need for automated optical inspection (AOI) in high-throughput environments.
Key Takeaways Frame Grabber Market Size & Forecast
The Frame Grabber market is characterized by a transition toward high-speed digital interfaces and edge computing capabilities. Users frequently inquire about the longevity of the Camera Link standard versus the rising dominance of CoaXPress and GigE Vision. Current analysis suggests that while legacy systems still rely on Camera Link, the future belongs to CoaXPress 2.0 due to its scalability and throughput. The forecast indicates that the integration of Artificial Intelligence (AI) and Machine Learning (ML) directly into the frame grabber hardware will become a standard requirement, reducing the processing load on host CPUs and minimizing system latency. This evolution is crucial for applications such as autonomous vehicles, high-speed pharmaceutical packaging, and advanced medical diagnostics where real-time accuracy is non-negotiable.
- Market Valuation: The total market value is set to nearly double by 2034, reflecting the indispensable nature of frame grabbers in high-end imaging chains.
- Technological Shift: There is a clear migration from analog and low-speed digital interfaces to high-bandwidth standards like Camera Link HS and CoaXPress 12.
- US Leadership: The United States remains the leading country in technological innovation, particularly in the development of specialized frame grabbers for military and space exploration.
- Medical Expansion: The medical imaging sector is a critical secondary driver, with frame grabbers facilitating high-resolution video capture for robotic surgery and diagnostic equipment.
Frame Grabber Market Drivers Analysis
The primary drivers of the Frame Grabber market include the burgeoning demand for high-speed automated inspection in the electronics industry and the increasing complexity of image data that requires dedicated hardware for acquisition. As manufacturing speeds increase, standard PC buses often struggle with the raw data volume from high-resolution cameras, making frame grabbers essential for maintaining system stability and data integrity. Furthermore, the push for non-destructive testing (NDT) in the automotive and aerospace sectors relies heavily on the precision offered by these devices.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Industry 4.0 and Smart Manufacturing | +2.5% | Global (Strongest in Germany, China) | 2025 - 2034 |
| Adoption of CoaXPress 2.0 Standard | +1.8% | North America, Japan | 2025 - 2030 |
| Demand for 3D Machine Vision | +1.4% | Europe, United States | 2026 - 2034 |
| Rising Robotic Surgery Integration | +1.1% | North America, Western Europe | 2025 - 2034 |
Frame Grabber Market Restraints Analysis
Despite strong growth, the market faces restraints such as the rising performance of embedded vision systems and the increasing capabilities of direct-to-PC interfaces like USB 3.1 and 10 GigE Vision. For less demanding applications, these alternative interfaces offer a lower-cost solution that bypasses the need for a dedicated frame grabber card, thereby cannibalizing the lower end of the market. Additionally, high initial setup costs and the complexity of integrating frame grabbers into existing software architectures can deter small and medium-sized enterprises (SMEs).
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Direct-Connect Interfaces | -1.2% | Global | 2025 - 2034 |
| High Hardware Acquisition Costs | -0.8% | Emerging Markets (India, SE Asia) | 2025 - 2028 |
Frame Grabber Market Opportunities Analysis
Significant opportunities lie in the development of AI-enabled frame grabbers that can perform complex image analysis tasks locally. This edge-processing capability is highly attractive for autonomous robotics and real-time surveillance where latency must be kept to an absolute minimum. Moreover, the expansion of high-speed rail and transportation monitoring systems presents a niche but high-value opportunity for ruggedized frame grabbers designed to operate in harsh environmental conditions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of FPGA-based AI Accelerators | +2.2% | United States, South Korea, Israel | 2026 - 2034 |
| Hyperspectral Imaging in Agriculture | +1.0% | Brazil, United States, Australia | 2027 - 2034 |
Frame Grabber Market Challenges Impact Analysis
A major challenge for manufacturers is the rapid pace of standard updates, requiring constant R&D investment to remain compatible with the latest sensor technologies. There is also the challenge of global supply chain volatility, which affects the availability of high-performance FPGAs and specialized semiconductor components required for frame grabber assembly. Ensuring backward compatibility while pushing the boundaries of bandwidth remains a technical hurdle for many engineering teams.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Volatility for High-End Chips | -0.9% | Global | 2025 - 2027 |
| Interoperability Issues Between Vendors | -0.5% | Europe, Asia | 2025 - 2030 |
Frame Grabber Market - Updated Report Scope
The scope of this report encompasses a thorough analysis of the hardware, software, and service components of the Frame Grabber market. It provides a granular breakdown by interface type, number of ports, and end-user industries, offering a 360-degree view of the competitive landscape and technological roadmap. The study covers both standard PC-based frame grabbers and specialized embedded modules used in mobile and defense applications, ensuring all market facets are evaluated for the forecast period between 2026 and 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 425.5 Million |
| Market Forecast in 2034 | USD 835.4 Million |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Matrox Imaging (Zebra Technologies), Teledyne DALSA, Basler AG, ADLINK Technology, Euresys S.A., Advantech Co., Ltd., National Instruments (NI), Active Silicon Ltd, Silicon Software (Basler), BitFlow, Inc., Imperx, Inc., KAYA Instruments, Epix, Inc., Imaging Development Systems (IDS) GmbH, Pleora Technologies Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Frame Grabber market is segmented primarily by interface technology, which dictates the bandwidth and distance capabilities of the system. Camera Link remains a staple for medium-bandwidth applications due to its deterministic nature and widespread industry adoption. However, CoaXPress is rapidly gaining ground in the ultra-high-speed segment, particularly in semiconductor inspection where 12 Gbps per cable is becoming the benchmark. GigE Vision frame grabbers are favored for long-distance transmissions and cost-effective multi-camera setups, leveraging existing Ethernet infrastructure. Each segment is further categorized by the number of ports, ranging from single-port cards for basic inspection to quad-port and octal-port boards designed for complex, synchronized multi-angle imaging systems.
- By Interface Type:
- Camera Link: Includes Base, Medium, Full, and Deca configurations; widely used in legacy industrial systems.
- CoaXPress (CXP): CXP-6 and CXP-12 versions providing high-speed data transfer over coaxial cables.
- GigE Vision: Optimized for high-speed Ethernet-based data transfer over long distances.
- USB 3.0/3.1: Used primarily in low-to-medium performance applications where ease of use is paramount.
- Analog: Shrinking segment used for legacy medical and surveillance equipment.
- By End-User Vertical:
- Manufacturing/Industrial: Automated Optical Inspection (AOI), pick-and-place, and robotic guidance.
- Healthcare & Life Sciences: MRI, CT scans, and high-speed dental imaging.
- Aerospace & Defense: Target acquisition, aerial reconnaissance, and satellite imaging.
- Scientific Research: High-speed physics experiments and microscopy.
Regional Highlights
North America currently leads the market, driven by intense R&D activities and the high concentration of technology providers in the United States and Canada. The region benefits from a mature industrial base that early-adopted machine vision for automotive and defense manufacturing. Meanwhile, Europe maintains a strong second position, with Germany serving as a hub for high-precision engineering and the development of Industry 4.0 standards. The European market is characterized by a high demand for specialized frame grabbers used in pharmaceuticals and automotive safety testing.
- North America: Largest market share; focus on high-reliability frame grabbers for military and medical sectors.
- Asia-Pacific: Fastest CAGR; driven by the semiconductor boom in Taiwan and massive consumer electronics production in China and Vietnam.
- Europe: Leading in the adoption of industrial standards and high-speed manufacturing automation.
- Rest of the World: Emerging demand in Latin America and the Middle East for security, surveillance, and mining automation.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Frame Grabber Market.- Matrox Imaging (Zebra Technologies)
- Teledyne DALSA
- Basler AG
- ADLINK Technology Inc.
- Euresys S.A.
- Advantech Co., Ltd.
- National Instruments (NI)
- Active Silicon Ltd
- Silicon Software GmbH
- BitFlow, Inc.
- Imperx, Inc.
- KAYA Instruments
- Epix, Inc.
- Imaging Development Systems (IDS) GmbH
- Pleora Technologies Inc.
- The Imaging Source Europe GmbH
- Aval Data Corporation
- Argo Corp.
Frequently Asked Questions
What is a Frame Grabber and why is it used in modern machine vision?
A frame grabber is a specialized electronic device that captures individual, digital still frames from an analog video signal or a digital video stream. In modern machine vision, they are used to offload data processing from the host computer, ensure deterministic data delivery, and support high-bandwidth cameras that exceed standard PC interface limits.
Which interface is currently dominating the high-speed Frame Grabber market?
CoaXPress (CXP), specifically the CXP-12 standard, is currently dominating the high-speed segment. It offers up to 12.5 Gbps per cable and is favored for its long cable lengths, high reliability, and ability to provide power over the cable (PoCXP).
How is AI influencing the development of new Frame Grabber hardware?
AI is leading to the development of AI-enabled frame grabbers that feature on-board FPGAs or specialized processors. These devices can perform real-time image classification, object detection, and data reduction before the information even reaches the main system memory, significantly reducing latency.
Will GigE Vision eventually replace dedicated Frame Grabbers?
While GigE Vision is popular for many applications due to its cost-effectiveness, it often introduces higher CPU overhead and jitter compared to dedicated frame grabbers. For mission-critical, high-speed, and low-latency applications, dedicated frame grabbers remain the preferred choice.
What are the key industries driving the growth of this market through 2034?
The primary growth drivers are the semiconductor and electronics manufacturing industries, followed by the automotive sector (especially for EV battery inspection), medical imaging for robotic-assisted surgery, and the aerospace and defense sector for high-resolution surveillance.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted