Flame Retardant Thermoplastics Market
Flame Retardant Thermoplastics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711227 | Published On : October 19, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Flame Retardant Thermoplastics Market Size
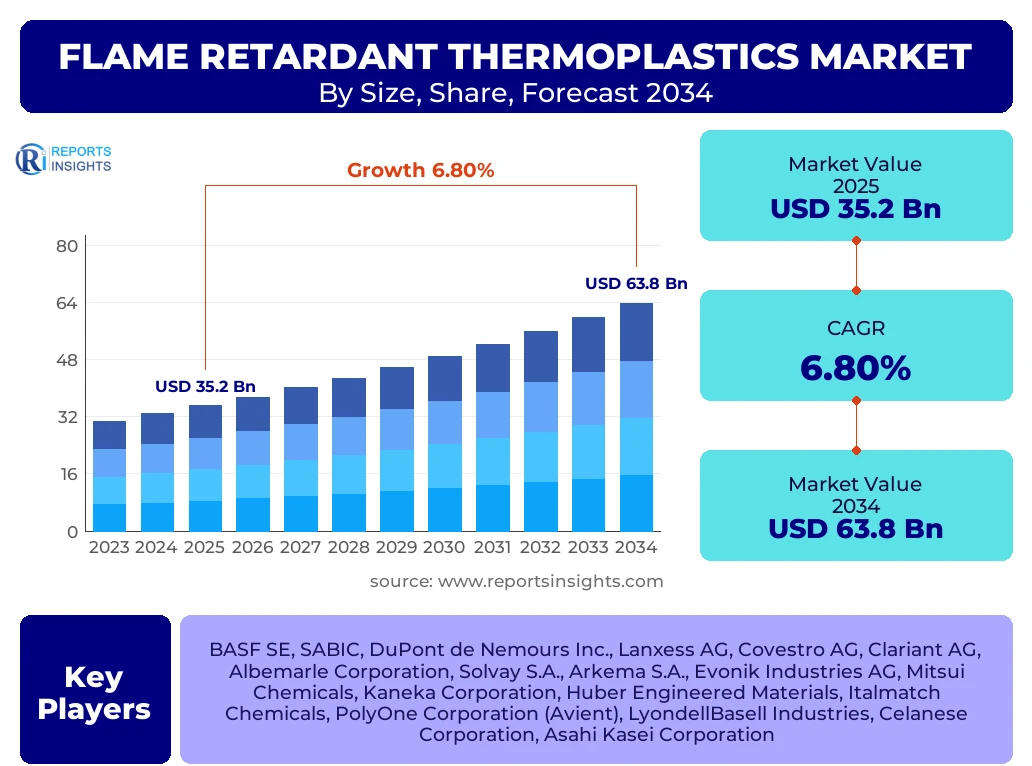
According to Reports Insights Consulting Pvt Ltd, The Flame Retardant Thermoplastics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 37.6 Billion in 2026 and is projected to reach USD 63.8 Billion by the end of the forecast period in 2034.
Key Flame Retardant Thermoplastics Market Trends & Insights
The global demand for flame retardant thermoplastics is witnessing a paradigm shift driven by the rapid electrification of the automotive sector and the tightening of fire safety regulations across the construction and consumer electronics industries. Current market analysis reveals a significant transition from traditional halogenated flame retardants toward halogen-free alternatives, such as phosphorus and nitrogen-based compounds, primarily due to environmental concerns and health regulations like REACH and RoHS. Competitive benchmarking indicates that top-tier companies are focusing on synergistic additive systems that maintain the mechanical integrity of the polymer while enhancing fire resistance. Furthermore, the integration of advanced materials in 5G infrastructure and high-speed rail systems is creating specialized niches for high-performance flame retardant polymers that can withstand extreme thermal conditions without compromising electrical insulation properties.
- Asia Pacific: Holds the largest market share and is the fastest-growing region due to massive electronics manufacturing and infrastructure development.
- Electrical and Electronics (E&E): Dominates as the largest application segment, driven by the demand for miniaturized components and high-heat resistant enclosures.
- Halogen-Free Flame Retardants (HFFR): The fastest-growing chemical segment as manufacturers align with global sustainability and safety standards.
- Automotive & Transportation: Emerging as a critical growth engine with the surge in Electric Vehicle (EV) battery housing and interior component requirements.
Key Takeaways Flame Retardant Thermoplastics Market Size & Forecast
The market trajectory for flame retardant thermoplastics is characterized by steady expansion as industries prioritize safety and risk mitigation in high-density urban environments. The forecast indicates that while the base materials like Polypropylene (PP) and Polyamide (PA) remain dominant in terms of volume, high-performance thermoplastics like Polyether Ether Ketone (PEEK) and Polyphenylene Sulfide (PPS) are gaining traction in aerospace and medical applications. Market players are increasingly investing in research and development to address the trade-off between fire retardancy and material toughness, which remains a primary technical challenge. Additionally, the shift toward a circular economy is prompting the development of recyclable flame retardant grades, ensuring that end-of-life products meet both safety and environmental disposal criteria.
- China and India: Leading countries in terms of production capacity and domestic consumption within the industrial and construction sectors.
- Polypropylene (PP): Remains the most widely used thermoplastic resin for flame retardancy due to its cost-effectiveness and versatility in various consumer goods.
- Electric Vehicles: Represent a massive opportunity for flame retardant materials in battery modules, connectors, and charging infrastructure.
- Miniaturization: The trend in consumer electronics necessitates materials that offer high flow and excellent fire ratings for thinner wall thicknesses.
Flame Retardant Thermoplastics Market Drivers Analysis
The expansion of the flame retardant thermoplastics market is primarily catalyzed by stringent government mandates regarding fire safety in residential and commercial buildings. As urbanization intensifies, the necessity for materials that prevent or slow the spread of fire has become non-negotiable for building contractors and architects. Simultaneously, the consumer electronics industry’s push for smaller, more powerful devices leads to higher internal temperatures, necessitating advanced thermal management and flame-retardant enclosures. The transition to green energy, specifically the proliferation of EVs, requires specialized polymers for battery enclosures that can prevent thermal runaway, thereby acting as a significant driver for high-grade flame retardant thermoplastic resins.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Fire Safety Regulations (UL94, EN45545) | +2.1% | Global (Strongest in Europe/North America) | 2025 - 2034 |
| Electric Vehicle (EV) Battery Housing Demand | +1.8% | China, Germany, United States | 2026 - 2034 |
| Miniaturization of Consumer Electronics | +1.5% | South Korea, Japan, Taiwan | 2025 - 2030 |
| Rapid Infrastructure and Construction Growth | +1.4% | India, Southeast Asia, Middle East | 2025 - 2034 |
Flame Retardant Thermoplastics Market Restraints Analysis
Despite robust growth, the market faces significant headwinds from the increasing regulatory scrutiny of traditional halogenated flame retardants, which are often linked to environmental persistence and bioaccumulation. The higher cost associated with halogen-free alternatives and high-performance resins can deter price-sensitive markets, particularly in developing economies. Furthermore, the physical inclusion of flame retardant additives often compromises the mechanical properties of the base polymer, such as impact strength and elongation, requiring complex and expensive compounding solutions to maintain material performance.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental Bans on Halogenated Additives | -1.2% | European Union, California (USA) | 2025 - 2034 |
| Volatility in Raw Material and Additive Pricing | -0.8% | Global | 2025 - 2028 |
| Reduction in Mechanical Performance of Resins | -0.5% | Global | Ongoing |
Flame Retardant Thermoplastics Market Opportunities Analysis
The emergence of bio-based flame retardant thermoplastics presents a significant opportunity for market leaders to align with corporate sustainability goals. As manufacturers look to reduce their carbon footprint, the development of flame retardant grades derived from renewable resources like lignin or cellulose is gaining traction. Additionally, the rollout of 5G telecommunications infrastructure requires a new generation of low-dielectric, flame retardant materials that can handle high-frequency signals without interference, opening a high-margin revenue stream for specialty chemical providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based FR Polymers | +1.3% | Nordic Countries, North America | 2027 - 2034 |
| 5G Network Infrastructure Components | +1.1% | China, USA, South Korea | 2025 - 2030 |
| Aerospace and Defense Modernization | +0.9% | USA, France, India | 2026 - 2034 |
Flame Retardant Thermoplastics Market Challenges Impact Analysis
One of the primary challenges in the flame retardant thermoplastics market is the complexity of global supply chains for critical additives such as phosphorus and antimony. Geopolitical tensions and environmental regulations on mining can lead to supply shortages and price spikes. Furthermore, the industry must continuously innovate to meet the diverse and evolving fire safety standards across different regions and applications, which necessitates expensive testing and certification processes that can delay product time-to-market.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability for Rare Additives | -0.7% | Global (Sourced from China/Russia) | 2025 - 2030 |
| Complexity in Meeting Regional Fire Standards | -0.4% | Global | Ongoing |
| Technological Barriers in Nano-composite FRs | -0.3% | R&D focused regions | 2025 - 2028 |
Flame Retardant Thermoplastics Market - Updated Report Scope
This comprehensive market report provides an in-depth analysis of the global flame retardant thermoplastics industry, covering historical trends, current market size, and future projections. The scope includes a detailed breakdown of polymer types, additive technologies, and end-user applications across six major geographical regions. The report emphasizes the impact of regulatory shifts, technological innovations in material science, and the competitive landscape of leading global manufacturers, offering stakeholders a strategic roadmap for investment and product development over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 35.2 Billion |
| Market Forecast in 2034 | USD 63.8 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, SABIC, DuPont de Nemours Inc., Lanxess AG, Covestro AG, Clariant AG, Albemarle Corporation, Solvay S.A., Arkema S.A., Evonik Industries AG, Mitsui Chemicals, Kaneka Corporation, Huber Engineered Materials, Italmatch Chemicals, PolyOne Corporation (Avient), LyondellBasell Industries, Celanese Corporation, Asahi Kasei Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the flame retardant thermoplastics market is based on a multi-faceted approach that considers polymer morphology, chemical additive systems, and end-use vertical requirements. Semi-crystalline resins like Polyamide and Polypropylene represent a significant volume share due to their widespread use in mechanical and structural components. Amorphous resins, particularly Polycarbonate, are highly valued in the E&E sector for their transparency and impact resistance coupled with fire safety. The chemical additive segment is rapidly evolving, with inorganic fillers like Alumina Trihydrate (ATH) being favored for their smoke-suppressant properties and cost-effectiveness in construction applications.
- By Resin Type:
- Polypropylene (PP)
- Polyamide (PA 6, PA 66)
- Polycarbonate (PC)
- Polyethylene (PE)
- Acrylonitrile Butadiene Styrene (ABS)
- Polybutylene Terephthalate (PBT)
- Polyphenylene Sulfide (PPS)
- Polyether Ether Ketone (PEEK)
- By Additive Type:
- Phosphorus-based (Red Phosphorus, Phosphate Esters)
- Nitrogen-based (Melamine derivatives)
- Inorganic Hydroxides (ATH, Magnesium Hydroxide)
- Chlorinated Flame Retardants
- Brominated Flame Retardants (BFRs)
- Synergists (Antimony Trioxide)
- By Application Vertical:
- Electrical & Electronics: Enclosures, Connectors, Circuit Breakers, Switchgear
- Automotive: Interior Trims, Under-the-hood Components, EV Battery Enclosures
- Construction: Insulation Boards, Cables & Wires, Roofing Materials
- Aerospace & Defense: Cabin Interior Panels, Ducting, Seating Components
- Industrial & Others: Protective Gears, Medical Devices, Appliances
Regional Highlights
- Asia Pacific: The largest and fastest-growing market, projected to maintain a CAGR of 7.5%. Growth is fueled by China’s dominance in electronics manufacturing and India’s burgeoning construction and automotive sectors.
- North America: A mature market characterized by high innovation and the presence of leading material science companies. The region leads in the adoption of high-performance FR thermoplastics for the aerospace and defense sectors.
- Europe: Driven by the world’s most stringent environmental and fire safety regulations. Germany and France are major hubs for automotive-grade flame retardant polymers, with a strong focus on HFFR technologies.
- Latin America & MEA: Emerging regions with steady growth in infrastructure and mining applications where fire safety in cabling and heavy machinery is paramount.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Flame Retardant Thermoplastics Market.- BASF SE
- SABIC
- DuPont de Nemours, Inc.
- Lanxess AG
- Covestro AG
- Clariant AG
- Albemarle Corporation
- Solvay S.A.
- Arkema S.A.
- Evonik Industries AG
- Mitsui Chemicals, Inc.
- Kaneka Corporation
- Huber Engineered Materials
- Italmatch Chemicals S.p.A.
- Avient Corporation
- LyondellBasell Industries N.V.
- Celanese Corporation
- Asahi Kasei Corporation
- Toray Industries, Inc.
- Sumitomo Chemical Co., Ltd.
Frequently Asked Questions
What are the primary factors driving the growth of the Flame Retardant Thermoplastics Market?
The growth is primarily driven by stringent global fire safety regulations (such as UL94 and EN45545), the rapid expansion of the electric vehicle (EV) market requiring fire-safe battery housings, and the continuous demand for flame-retardant materials in the consumer electronics sector due to device miniaturization and higher heat generation.
Why is there a shift from halogenated to halogen-free flame retardants?
The shift is motivated by environmental and health concerns, as halogenated flame retardants can release toxic gases and corrosive smoke during combustion. Regulatory frameworks like REACH and RoHS have restricted many brominated and chlorinated substances, leading manufacturers to adopt safer phosphorus, nitrogen, and inorganic mineral alternatives.
Which region is expected to dominate the Flame Retardant Thermoplastics Market through 2034?
Asia Pacific is expected to dominate the market, accounting for over 45% of the global share. This is attributed to the presence of major electronics manufacturing hubs in China, Taiwan, and South Korea, coupled with significant infrastructure projects and automotive production in India and Southeast Asia.
What are the main technical challenges in developing flame retardant thermoplastics?
The primary technical challenge is maintaining the mechanical properties of the base polymer, such as toughness, flexibility, and impact resistance, which are often degraded when high concentrations of flame retardant additives are introduced. Achieving a balance between fire rating (e.g., V-0 rating) and material performance is a key area of R&D.
How does the Electric Vehicle (EV) industry impact this market?
The EV industry is a major growth catalyst, as high-voltage battery systems require flame retardant materials to prevent thermal runaway and ensure passenger safety. This has increased demand for specialized flame retardant grades of Polyamide, Polycarbonate, and Polyphenylene Sulfide for battery modules, connectors, and charging stations.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
