Fire Suppression System Market
Fire Suppression System Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711123 | Published On : October 10, 2026 |
Format : 


 | Author : Jonathan Sikka
Fire Suppression System Market Size
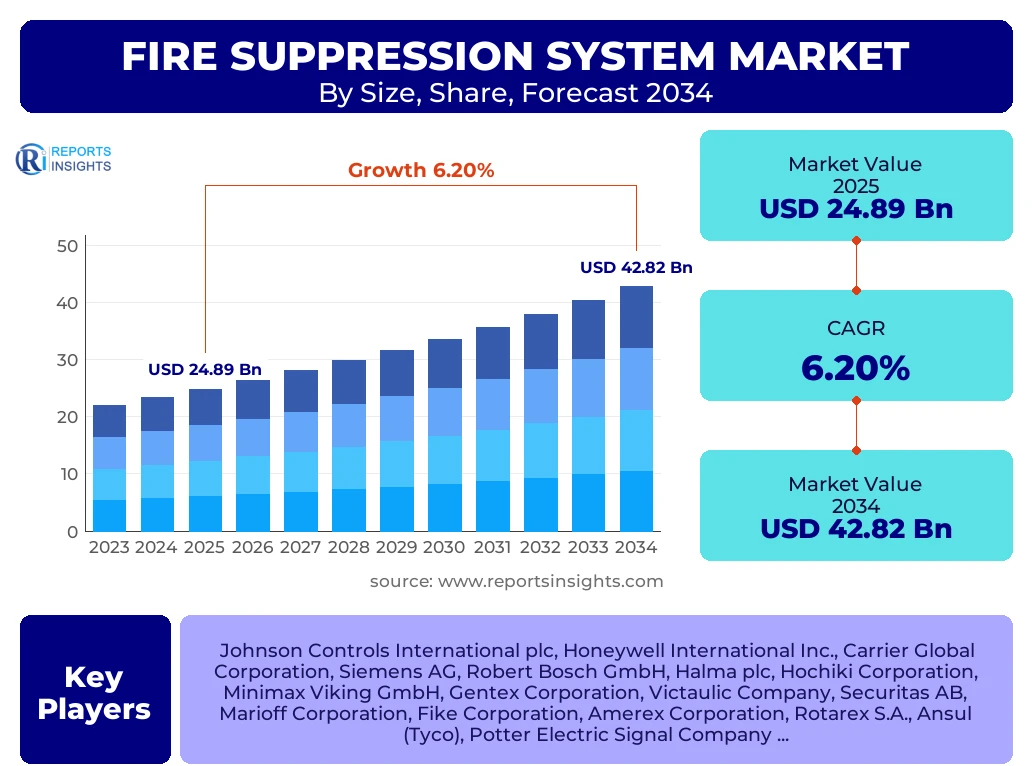
According to Reports Insights Consulting Pvt Ltd, The Fire Suppression System Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 26.43 Billion in 2026 and is projected to reach USD 42.82 Billion by the end of the forecast period in 2034.
Key Fire Suppression System Market Trends & Insights
The global fire suppression system market is undergoing a significant transformation driven by the integration of Internet of Things (IoT) technologies and the rising demand for sustainable, clean-agent suppression solutions. As urbanization accelerates and industrial safety regulations become more stringent worldwide, stakeholders are prioritizing systems that offer real-time monitoring and minimized collateral damage. The shift toward smart cities and intelligent building management systems has catalyzed the adoption of wireless fire detection and suppression arrays, which reduce installation complexity and enhance system reliability in diverse environments ranging from data centers to high-rise residential complexes.
- Largest Region: North America remains the largest regional market, bolstered by rigorous enforcement of fire safety codes such as NFPA standards and a high concentration of commercial and industrial infrastructure.
- Fastest Growing Region: Asia Pacific is the fastest-growing region, fueled by rapid industrialization in China and India, alongside massive investments in smart city projects and infrastructure development.
- Leading Segment by Type: The Fire Sprinkler Systems segment holds the largest market share due to its widespread mandatory installation in commercial and residential buildings globally.
- Emerging Trend: Increased adoption of Clean Agent Fire Suppression systems (such as FM-200 and Novec 1230) is observed in sensitive environments like server rooms and museums to prevent water-related equipment damage.
Key Takeaways Fire Suppression System Market Size & Forecast
The forecast period from 2025 to 2034 indicates a robust expansion phase for the fire suppression industry, characterized by a transition from traditional mechanical systems to automated, sensor-driven architectures. Market analysts observe that the industrial sector, particularly oil and gas and chemical processing, continues to necessitate heavy-duty suppression technologies, while the residential sector is seeing a spike in growth due to modernizing building bylaws. The integration of artificial intelligence for early-stage smoke and flame detection is expected to redefine response times, significantly reducing property loss and ensuring human safety across various high-risk applications.
- Strategic Market Value: The market is set to surpass the USD 40 Billion mark by 2034, reflecting the non-discretionary nature of fire safety investments in a post-pandemic economic landscape.
- Regulatory Influence: Stringent government regulations and insurance requirements act as the primary catalysts for market entry and system upgrades in both developed and emerging economies.
- Industrial Dominance: The industrial application segment leads the market value, driven by the high cost of specialized suppression systems required for volatile chemical and manufacturing environments.
- Technological Shift: The transition from HALON-based systems to environmentally friendly alternatives is nearly complete in major markets, opening significant opportunities for replacement and retrofit services.
Fire Suppression System Market Drivers Analysis
The primary driver for the fire suppression system market is the continuous evolution of global safety standards and building codes. Organizations such as the National Fire Protection Association (NFPA) and European Norms (EN) frequently update their guidelines, necessitating the modernization of existing fire safety infrastructure. Furthermore, the rapid expansion of the global construction industry, particularly in the commercial and industrial sectors, creates a direct demand for integrated fire suppression solutions that comply with modern safety protocols.
Another significant driver is the increasing awareness regarding workplace safety and the potential for catastrophic financial losses associated with fire-related incidents. Businesses are increasingly viewing fire suppression systems not just as a regulatory requirement, but as a critical component of business continuity planning. This is especially true for data centers and telecommunication hubs, where even a minor fire can lead to massive data loss and operational downtime, prompting heavy investment in specialized gaseous and water mist suppression technologies.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Regulatory Standards and Building Codes | +2.1% | Global (Strongest in Europe & North America) | 2025 - 2034 |
| Expansion of Data Centers and IT Infrastructure | +1.8% | United States, China, Ireland | 2026 - 2030 |
| Rapid Urbanization and Smart City Projects | +1.5% | India, UAE, Saudi Arabia | 2025 - 2034 |
Fire Suppression System Market Restraints Analysis
High initial installation costs and significant maintenance expenditures represent the most substantial restraints to market growth. For small and medium-sized enterprises (SMEs), the capital outlay required for advanced fire suppression systems, including specialized sensors, control panels, and suppression agents, can be prohibitive. This often leads to the installation of bare-minimum compliant systems rather than state-of-the-art solutions, slowing down the overall adoption of advanced technologies.
Furthermore, technical complexities and the requirement for highly skilled personnel for installation and periodic servicing pose challenges. Many suppression systems, particularly those using chemical agents or intricate water mist technology, require precise calibration and regular inspections. In regions where there is a shortage of certified fire safety engineers, the deployment and effective operation of these systems are often compromised, leading to longer project timelines and increased operational costs.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Installation and Capital Investment | -1.2% | Developing Nations (Latin America, Africa) | 2025 - 2028 |
| Technical Complexity and Skilled Labor Shortage | -0.8% | Southeast Asia, Middle East | 2025 - 2034 |
Fire Suppression System Market Opportunities Analysis
The integration of the Internet of Things (IoT) and Artificial Intelligence (AI) presents a transformative opportunity for the fire suppression market. Smart systems that can distinguish between a false alarm and a genuine fire threat using advanced algorithms can significantly reduce the costs associated with accidental discharges. Furthermore, remote monitoring capabilities allow facility managers to oversee the health of fire suppression systems across multiple locations via a single interface, creating a market for subscription-based "Fire Safety as a Service" (FSaaS) models.
Retrofitting aging infrastructure in developed economies also serves as a massive opportunity. Many older commercial and industrial buildings in North America and Europe are equipped with outdated fire safety technology that no longer meets modern environmental or safety standards. The transition toward eco-friendly suppression agents and wireless detection systems provides a steady stream of revenue for companies specializing in system upgrades and replacements, particularly as green building certifications become more prestigious.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI and IoT Integration for Smart Detection | +1.9% | Global (Advanced Economies) | 2026 - 2034 |
| Retrofitting Older Commercial Buildings | +1.4% | United Kingdom, Germany, United States | 2025 - 2034 |
| Demand for Eco-friendly Gaseous Agents | +1.2% | Japan, Scandinavia, South Korea | 2027 - 2034 |
Fire Suppression System Market Challenges Impact Analysis
Environmental concerns regarding the chemical composition of certain fire suppression agents continue to challenge the industry. While Halon has been phased out, some current clean agents and foams are coming under scrutiny due to their Global Warming Potential (GWP) or the presence of Per- and Polyfluoroalkyl Substances (PFAS). Navigating the evolving landscape of environmental regulations requires constant research and development, which can strain the resources of smaller manufacturers and disrupt existing supply chains.
Supply chain volatility, particularly for electronic components used in control panels and advanced sensors, remains a persistent challenge. Geopolitical tensions and trade restrictions can lead to sudden shortages of critical semiconductors and raw materials, causing delays in large-scale fire safety projects. Additionally, the lack of standardized global regulations can complicate the manufacturing process for multinational companies that must adapt their products to meet varying regional requirements.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Environmental Regulations on Chemical Agents | -1.0% | European Union, North America | 2025 - 2034 |
| Global Supply Chain Disruptions | -0.7% | Global | 2025 - 2027 |
Fire Suppression System Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global fire suppression system market, focusing on technological advancements, regulatory frameworks, and competitive dynamics. It provides a comprehensive evaluation of various system types including sprinklers, gaseous systems, and dry chemicals, categorized by their application in residential, commercial, and industrial sectors. The report also investigates the impact of emerging technologies like smart sensors and IoT-based monitoring on the future trajectory of the market through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 24.89 Billion |
| Market Forecast in 2034 | USD 42.82 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Johnson Controls International plc, Honeywell International Inc., Carrier Global Corporation, Siemens AG, Robert Bosch GmbH, Halma plc, Hochiki Corporation, Minimax Viking GmbH, Gentex Corporation, Victaulic Company, Securitas AB, Marioff Corporation, Fike Corporation, Amerex Corporation, Rotarex S.A., Ansul (Tyco), Potter Electric Signal Company, Gielle Industries, Firetrace International, Danfoss. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The fire suppression system market is segmented based on product type, component, and end-user application to provide a granular view of market dynamics. The product segment is historically led by fire sprinkler systems due to their proven efficacy and regulatory mandates. However, the gaseous suppression segment is witnessing rapid growth in specialized sectors like IT and telecommunications. The component segment highlights the increasing importance of control panels and sensors, which act as the intelligence hub for modern suppression networks. Application-wise, the industrial sector remains the highest value-generating segment, though the commercial sector is expanding rapidly due to the proliferation of office spaces and retail hubs in developing nations.
- By Product Type: Fire Sprinkler Systems, Gaseous Suppression Systems, Water Mist Systems, Foam Systems, and Fire Extinguishers.
- By Component: Detectors & Sensors (Smoke, Heat, Flame), Control Panels, Fire Suppression Reagents (Water, Gas, Chemical), and Distribution Hardware.
- By End-User Application: Commercial Buildings (Hotels, Retail, Schools), Industrial Facilities (Chemical Plants, Refineries, Warehouses), Residential Complexes, and Transport & Infrastructure (Aviation, Rail, Marine).
- By Suppression Agent: Water, CO2, Clean Agents (Inert Gases, Chemical Agents), and Dry Chemicals.
Regional Highlights
- North America: This region holds the largest market share, driven by a mature regulatory environment, high fire safety awareness, and the presence of major industry players. The United States is the primary contributor, focusing on upgrading aging infrastructure and adopting smart fire technologies.
- Asia Pacific: Recognized as the fastest-growing market, APAC's growth is propelled by rapid infrastructure expansion in China, India, and Southeast Asia. Increasing industrial activities and the development of massive commercial hubs are creating substantial demand for integrated suppression systems.
- Europe: The market is characterized by stringent environmental regulations regarding suppression agents and a strong emphasis on fire safety in historical and commercial buildings. Countries like Germany and the UK are leaders in adopting water mist and clean-agent technologies.
- Middle East and Africa: Growth is driven by the energy sector (oil and gas) and high-profile construction projects in the GCC countries. The harsh environmental conditions in this region necessitate highly durable and specialized suppression systems.
- Latin America: This region is experiencing steady growth, particularly in the industrial and mining sectors of Brazil and Chile, as international safety standards are increasingly adopted by local enterprises.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Fire Suppression System Market.- Johnson Controls International plc
- Honeywell International Inc.
- Carrier Global Corporation
- Siemens AG
- Robert Bosch GmbH
- Halma plc
- Hochiki Corporation
- Minimax Viking GmbH
- Gentex Corporation
- Victaulic Company
- Securitas AB
- Marioff Corporation
- Fike Corporation
- Amerex Corporation
- Rotarex S.A.
- Ansul (A Tyco brand)
- Potter Electric Signal Company
- Gielle Industries
- Firetrace International
- Danfoss
Frequently Asked Questions
What is the projected growth rate of the Fire Suppression System market from 2025 to 2034?
The market is projected to grow at a Compound Annual Growth Rate (CAGR) of approximately 6.2% during the forecast period, reaching an estimated value of USD 42.82 Billion by 2034.
Which region currently dominates the global Fire Suppression System market?
North America currently dominates the market due to its stringent fire safety regulations, established commercial infrastructure, and high adoption rate of advanced safety technologies.
What are the most common clean agents used in modern fire suppression?
The most common clean agents include chemical agents like Novec 1230 and FM-200, as well as inert gases like Argonite and Inergen, which leave no residue and are safe for electronic equipment.
How is IoT technology impacting the Fire Suppression System market?
IoT allows for real-time monitoring, predictive maintenance, and integrated communication between sensors and suppression units, which reduces false alarms and ensures the system is operational during emergencies.
What are the main drivers for fire suppression adoption in the industrial sector?
The primary drivers include the high risk of volatile materials, the need to protect expensive machinery, regulatory compliance for worker safety, and the requirement for business continuity in high-output environments.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
