Electronic Contract Manufacturing Design Services Market
Electronic Contract Manufacturing Design Services Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711589 | Published On : November 07, 2026 |
Format : 


 | Author : Jonathan Sikka
Electronic Contract Manufacturing Design Services Market Size
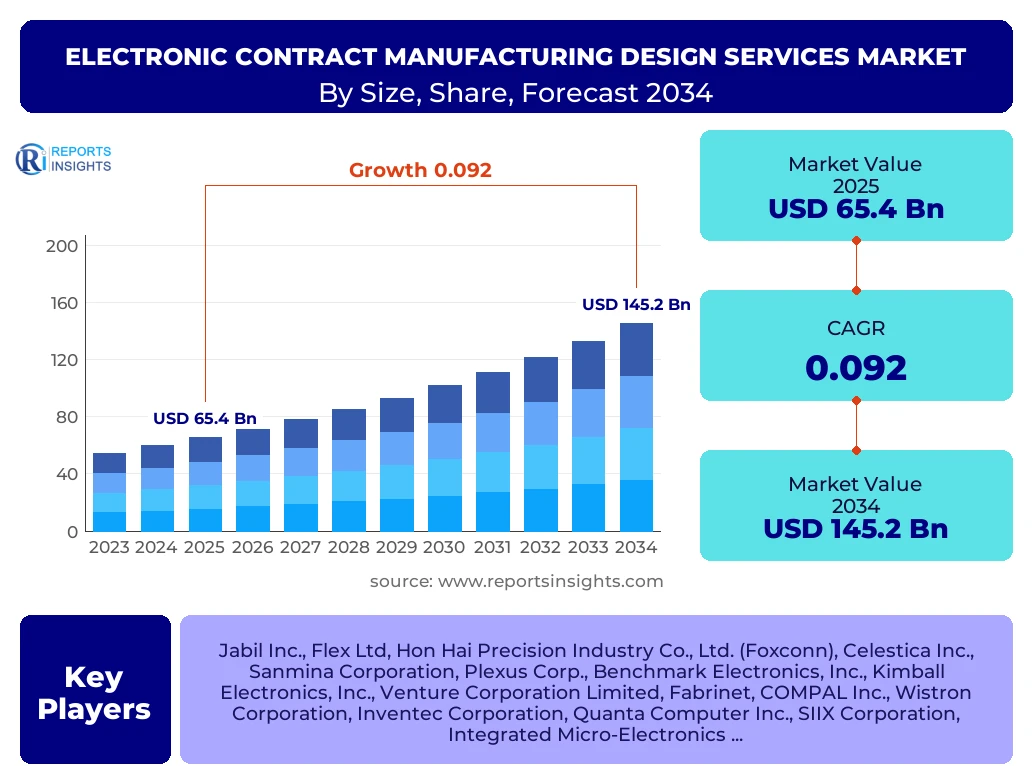
According to Reports Insights Consulting Pvt Ltd, The Electronic Contract Manufacturing Design Services Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.2% between 2025 and 2034. The market is estimated at USD 71.42 Billion in 2026 and is projected to reach USD 145.2 Billion by the end of the forecast period in 2034.
Key Electronic Contract Manufacturing Design Services Market Trends & Insights
The global landscape for electronic design and contract manufacturing is undergoing a structural shift as original equipment manufacturers (OEMs) increasingly pivot from simple assembly to end-to-end design collaboration. Modern electronic products require sophisticated engineering in high-density interconnect (HDI) printed circuit boards, signal integrity analysis, and thermal management, pushing OEMs to rely on the specialized technical expertise of contract designers. The convergence of Artificial Intelligence (AI) and the Internet of Things (IoT) has catalyzed a demand for smart, connected hardware that necessitates advanced prototyping and rapid iterative cycles, which are the core competencies of top-tier design service providers.
- Largest Region: Asia-Pacific remains the dominant powerhouse, accounting for over 45% of the total market share due to its established semiconductor ecosystem and massive manufacturing infrastructure in China, Taiwan, and Vietnam.
- Fastest Growing Region: North America is poised for the highest growth rate during the forecast period, driven by aggressive reshoring initiatives and the rapid expansion of the electric vehicle (EV) and aerospace sectors.
- Largest Segment by Share: The IT and Telecommunications segment currently holds the largest market share, fueled by the global rollout of 5G infrastructure and the demand for high-performance data center hardware.
- Leading Service Type: Electronic design services, specifically front-end engineering and PCB layout design, are experiencing higher growth margins compared to traditional testing or assembly services.
Key Takeaways Electronic Contract Manufacturing Design Services Market Size & Forecast
Strategic analysis of the market indicates that the transition toward Industry 4.0 and the integration of edge computing are the primary engines of value creation. Market participants are increasingly adopting generative design tools and digital twins to reduce time-to-market and enhance product reliability. This technological leap is essential as the complexity of consumer and industrial electronics reaches levels where manual design processes are no longer feasible or cost-effective. Furthermore, the push for environmental sustainability is forcing design service providers to implement "Design for Circularity" principles, ensuring products are easier to repair, recycle, and upgrade.
- Market Valuation: The total addressable market is expected to more than double by 2034, reflecting the critical role of outsourced design in the modern electronics supply chain.
- Leading Country: China continues to lead in volume, but the United States is emerging as the leader in high-value, specialized electronic design for medical and defense applications.
- Industrial Shift: The automotive sector is transitioning into a "software-defined vehicle" era, which has tripled the demand for complex electronic control units (ECUs) and sensor integration design services.
- Strategic Mergers: There is a notable trend of Tier 1 EMS providers acquiring niche design firms to offer a "concept-to-production" vertical service model, capturing higher margins.
Electronic Contract Manufacturing Design Services Market Drivers Analysis
The primary driver for the Electronic Contract Manufacturing (ECM) design services market is the accelerating complexity of semiconductor integration and the global shift toward miniaturization. As components shrink and power densities increase, OEMs face significant internal R&D hurdles, leading them to outsource design tasks to specialized partners who possess the requisite thermal and electromagnetic interference (EMI) expertise. Additionally, the rapid lifecycle of consumer electronics necessitates a reduction in development time, making the agile prototyping capabilities of contract designers indispensable for maintaining competitive advantages.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Demand for Automotive Electronics & EVs | +2.8% | Germany, USA, China | 2025-2034 |
| Expansion of 5G and Edge Computing Infrastructure | +2.5% | South Korea, Japan, USA | 2025-2030 |
| Miniaturization of Medical Wearable Devices | +1.9% | Switzerland, Israel, USA | 2026-2034 |
Electronic Contract Manufacturing Design Services Market Restraints Analysis
Despite robust growth, the market faces significant headwinds from fluctuating raw material prices and the high cost of advanced EDA (Electronic Design Automation) software licenses. Furthermore, the ongoing global shortage of skilled engineering talent—specifically those proficient in RF design and high-speed digital layout—poses a barrier to scaling operations. Intellectual property (IP) security remains a paramount concern for OEMs when outsourcing sensitive design layouts, particularly in sectors such as defense and aerospace where national security protocols are stringent.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Semiconductor Supply Chains | -1.5% | Global | 2025-2028 |
| Stringent IP Protection Regulations | -1.1% | China, India, SE Asia | 2025-2034 |
Electronic Contract Manufacturing Design Services Market Opportunities Analysis
The integration of AI-driven generative design represents a transformative opportunity for the market, allowing service providers to automate routine layout tasks and focus on high-level architecture. There is also a burgeoning opportunity in the "Green Electronics" movement, where design services are sought to optimize power efficiency and utilize sustainable materials. As regional governments provide subsidies for domestic electronics manufacturing (such as the CHIPS Act in the US and the PLI scheme in India), design firms that establish local presence in these regions stand to benefit from significant public-private partnership opportunities.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Enabled Design Automation Tools | +3.2% | Global | 2027-2034 |
| Government Incentives for Domestic Electronics | +2.4% | India, USA, EU | 2025-2030 |
Electronic Contract Manufacturing Design Services Market Challenges Impact Analysis
The primary challenge involves the rapid pace of technological obsolescence, which requires constant capital reinvestment in new testing equipment and software. Design service providers must also navigate a complex web of international trade sanctions and export controls that can suddenly disrupt partnerships between designers and manufacturers in different jurisdictions. Maintaining quality consistency across high-volume production while managing the nuances of low-volume, high-complexity prototype runs requires an exceptionally high level of operational flexibility.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Specialized RF/Analog Engineers | -1.8% | North America, Europe | 2025-2034 |
| Cross-Border Regulatory Compliance Costs | -1.2% | EU, China | 2025-2030 |
Electronic Contract Manufacturing Design Services Market - Updated Report Scope
This report provides a comprehensive examination of the global electronic contract manufacturing design services ecosystem, covering the full spectrum from initial product conceptualization to high-volume manufacturing support. It analyzes the shift toward value-added engineering services and explores how emerging technologies like 6G, autonomous systems, and advanced healthcare diagnostics are reshaping the competitive landscape for service providers and their OEM clients.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 65.4 Billion |
| Market Forecast in 2034 | USD 145.2 Billion |
| Growth Rate | 9.2% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Jabil Inc., Flex Ltd, Hon Hai Precision Industry Co., Ltd. (Foxconn), Celestica Inc., Sanmina Corporation, Plexus Corp., Benchmark Electronics, Inc., Kimball Electronics, Inc., Venture Corporation Limited, Fabrinet, COMPAL Inc., Wistron Corporation, Inventec Corporation, Quanta Computer Inc., SIIX Corporation, Integrated Micro-Electronics, Inc. (IMI), Neways Electronics International N.V., Zollner Elektronik AG. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of this market reflects the diverse technical requirements across different industrial verticals, with each segment demanding unique certifications and engineering skill sets. While consumer electronics drive high-volume design for cost optimization, segments like aerospace and healthcare prioritize reliability and long-term lifecycle support. The market is also segmented by the stage of the design cycle, with a growing emphasis on front-end conceptualization and post-design testing services to ensure compliance with global standards like ISO and CE.
- By Service Type:
- Electronic Design (Schematic Capture, PCB Layout)
- Circuit Modeling & Simulation
- Rapid Prototyping & NPI (New Product Introduction)
- Design for Excellence (DFX)
- Testing & Quality Assurance
- By End-User Industry:
- IT & Telecommunications (5G Radios, Data Centers)
- Consumer Electronics (Smartphones, Smart Home)
- Automotive (EV Powertrains, ADAS Systems)
- Healthcare & Medical Devices (Diagnostic Imaging, Wearables)
- Aerospace & Defense (Avionics, Satellite Communication)
- Industrial Automation (Robotics, IoT Sensors)
- By Scale of Operation:
- Tier 1 EMS (Global Operations)
- Tier 2 & 3 Providers (Regional Specialized Firms)
Regional Highlights
Regional dynamics are currently defined by the tension between manufacturing cost-efficiency and supply chain resilience. Asia-Pacific continues to benefit from a dense concentration of component suppliers and a massive workforce, making it the leader in sheer production volume. However, the regulatory environment in the European Union and North America is increasingly favoring localized design to secure critical infrastructure. The emergence of India as a global manufacturing hub, supported by government incentives, is expected to shift a significant portion of the design workload from traditional centers in East Asia toward South Asia over the next decade.
- Asia-Pacific: Remains the Largest Region by value, with China and Vietnam serving as the primary manufacturing hubs for global consumer electronics and telecommunications hardware.
- North America: Identified as the Fastest Growing Region, with the United States leading in high-tech design for military-grade electronics and innovative medical technology.
- Europe: A key player in high-quality industrial and automotive design services, particularly in Germany and the Nordic countries, focusing on Industry 4.0 and green energy electronics.
- Latin America & MEA: Emerging markets with significant growth potential in basic consumer electronics assembly and regional telecommunications infrastructure development.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Electronic Contract Manufacturing Design Services Market.- Jabil Inc.
- Flex Ltd
- Hon Hai Precision Industry Co., Ltd. (Foxconn)
- Celestica Inc.
- Sanmina Corporation
- Plexus Corp.
- Benchmark Electronics, Inc.
- Kimball Electronics, Inc.
- Venture Corporation Limited
- Fabrinet
- COMPAL Inc.
- Wistron Corporation
- Inventec Corporation
- Quanta Computer Inc.
- SIIX Corporation
- Integrated Micro-Electronics, Inc. (IMI)
- Neways Electronics International N.V.
- Zollner Elektronik AG
- Asteelflash
- Creation Technologies
Frequently Asked Questions
What is the difference between EMS and Electronic Design Services?
Electronic Manufacturing Services (EMS) typically focus on the assembly and mass production of products, while Electronic Design Services specifically involve the engineering, schematic creation, and PCB layout phases that occur before mass production begins.
How is AI impacting the electronic contract manufacturing market?
AI is accelerating the design cycle by automating complex PCB routing, predicting potential thermal failures, and optimizing component placement, which significantly reduces the time required for the prototyping and testing phases.
Which industry vertical is seeing the fastest adoption of outsourced design?
The automotive industry is currently seeing the fastest adoption due to the rapid transition toward electric vehicles and autonomous driving systems, both of which require highly complex, specialized electronic architectures.
Why is the North American market growing so rapidly?
North America is experiencing high growth due to reshoring policies, a surge in aerospace and defense spending, and a concentration of startups in the medical device and IoT sectors that lack internal manufacturing capabilities.
What are the key challenges in the ECM design services sector?
Key challenges include the shortage of high-level engineering talent, the need for constant investment in advanced CAD/EDA software, and the complexity of managing intellectual property across global supply chains.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
