Electrocoat Market
Electrocoat Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711954 | Published On : November 22, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Electrocoat Market Size
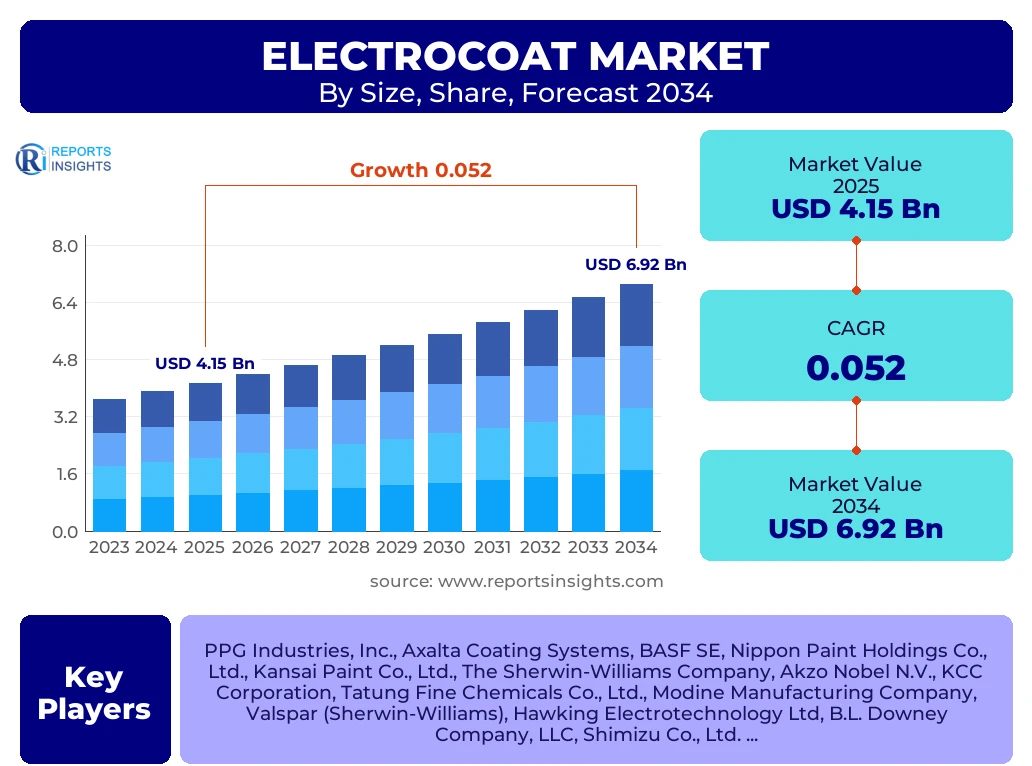
According to Reports Insights Consulting Pvt Ltd, The Electrocoat Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 4.38 Billion in 2026 and is projected to reach USD 6.92 Billion by the end of the forecast period in 2034.
Key Electrocoat Market Trends & Insights
The global electrocoat industry is undergoing a significant transformation driven by the intersection of environmental sustainability and advanced material science. Modern industrial requirements favor cathodic electrodeposition (CED) over traditional anodic methods due to superior corrosion resistance and throw power. Market participants are increasingly focusing on the development of lead-free and low-VOC (Volatile Organic Compound) formulations to align with global environmental mandates like REACH and the Clean Air Act. Additionally, the electrification of the automotive sector has introduced new technical requirements for electrocoating, specifically regarding the insulation and protection of battery housings and peripheral components. The integration of smart manufacturing and automation in coating lines is further optimizing material utilization and reducing waste, positioning electrocoating as a critical process for high-volume manufacturing environments.
- Largest Region: Asia-Pacific remains the dominant force, accounting for over 45% of the total market share, bolstered by massive automotive and electronics manufacturing hubs in China, India, and Japan.
- Fastest Growing Region: Southeast Asia and parts of Latin America are exhibiting the highest growth rates due to rapid industrialization and the relocation of manufacturing bases.
- Leading Segment: The Cathodic Epoxy segment holds the largest share by chemistry type, valued for its exceptional chemical resistance and durability in harsh environments.
- Dominant End-Use: The Automotive industry continues to be the primary consumer of electrocoat technologies, particularly for primer applications on vehicle bodies and frames.
Key Takeaways Electrocoat Market Size & Forecast
The trajectory of the electrocoat market is firmly rooted in the expansion of the global automotive supply chain and the rising demand for long-lasting consumer durables. As manufacturers strive to extend the lifecycle of their products, the adoption of electrocoating as a foundational anti-corrosive layer has become non-negotiable. The forecast period is expected to see a rise in niche applications, including aerospace components and specialized medical devices, where precision coating thickness is essential. Strategic investments in R&D are currently focused on reducing the curing temperatures of e-coats, which would significantly lower the energy footprint of coating facilities, addressing one of the major operational costs in the industry.
- Market Maturity: While the North American and European markets are relatively mature, growth is sustained through the replacement of legacy systems with high-efficiency, sustainable alternatives.
- China’s Influence: China is the single largest national market, driven by its status as the global leader in both traditional internal combustion engine (ICE) and electric vehicle (EV) production.
- Product Innovation: The shift toward "thin-film" technology is a critical takeaway, allowing for reduced material consumption without compromising protective properties.
- Infrastructure Demand: Increasing infrastructure projects in emerging economies are driving the demand for electrocoated heavy machinery and structural components.
Electrocoat Market Drivers Analysis
The primary catalysts for the electrocoat market involve a combination of regulatory pressures and technical performance advantages. As global emissions standards tighten, the low-VOC nature of waterborne electrocoats makes them the preferred choice for large-scale industrial finishers. Furthermore, the inherent efficiency of the process—boasting transfer efficiencies of up to 99%—provides a compelling economic argument for high-volume production lines where material waste directly impacts the bottom line. The surge in electric vehicle production is a specific driver, as the complex geometries of battery enclosures require the high "throw power" that only electrodeposition can provide to ensure complete coverage of recessed areas.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Expansion of Electric Vehicle (EV) Manufacturing | +1.8% | Global (High in China, Germany, USA) | 2025 - 2034 |
| Stringent Environmental Regulations (Low VOC/Lead-Free) | +1.2% | European Union, North America | 2025 - 2030 |
| High Transfer Efficiency and Material Cost Savings | +0.9% | Global (Industrial Finishers) | 2026 - 2034 |
| Growth in Agricultural and Construction Equipment (ACE) | +1.3% | India, Brazil, Southeast Asia | 2025 - 2034 |
Electrocoat Market Restraints Analysis
Despite the technical advantages, the electrocoat market faces hurdles related to high entry barriers and operational rigidity. The initial capital expenditure required to install a full-scale electrocoating line—including tanks, ultrafiltration systems, and curing ovens—is substantial, often deterring small and medium-sized enterprises (SMEs). Additionally, the process is energy-intensive, particularly during the thermal curing phase, making it sensitive to fluctuations in industrial electricity and gas prices. The complexity of maintaining bath stability and chemistry balance also requires highly skilled labor and constant monitoring, which can increase operational overhead.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Expenditure (CAPEX) | -0.7% | Emerging Markets (SME sector) | 2025 - 2034 |
| High Energy Consumption for Thermal Curing | -0.5% | Europe (High Energy Costs) | 2025 - 2028 |
| Complex Chemical Maintenance and Bath Stability | -0.4% | Global | 2026 - 2034 |
Electrocoat Market Opportunities Analysis
The evolution of electrocoating chemistry presents lucrative opportunities for market expansion, particularly in the development of low-temperature curing systems. If curing temperatures can be reduced from the standard 160-180°C to 120-140°C, the energy savings would be transformative for the industry. Furthermore, the expansion of the electronics sector, specifically for 5G infrastructure and consumer electronics, requires precise, thin-film coatings for heat dissipation and corrosion protection, a niche where specialized e-coats can excel. The untapped potential in the African and Middle Eastern manufacturing sectors also represents a long-term growth frontier for global chemical suppliers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Low-Temperature Curing Formulations | +1.5% | Global (Industrial Coatings) | 2027 - 2034 |
| Customized Coatings for 5G and Electronic Components | +0.8% | South Korea, Taiwan, Japan | 2026 - 2032 |
| Expansion into Aerospace and Defense Applications | +0.6% | North America, France | 2028 - 2034 |
Electrocoat Market Challenges Impact Analysis
One of the most persistent challenges in the electrocoat market is the limitation in color variety. Unlike traditional liquid paint or powder coatings, electrocoating is typically used as a primer or a single-color finish (usually black or grey) because changing colors in a large dip tank is economically unfeasible. This limits its use in top-coat applications where aesthetics and frequent color changes are required. Additionally, the sensitivity of the process to substrate cleanliness means that any upstream pretreatment failure can lead to catastrophic coating defects, requiring rigorous and expensive quality control protocols.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Limited Color Flexibility for Top-Coat Applications | -0.6% | Consumer Goods, Decorative Segments | 2025 - 2034 |
| Sensitivity to Substrate Pretreatment Quality | -0.4% | Global Manufacturing | 2025 - 2034 |
| Fluctuating Raw Material Prices (Epoxy and Acrylic Resins) | -0.5% | Global Supply Chain | 2025 - 2030 |
Electrocoat Market - Updated Report Scope
This comprehensive market report provides a multi-dimensional analysis of the global electrocoat industry, covering chemical formulations, application techniques, and end-user vertical requirements. It delves into the technical nuances of anodic versus cathodic systems and provides a detailed forecast of material consumption across different industrial landscapes. The scope includes an evaluation of the competitive landscape, examining how major chemical conglomerates are positioning themselves through mergers, acquisitions, and sustainable product launches to capture market share in a rapidly evolving regulatory environment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.15 Billion |
| Market Forecast in 2034 | USD 6.92 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | PPG Industries, Inc., Axalta Coating Systems, BASF SE, Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., The Sherwin-Williams Company, Akzo Nobel N.V., KCC Corporation, Tatung Fine Chemicals Co., Ltd., Modine Manufacturing Company, Valspar (Sherwin-Williams), Hawking Electrotechnology Ltd, B.L. Downey Company, LLC, Shimizu Co., Ltd., Nordson Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The electrocoat market is segmented based on chemistry, technology type, and end-use application, reflecting the diverse industrial requirements for corrosion protection and finish quality. Cathodic electrodeposition (CED) dominates the market because of its superior performance on ferrous substrates, while anodic systems remain relevant for specific non-ferrous applications like aluminum extrusion and certain decorative finishes. The automotive sector remains the largest segment by far, but heavy-duty equipment and home appliances are showing significant growth as manufacturers seek to improve product longevity in competitive markets.
- By Type:
- Cathodic Epoxy (Standard for automotive primers)
- Cathodic Acrylic (Used for one-coat finishes and UV resistance)
- Anodic Epoxy (Industrial components)
- Anodic Acrylic (Decorative hardware and aluminum)
- By Application:
- Automotive OEM (Vehicle bodies and chassis)
- Automotive Components (Brake lines, fuel tanks, fasteners)
- Heavy-Duty Equipment (Agricultural machinery, construction vehicles)
- Appliances (Refrigerators, washing machines, HVAC units)
- Decorative & Hardware (Lighting fixtures, office furniture)
- Electronics (Chassis, heat sinks, connectors)
Regional Highlights
- Asia-Pacific: The undisputed leader in the market, Asia-Pacific’s dominance is fueled by China’s massive automotive output and the growing electronics manufacturing sectors in Vietnam, Thailand, and South Korea. India is emerging as a critical growth node due to rising domestic infrastructure projects.
- North America: This region is characterized by a high adoption rate of advanced cathodic technologies and a strong focus on the heavy-duty equipment and aerospace sectors. The United States is a key market for specialized e-coats used in the defense industry.
- Europe: Driven by the most stringent environmental regulations globally, Europe leads in the adoption of lead-free and sustainable electrocoat formulations. Germany remains the regional hub due to its premium automotive manufacturing base.
- Latin America & MEA: These regions are seeing steady growth as global OEMs expand their manufacturing footprints into Brazil, Mexico, and South Africa to serve local emerging middle-class populations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Electrocoat Market.- PPG Industries, Inc.
- Axalta Coating Systems
- BASF SE
- Nippon Paint Holdings Co., Ltd.
- Kansai Paint Co., Ltd.
- The Sherwin-Williams Company
- Akzo Nobel N.V.
- KCC Corporation
- Tatung Fine Chemicals Co., Ltd.
- Modine Manufacturing Company
- Valspar
- Hawking Electrotechnology Ltd
- B.L. Downey Company, LLC
- Shimizu Co., Ltd.
- Nordson Corporation
- Nycote Laboratories Corporation
- Dymax Corporation
- Acheson (Henkel)
- Master Bond Inc.
- Houghton International Inc.
Frequently Asked Questions
What is the main advantage of cathodic electrocoat over anodic electrocoat?
Cathodic electrocoat (CED) offers significantly higher corrosion resistance and chemical durability compared to anodic systems. Because the part acts as the cathode, there is no dissolution of the metal into the coating bath, which ensures a cleaner, more stable process and a more robust protective layer for ferrous metals.
How is the growth of electric vehicles impacting the electrocoat market?
The EV boom is a major driver, as electric vehicles require specialized coatings for battery enclosures and complex electrical housing components. These parts need high-precision anti-corrosive layers that can reach deep into recessed areas, a performance characteristic where electrocoating excels compared to spray or powder methods.
Are electrocoats considered environmentally friendly?
Yes, electrocoats are among the most sustainable industrial coating options. They are waterborne, which results in very low VOC emissions. Additionally, the process efficiency is near 99%, meaning almost all the material in the tank ends up on the part, drastically reducing chemical waste and environmental impact.
What are the typical curing requirements for electrocoated parts?
Standard electrocoats typically require thermal curing in an oven at temperatures between 160°C and 180°C (320°F to 350°F) for approximately 20 to 30 minutes. However, a major industry trend is the development of low-cure formulations that can cross-link at lower temperatures to save energy.
Which region is expected to see the fastest growth in the next decade?
Asia-Pacific is projected to remain the fastest-growing region. This is due to the continued relocation of manufacturing centers to Southeast Asia and the explosive growth of the domestic automotive and consumer electronics markets in India and China.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
