Electric Vehicle Testing Inspection Certification Market
Electric Vehicle Testing Inspection Certification Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711025 | Published On : September 29, 2026 |
Format : 


 | Author : Ashraf Shehata
Electric Vehicle Testing Inspection Certification Market Size
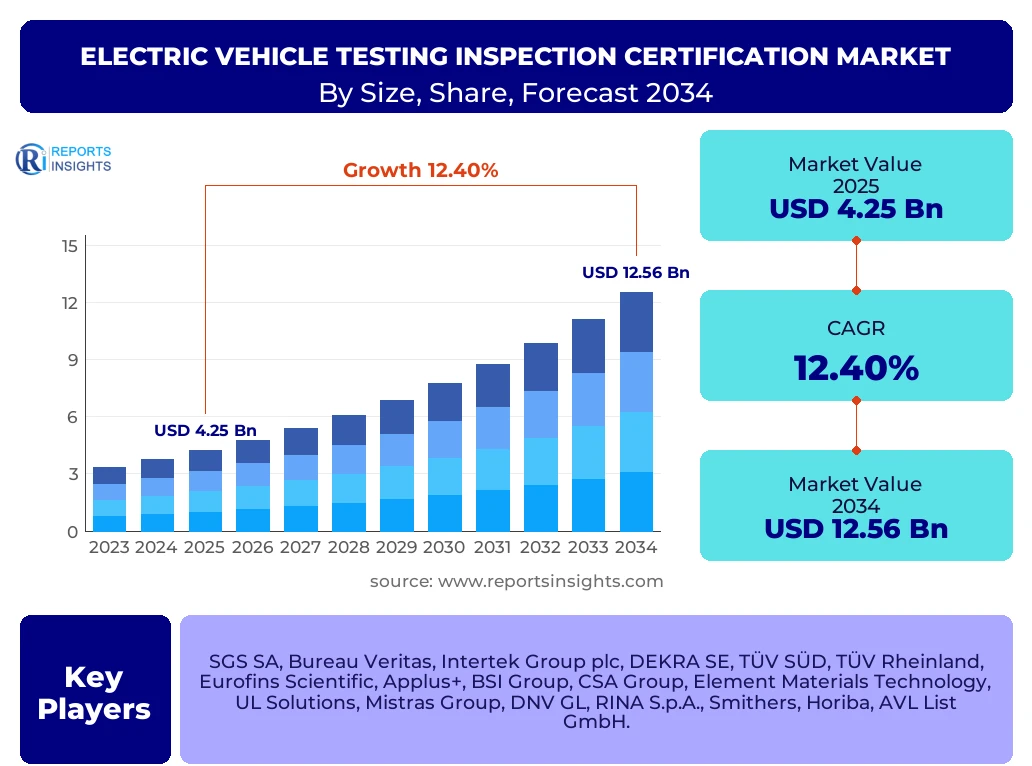
According to Reports Insights Consulting Pvt Ltd, The Electric Vehicle Testing Inspection Certification Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 12.4% between 2026 and 2034. The market is estimated at USD 4.82 Billion in 2026 and is projected to reach USD 12.56 Billion by the end of the forecast period in 2034.
Key Electric Vehicle Testing Inspection Certification Market Trends & Insights
The global transition toward sustainable mobility is the primary catalyst for the Electric Vehicle (EV) Testing, Inspection, and Certification (TIC) market. As automotive manufacturers shift their focus from internal combustion engines to electric powertrains, the complexity of safety and performance standards has increased exponentially. Users and stakeholders are increasingly inquiring about regional regulatory shifts, particularly the implementation of Euro 7 standards and the tightening of National Highway Traffic Safety Administration (NHTSA) guidelines. The market is currently seeing a significant shift toward automated testing systems and the integration of Artificial Intelligence (AI) to enhance the precision of battery health assessments and electromagnetic compatibility (EMC) testing. Competitive benchmarking reveals that leading players are expanding their specialized laboratory capacities to accommodate large-format battery packs and high-voltage charging systems.
- Largest Region: Asia-Pacific remains the dominant region, accounting for over 45% of the total market share, driven by massive production volumes in China, Japan, and South Korea.
- Fastest Growing Region: North America is projected to be the fastest-growing region during the forecast period due to rapid infrastructure expansion and the Inflation Reduction Act's impact on domestic manufacturing.
- Leading Segment by Share: The Testing segment currently holds the largest share of the market, as every new vehicle model requires rigorous validation of components such as battery cells, inverters, and thermal management systems.
- Emerging Trend: Cybersecurity certification for connected EVs is becoming a critical sub-segment as vehicles become increasingly software-defined and susceptible to digital threats.
Key Takeaways Electric Vehicle Testing Inspection Certification Market Size & Forecast
The Electric Vehicle Testing Inspection Certification market is undergoing a period of structural transformation, characterized by the decentralization of testing facilities and the adoption of virtual testing environments. Analysis of market queries indicates that stakeholders are highly concerned with the cost-efficiency of certification processes and the time-to-market for new EV models. The forecast suggests that the market will triple in size over the next decade as emerging economies in Southeast Asia and Latin America begin to modernize their automotive safety regulations. Furthermore, the rise of second-life battery applications is creating a whole new category for inspection and certification services, ensuring that used EV batteries meet safety standards for stationary energy storage.
- Dominant Country: China is the world leader in EV TIC activities, supported by a comprehensive ecosystem of battery manufacturers and domestic EV startups.
- Infrastructure Impact: The rapid rollout of DC fast-charging networks is driving a 15% year-on-year increase in the certification requirements for charging equipment and grid-interfacing systems.
- Safety Standards: Compliance with ISO 26262 (Functional Safety) and ISO/SAE 21434 (Cybersecurity) has become mandatory for market entry in most developed economies, significantly boosting service demand.
- Strategic Consolidation: Large TIC corporations are actively acquiring boutique engineering firms to gain specialized knowledge in hydrogen fuel cell testing and solid-state battery validation.
Electric Vehicle Testing Inspection Certification Market Drivers Analysis
The growth of the EV TIC market is fundamentally underpinned by the global mandate to decarbonize transportation. Governments worldwide are providing substantial subsidies and tax incentives for EV adoption, which in turn forces OEMs to accelerate their production cycles while adhering to stringent safety protocols. Additionally, the increasing consumer awareness regarding vehicle safety and the performance longevity of Lithium-ion batteries has made third-party certification a vital trust factor in the sales process. The emergence of autonomous driving features within electric platforms further complicates the testing landscape, requiring multidisciplinary inspection services that cover both electrical and software domains.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Government Zero-Emission Mandates | +4.2% | European Union and North America | 2025–2034 |
| Advancements in Battery Technology (Solid-State) | +2.8% | Japan, South Korea, and China | 2027–2034 |
| Expansion of Public Charging Infrastructure | +3.1% | Global (Especially India and USA) | 2025–2030 |
| Consumer Safety Perception and Brand Trust | +2.3% | Global | 2025–2034 |
Electric Vehicle Testing Inspection Certification Market Restraints Analysis
Despite the robust growth, the EV TIC market faces significant hurdles, primarily related to the lack of global harmonization in testing standards. Different regions often have conflicting requirements for battery crash testing and electromagnetic interference levels, which increases the cost and complexity for manufacturers operating internationally. Furthermore, the high capital expenditure required to establish state-of-the-art testing laboratories capable of handling high-voltage systems and hazardous materials acts as a barrier to entry for smaller service providers, potentially slowing down the overall pace of innovation in the certification space.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Cost of Specialized Testing Equipment | -1.5% | Developing Markets (MEA, LATAM) | 2025–2028 |
| Non-Harmonized International Standards | -2.1% | Global | 2025–2034 |
| Shortage of Skilled Technical Personnel | -1.2% | North America and Europe | 2025–2030 |
Electric Vehicle Testing Inspection Certification Market Opportunities Analysis
The evolving energy landscape offers numerous opportunities for the expansion of TIC services. The "Second-Life" battery market, where used EV batteries are repurposed for residential or industrial energy storage, requires rigorous testing for residual capacity and safety, representing a significant new revenue stream. Additionally, the development of Vehicle-to-Grid (V2G) technologies creates a need for complex certification processes that ensure seamless and safe energy transfer between vehicles and the electrical grid. As heavy-duty electric trucks and electric vertical takeoff and landing (eVTOL) aircraft enter the development phase, the demand for high-capacity testing services will likely skyrocket.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Second-Life Battery Validation | +3.5% | Europe and APAC | 2026–2034 |
| Cybersecurity and Software Update Audits | +2.9% | Global | 2025–2034 |
| V2G (Vehicle to Grid) Integration Testing | +2.4% | USA, Germany, and UK | 2027–2034 |
| Hydrogen Fuel Cell EV Certification | +1.8% | Japan and South Korea | 2028–2034 |
Electric Vehicle Testing Inspection Certification Market Challenges Impact Analysis
Technological volatility remains the most pressing challenge in the EV TIC sector. The rapid pace at which battery chemistries and power electronics evolve means that testing protocols can become obsolete within a matter of months. Ensuring the safety of increasingly dense battery packs during extreme thermal and mechanical stress tests requires highly sophisticated and dangerous testing environments. Moreover, the shift toward over-the-air (OTA) software updates by manufacturers means that a vehicle's performance characteristics can change after it has left the factory, challenging the traditional "once-and-done" model of certification and moving the industry toward a continuous monitoring framework.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Pace of Technological Obsolescence | -2.5% | Global | 2025–2034 |
| Hazardous Nature of High-Voltage Testing | -1.1% | Global | 2025–2034 |
| Regulatory Lags in Emerging Tech (OTA Updates) | -1.8% | Europe and North America | 2025–2029 |
Electric Vehicle Testing Inspection Certification Market - Updated Report Scope
This report provides a comprehensive examination of the global EV TIC market, covering the full spectrum of services including safety testing, environmental simulation, chemical analysis, and regulatory certification. The scope includes a detailed analysis of the supply chain for battery electric vehicles (BEVs), plug-in hybrid electric vehicles (PHEVs), and fuel cell electric vehicles (FCEVs). It evaluates the impact of global trade policies and environmental regulations on the TIC industry, providing stakeholders with actionable insights into future market dynamics. The report further explores the technological convergence of telematics and EV systems, offering a forward-looking perspective on the software-centric certification needs of the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.25 Billion |
| Market Forecast in 2034 | USD 12.56 Billion |
| Growth Rate | 12.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | SGS SA, Bureau Veritas, Intertek Group plc, DEKRA SE, TÜV SÜD, TÜV Rheinland, Eurofins Scientific, Applus+, BSI Group, CSA Group, Element Materials Technology, UL Solutions, Mistras Group, DNV GL, RINA S.p.A., Smithers, Horiba, AVL List GmbH. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Electric Vehicle Testing, Inspection, and Certification market is multifaceted, reflecting the complex engineering involved in modern electric mobility. The market is primarily divided by service type, where testing services dominate due to the need for physical validation of high-voltage components against thermal runaway and mechanical impact. The application segment is increasingly weighted toward battery and powertrain systems, given that the battery pack is the single most expensive and safety-critical component of an EV. Furthermore, the sourcing segment highlights a growing trend of outsourcing to specialized third-party TIC providers as OEMs seek to reduce internal overhead and leverage independent safety stamps to boost consumer confidence.
- By Service Type:
- Testing: Includes battery cell testing, electromagnetic compatibility (EMC), environmental stress testing, and functional safety.
- Inspection: Covers periodic vehicle inspections, supply chain audits, and manufacturing facility assessments.
- Certification: Involves granting official approval based on international standards like ISO, SAE, and UL.
- By Application:
- Battery and Powertrain: Focuses on energy density, thermal management, and power electronics efficiency.
- Charging Infrastructure: Ensuring safety and interoperability for AC/DC chargers and wireless charging pads.
- On-board Electronics: Testing infotainment, ADAS sensors, and telematics modules.
- By Vehicle Type:
- Battery Electric Vehicles (BEV): The largest segment by volume and testing intensity.
- Plug-in Hybrid Electric Vehicles (PHEV): Requires testing for both electrical and internal combustion components.
- Fuel Cell Electric Vehicles (FCEV): A niche but growing segment focused on high-pressure hydrogen safety.
Regional Highlights
- Asia-Pacific (APAC): Holding the largest market share, APAC is the epicenter of EV battery production. China alone accounts for a significant portion of global testing demand due to its aggressive "New Energy Vehicle" policies. The presence of major battery manufacturers like CATL and BYD necessitates localized, high-capacity TIC services.
- Europe: The region is characterized by the most stringent regulatory framework. The European Green Deal and upcoming Euro 7 standards drive continuous demand for high-end certification. Germany and France are the key hubs for automotive engineering and TIC innovation.
- North America: This region is the fastest-growing market, spurred by the revitalization of domestic manufacturing in the "Battery Belt." The focus here is heavily on large-scale infrastructure testing and cybersecurity standards driven by the US Department of Transportation.
- Latin America & MEA: While currently smaller in share, these regions are showing significant potential as they begin to adopt EV fleets for public transport, creating a new demand for localized inspection and periodic maintenance certification.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Electric Vehicle Testing Inspection Certification Market.- SGS SA
- Bureau Veritas
- Intertek Group plc
- DEKRA SE
- TÜV SÜD
- TÜV Rheinland
- Eurofins Scientific
- Applus+
- BSI Group
- CSA Group
- Element Materials Technology
- UL Solutions
- Mistras Group
- DNV GL
- RINA S.p.A.
- Smithers
- Horiba
- AVL List GmbH
Frequently Asked Questions
What is the primary driver for the Electric Vehicle TIC market?
The primary driver is the global government mandate to transition to zero-emission vehicles, which requires manufacturers to comply with evolving safety and performance standards for batteries and electric powertrains.
Which region currently leads the EV Testing and Certification market?
The Asia-Pacific region, led by China, currently holds the largest market share due to its dominant position in global EV production and battery manufacturing.
What are the key standards involved in EV certification?
Key standards include ISO 26262 for functional safety, ISO/SAE 21434 for cybersecurity, and UL 2580 for battery safety in electric vehicles.
How is the "Second-Life" battery market impacting TIC services?
The second-life battery market creates significant opportunities for TIC providers to develop new inspection and certification protocols to verify the safety and remaining capacity of used batteries for stationary storage applications.
What are the main challenges for TIC providers in the EV space?
The main challenges include the rapid pace of technological change, the lack of globally harmonized standards, and the high cost of building specialized laboratories for high-voltage testing.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted