Electric Motor Market
Electric Motor Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_704961 | Published On : October 11, 2026 |
Format : 


 | Author : Jonathan Sikka
Electric Motor Market Size
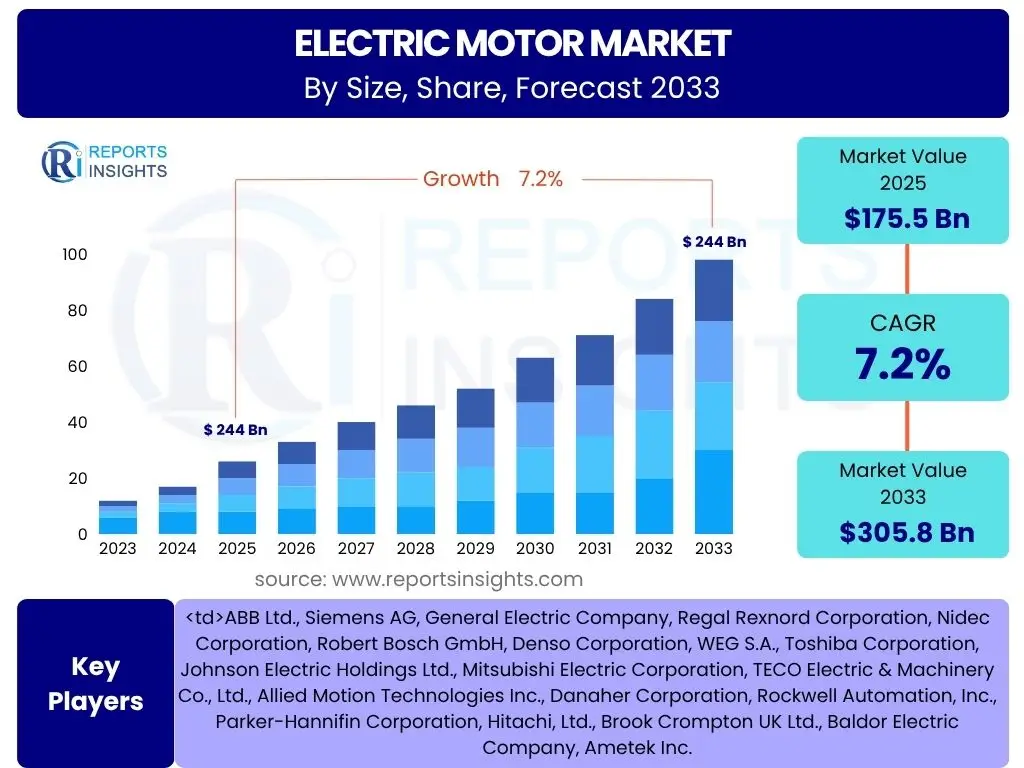
According to Reports Insights Consulting Pvt Ltd, The Electric Motor Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2025 and 2034. The market is estimated at USD 148.7 Billion in 2026 and is projected to reach USD 265.8 Billion by the end of the forecast period in 2034.
Key Electric Motor Market Trends & Insights
The global electric motor industry is undergoing a paradigm shift driven by the dual forces of industrial automation and the aggressive electrification of the transport sector. As nations commit to net-zero targets, the demand for high-efficiency motors, particularly those meeting IE4 and IE5 standards, has surged. Technological advancements in material science, such as the development of high-performance permanent magnets and the integration of Internet of Things (IoT) sensors for predictive maintenance, are redefining the competitive landscape. Current market intelligence suggests a significant migration toward brushless DC motors and permanent magnet synchronous motors (PMSM) due to their superior power-to-weight ratios and longevity in demanding applications.
- Largest Region: Asia Pacific remains the dominant regional market, accounting for over 45% of the total market share, fueled by massive industrial production in China, India, and Japan.
- Fastest Growing Region: North America is projected to witness the highest growth rate during the forecast period, driven by rapid electric vehicle (EV) infrastructure expansion and domestic manufacturing incentives.
- Largest Segment by Type: AC Motors continue to hold the largest market share owing to their widespread utility in industrial machinery and household appliances.
- Leading Application: The Automotive segment is the fastest-growing application category, primarily due to the global transition from internal combustion engines to electric powertrains.
Key Takeaways Electric Motor Market Size & Forecast
The trajectory of the electric motor market is fundamentally linked to the global energy transition. Industrial sectors are increasingly replacing legacy systems with energy-efficient variants to comply with stringent government regulations regarding carbon footprints. Furthermore, the convergence of robotics and motor technology is opening new revenue streams in the precision engineering and healthcare sectors. Strategic investments in domestic supply chains for rare earth metals and copper are becoming critical as companies seek to mitigate geopolitical risks and ensure long-term production stability.
- China is the world leader in both the production and consumption of electric motors, supported by a robust ecosystem for raw materials and downstream manufacturing.
- The adoption of IE4 (Super Premium Efficiency) motors is expected to become the industry standard by 2030, significantly reducing global electricity consumption in the industrial sector.
- Fractional Horsepower (FHP) motors are seeing increased penetration in the consumer electronics and medical device industries.
- Rising demand for HVAC systems in emerging economies is providing a steady growth floor for medium-voltage motor manufacturers.
Electric Motor Market Drivers Analysis
The primary catalyst for the electric motor market is the global shift toward electric mobility. Governments worldwide are implementing subsidies and tax credits to accelerate EV adoption, which directly translates to massive demand for traction motors. Additionally, the industrial sector is moving toward Industry 4.0, where automated production lines require sophisticated, controllable electric motors for precise movements and high-torque applications. This modernization of the global industrial base is essential for maintaining competitiveness in a high-cost energy environment.
Energy efficiency regulations represent another critical driver. Programs such as the European Union’s Ecodesign Directive and similar mandates in the United States and China are forcing manufacturers to phase out inefficient motor models. This regulatory pressure is creating a massive replacement market as industrial facilities upgrade their existing motor fleets to avoid penalties and reduce operational costs through lowered energy bills. The synergy between sustainability goals and economic efficiency is a powerful motivator for market expansion.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Electric Vehicle (EV) Proliferation | +2.8% | Global (Strong in China & USA) | 2025 - 2034 |
| Industrial Automation and Robotics Integration | +1.9% | Germany, Japan, South Korea | 2025 - 2030 |
| Stringent Energy Efficiency Standards (IE4/IE5) | +1.5% | European Union, North America | 2026 - 2034 |
| Modernization of Power Grids and Infrastructure | +1.2% | India, Brazil, Southeast Asia | 2027 - 2034 |
Electric Motor Market Restraints Analysis
Despite the optimistic growth projections, the electric motor market faces significant headwinds from the volatility of raw material prices. The production of high-efficiency motors relies heavily on copper, aluminum, and rare earth elements such as neodymium and dysprosium. Fluctuations in the prices of these commodities, often driven by geopolitical tensions or mining disruptions, can lead to unpredictable production costs and squeezed margins for manufacturers. This economic uncertainty can delay large-scale industrial projects and slow the pace of technology adoption.
Furthermore, the high initial cost of advanced, high-efficiency motors remains a barrier for small and medium-sized enterprises (SMEs). While these motors offer long-term savings through reduced energy consumption, the upfront capital expenditure can be prohibitive, especially in developing regions where access to low-cost financing is limited. This price sensitivity often leads to the continued use of older, less efficient motors, hindering the overall market’s transition toward more sustainable technologies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility (Rare Earths/Copper) | -1.1% | Global | 2025 - 2034 |
| High Initial Capital Expenditure for High-Efficiency Systems | -0.8% | Emerging Markets (ASEAN/Africa) | 2025 - 2029 |
Electric Motor Market Opportunities Analysis
The emergence of the "Smart Motor" ecosystem presents a transformative opportunity for market participants. By integrating sensors, wireless connectivity, and advanced analytics directly into the motor housing, manufacturers can offer value-added services such as real-time performance monitoring and predictive maintenance. This shift from a hardware-only model to a service-oriented business model allows companies to build long-term relationships with clients and generate recurring revenue through software updates and maintenance contracts.
Geographically, the expansion of the agricultural sector in Africa and Southeast Asia offers untapped potential. As these regions modernize their farming practices, there is an increasing demand for electric pumps, irrigation systems, and processing machinery, all of which require reliable and durable electric motors. Furthermore, the decentralized renewable energy sector, specifically small-scale wind and solar installations, is creating a niche market for specialized generators and motors designed for variable load conditions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of IoT and Predictive Analytics (Smart Motors) | +1.4% | USA, Germany, Japan | 2026 - 2034 |
| Agricultural Mechanization in Developing Economies | +0.9% | India, Vietnam, Nigeria | 2027 - 2034 |
| Specialized Motors for Renewable Energy Storage | +1.1% | Australia, Nordic Countries | 2026 - 2032 |
Electric Motor Market Challenges Impact Analysis
One of the most pressing challenges is the talent gap in specialized electrical engineering and power electronics. As motors become more complex, requiring advanced control algorithms and integration with digital twins, the industry faces a shortage of skilled professionals capable of designing and maintaining these next-generation systems. This human capital constraint can lead to longer R&D cycles and slower time-to-market for innovative products, potentially allowing competitors to gain an advantage.
Additionally, the proliferation of counterfeit and low-quality motors in the global market poses a threat to established brands. These substandard products often bypass safety and efficiency regulations, competing solely on price. For legitimate manufacturers, this necessitates increased spending on brand protection and customer education to emphasize the total cost of ownership and safety risks associated with non-compliant hardware. Navigating different regional standards and certification requirements also adds a layer of administrative complexity for global players.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Workforce in Power Electronics | -0.6% | North America, Europe | 2025 - 2034 |
| Proliferation of Low-Quality Counterfeit Products | -0.5% | Global (Impactful in APAC/LATAM) | 2025 - 2030 |
Electric Motor Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis of the global electric motor market, covering historical data from 2020 and providing a detailed forecast through 2034. The scope includes a multi-dimensional segmentation by motor type, output power, voltage, and application across six major geographic regions. The analysis incorporates the latest technological trends, regulatory shifts, and competitive dynamics to provide stakeholders with actionable insights for strategic decision-making and investment planning.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 138.5 Billion |
| Market Forecast in 2034 | USD 265.8 Billion |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | ABB Ltd., Siemens AG, Nidec Corporation, WEG S.A., Wolong Electric Group Co., Ltd., Regal Rexnord Corporation, Rockwell Automation, Inc., Emerson Electric Co., Bosch Rexroth AG, Mitsubishi Electric Corporation, Danfoss A/S, TECO Electric & Machinery Co., Ltd., Allied Motion Technologies Inc., AMETEK, Inc., Toshiba Corporation, Denso Corporation, Johnson Electric Holdings Limited, Faulhaber Group. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the electric motor market reflects the diverse operational requirements across different industries. AC motors dominate the industrial landscape due to their robustness and ease of maintenance, whereas DC motors, particularly brushless variants, are seeing explosive growth in applications requiring precise speed and torque control. The categorization by output power allows for a distinction between high-torque industrial drives and small-scale precision motors used in robotics and medical devices.
- By Motor Type:
- AC Motors (Induction Motors, Synchronous Motors)
- DC Motors (Brushed DC Motors, Brushless DC Motors)
- Hermetic Motors (Used in refrigeration and compressor units)
- By Output Power:
- Fractional Horsepower (FHP)
- Integral Horsepower (IHP)
- By Voltage:
- Low Voltage Motors
- Medium Voltage Motors
- High Voltage Motors
- By Application:
- Automotive and Transportation (Traction motors, power steering, window lifts)
- Industrial Machinery (Pumps, fans, compressors, conveyors)
- HVAC (Heating, ventilation, and air conditioning systems)
- Consumer Appliances (Washing machines, vacuum cleaners, refrigerators)
- Aerospace and Defense (Actuators, flight controls)
- Healthcare (Surgical tools, laboratory equipment)
Regional Highlights
- Asia Pacific: Holds the largest market share (over 45%) and is the global manufacturing hub. China is the primary contributor, supported by massive investments in EV production and industrial automation. India is emerging as a critical growth node due to its "Make in India" initiative and rural electrification projects.
- North America: Projected as the fastest-growing region with a CAGR of approximately 8.1%. This growth is driven by the rapid adoption of electric vehicles, the presence of major tech innovators, and government incentives for renewable energy infrastructure.
- Europe: A mature market focused on energy efficiency and sustainability. Stringent EU regulations on carbon emissions and the early adoption of IE4/IE5 standards make it a leader in high-end, premium-efficiency motor technology.
- Latin America & MEA: These regions are witnessing steady growth through the expansion of the mining and oil & gas sectors. Brazil and South Africa are key markets for large-scale industrial motors used in extraction and processing.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Electric Motor Market.- ABB Ltd.
- Siemens AG
- Nidec Corporation
- WEG S.A.
- Wolong Electric Group Co., Ltd.
- Regal Rexnord Corporation
- Rockwell Automation, Inc.
- Emerson Electric Co.
- Bosch Rexroth AG
- Mitsubishi Electric Corporation
- Danfoss A/S
- TECO Electric & Machinery Co., Ltd.
- Allied Motion Technologies Inc.
- AMETEK, Inc.
- Toshiba Corporation
- Denso Corporation
- Johnson Electric Holdings Limited
- Faulhaber Group
- Maxon Motor AG
- Yaskawa Electric Corporation
Frequently Asked Questions
What is the current market size and projected growth of the Electric Motor Market?
The market is estimated at USD 148.7 Billion in 2026 and is projected to reach USD 265.8 Billion by 2034, growing at a steady CAGR of 7.4% during the forecast period.
Which motor type is expected to dominate the market share?
AC Motors currently dominate due to their widespread use in industrial applications. However, Brushless DC (BLDC) and Permanent Magnet Synchronous Motors (PMSM) are the fastest-growing segments, especially in the automotive and high-precision electronics sectors.
What are the key factors driving the growth in North America?
North American growth is primarily driven by the aggressive transition to electric mobility (EVs), significant government subsidies for green energy, and the modernization of industrial manufacturing plants through robotics and AI integration.
How are energy efficiency regulations impacting the market?
Global regulations like the IE4/IE5 standards are forcing a transition away from legacy induction motors. This creates a high-volume replacement market where manufacturers must innovate to provide higher efficiency and lower operational costs.
What are the major challenges facing the Electric Motor Market?
The primary challenges include the volatility of raw material prices (such as copper and rare earth magnets), a shortage of specialized electrical engineers, and the entry of low-cost, substandard products in emerging markets.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
