Edge Computing Market
Edge Computing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711166 | Published On : October 14, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Edge Computing Market Size
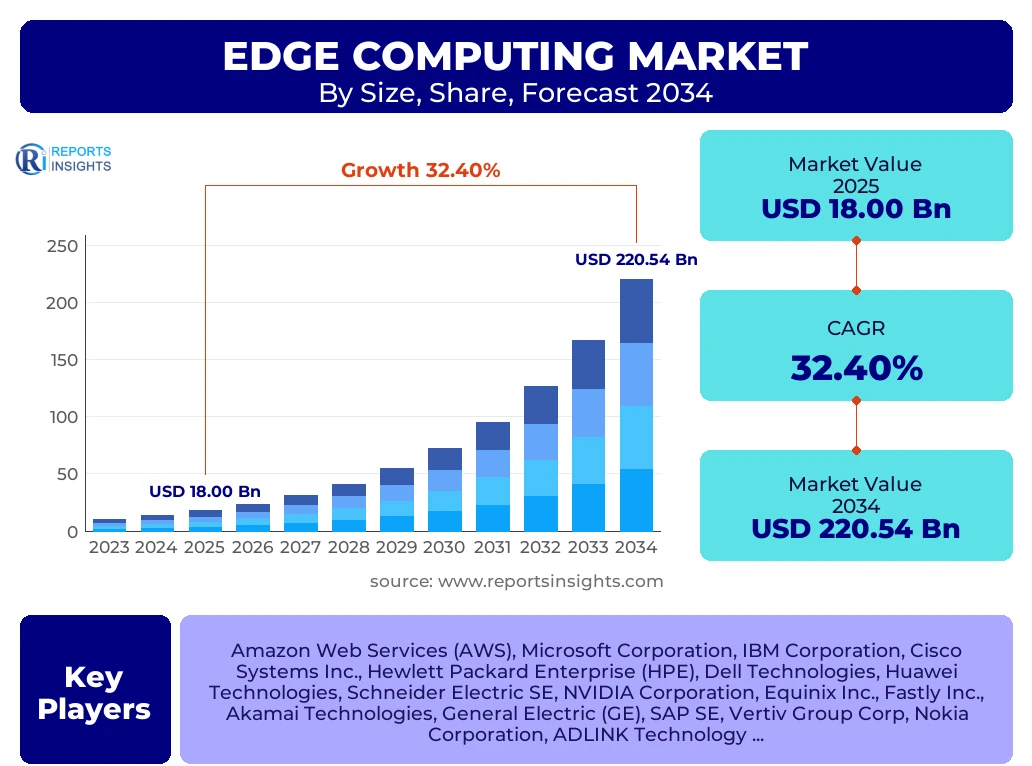
According to Reports Insights Consulting Pvt Ltd, The Edge Computing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 32.4% between 2025 and 2034. The market is estimated at USD 23.83 Billion in 2026 and is projected to reach USD 220.54 Billion by the end of the forecast period in 2034.
Key Edge Computing Market Trends & Insights
The global edge computing landscape is undergoing a radical transformation driven by the necessity for real-time data processing and the proliferation of internet-connected devices. Modern enterprises are increasingly shifting away from centralized cloud architectures toward decentralized frameworks to mitigate latency issues and optimize bandwidth utilization. This shift is particularly evident in industrial automation and autonomous systems where millisecond delays can lead to operational failures. Furthermore, the convergence of artificial intelligence with edge infrastructure, commonly referred to as Edge AI, is enabling sophisticated analytics to occur locally on devices, reducing the reliance on constant backbone connectivity and improving data privacy. Competitive benchmarking indicates that leading providers are focusing on integrated hardware-software stacks that offer seamless orchestration across heterogeneous environments, from micro-datacenters to ruggedized IoT gateways.
Regional insights suggest that while North America currently maintains the highest market valuation due to early adoption of 5G and massive investments in Industry 4.0, the Asia-Pacific region is emerging as the fastest-growing corridor. This rapid expansion is fueled by massive urbanization, government-led smart city initiatives in China and India, and a robust manufacturing sector that requires localized computing power. Segment-specific data reveals that the hardware component currently commands the largest revenue share, though services and software are anticipated to witness higher growth rates as the market matures and the complexity of managing distributed edge nodes increases.
- Largest Region: North America remains the dominant revenue contributor, holding approximately 38% of the global market share in 2025.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period due to rapid industrial digitalization.
- Leading Segment by Share: Hardware components, including edge gateways and sensors, represent the largest market segment by value.
- Dominant Application: Industrial Internet of Things (IIoT) is the primary driver for edge computing adoption across the manufacturing vertical.
Key Takeaways Edge Computing Market Size & Forecast
The trajectory of the edge computing market is defined by its ability to bridge the gap between physical operations and digital intelligence. Analysts observe that the market is moving past the experimental phase into a deployment-heavy cycle, where ROI is clearly linked to operational efficiency and reduced cloud egress costs. The forecast suggests a sustained upward trend as 5G network slicing becomes more prevalent, allowing for dedicated low-latency channels for critical edge applications. Stakeholders are prioritizing interoperability and standardized protocols to manage the diverse ecosystem of edge devices, ensuring that data can flow securely and efficiently between the edge, the fog, and the core cloud layers.
- Unprecedented Growth: The market is set to expand nearly tenfold over the next decade, driven by the exponential volume of data generated by 15 billion plus IoT devices.
- Strategic Regional Hubs: The United States, China, and Germany are identified as the three most critical national markets for edge infrastructure investment.
- Vertical Integration: Manufacturing, Healthcare, and Retail are the top three sectors expected to realize the most significant productivity gains from edge deployments.
- Infrastructure Evolution: A significant transition from centralized data centers to localized micro-datacenters is reshaping the global telecommunications and IT services landscape.
Edge Computing Market Drivers Analysis
The fundamental driver for the edge computing market is the mounting pressure on traditional cloud architectures caused by the sheer volume of data generated at the network periphery. As businesses integrate more sensors and smart devices into their operations, the costs and latency associated with transferring all data to a central server have become prohibitive. Edge computing addresses this by filtering and processing data locally, only sending relevant insights to the cloud. This is critical for time-sensitive applications such as autonomous driving and remote robotic surgery, where immediate response is mandatory for safety and efficacy.
Additionally, the global rollout of 5G infrastructure acts as a powerful catalyst. 5G provides the high-speed, high-bandwidth connectivity required to link a vast number of edge nodes simultaneously. This synergy allows for the creation of private 5G networks in industrial settings, where edge computing provides the localized processing power for real-time analytics and machine-to-machine communication. The focus on data sovereignty and privacy also drives adoption, as sensitive information can be kept within local jurisdictions or on-premise, minimizing the risk of interception during transit.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Proliferation of IoT Devices | +8.2% | Global | 2025 - 2034 |
| Expansion of 5G Networks | +7.5% | North America, Europe, China | 2025 - 2030 |
| Need for Low Latency in AI Applications | +6.8% | Japan, USA, South Korea | 2026 - 2034 |
| Rising Demand for Real-time Analytics | +5.4% | Western Europe, India | 2025 - 2034 |
Edge Computing Market Restraints Analysis
Despite its potential, the market faces significant restraints, primarily regarding security and the physical vulnerability of edge nodes. Unlike centralized data centers that benefit from rigorous physical and digital security perimeters, edge devices are often located in remote or public areas, making them susceptible to tampering and cyber-attacks. The distributed nature of the network also expands the attack surface, requiring complex and expensive security protocols to maintain integrity across thousands of disparate nodes.
Furthermore, the high initial capital expenditure required for deploying and maintaining edge hardware can be a deterrent for small and medium-sized enterprises. There is also a notable lack of standardized communication protocols among various hardware vendors, which creates interoperability challenges. Organizations often find themselves locked into proprietary ecosystems, complicating the integration of new technologies and increasing the long-term total cost of ownership. These factors combined can slow the pace of mass adoption in price-sensitive markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Security Vulnerabilities and Data Privacy | -4.2% | Global (High impact in EU) | 2025 - 2034 |
| Lack of Standardized Architecture | -3.5% | Developing Markets | 2025 - 2028 |
| High Initial Implementation Costs | -2.8% | Latin America, MEA | 2025 - 2030 |
Edge Computing Market Opportunities Analysis
The integration of generative AI and machine learning at the edge represents a massive opportunity for market expansion. By enabling devices to not only process data but to learn and adapt in real-time, businesses can develop hyper-personalized consumer experiences and predictive maintenance models that were previously impossible. In the retail sector, for instance, edge-powered computer vision can track inventory and analyze customer behavior instantly, optimizing store layouts and supply chains without the latency of cloud processing.
Moreover, the rise of autonomous vehicles and smart infrastructure creates a fertile ground for edge computing providers. V2X (Vehicle-to-Everything) communication requires localized processing to ensure safety and traffic optimization. As cities transition into "Smart Cities," the demand for edge nodes to manage traffic lights, utility grids, and public safety surveillance will skyrocket. There is also a significant opportunity in the "Edge-as-a-Service" (EaaS) model, which allows enterprises to scale their edge capabilities through a subscription-based approach, lowering the barrier to entry and fostering innovation.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Edge AI and Local Machine Learning | +9.3% | USA, China, UK | 2026 - 2034 |
| Smart City and Autonomous Infrastructure | +7.1% | APAC, GCC Countries | 2027 - 2034 |
| Edge-as-a-Service (EaaS) Models | +5.9% | Global | 2025 - 2034 |
Edge Computing Market Challenges Impact Analysis
The primary challenge for the edge computing market is the management and orchestration of a highly distributed and heterogeneous environment. Managing software updates, monitoring health, and ensuring consistent performance across thousands of geographically dispersed nodes is a monumental task for IT departments. The shortage of skilled professionals who understand the nuances of both traditional IT and operational technology (OT) further exacerbates this challenge, potentially leading to sub-optimal deployments and increased downtime.
Environmental factors and power consumption also present significant hurdles. Edge devices are often deployed in harsh environments—such as oil rigs or manufacturing floors—where temperature fluctuations and vibration can cause hardware failure. Additionally, as the number of edge nodes grows, the cumulative energy consumption becomes a concern for organizations striving to meet sustainability goals. Designing energy-efficient hardware and cooling solutions for compact edge enclosures is a technical challenge that manufacturers must address to maintain market momentum.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complexity in Lifecycle Management | -3.1% | Global | 2025 - 2034 |
| Energy Consumption and Sustainability | -2.4% | Europe, North America | 2026 - 2034 |
| Hardware Durability in Harsh Conditions | -1.9% | Global (Industrial Segments) | 2025 - 2034 |
Edge Computing Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis of the global edge computing ecosystem, covering the period from 2020 through 2034. It examines the market through various lenses, including hardware components, software platforms, managed services, and industry-specific applications. The scope encompasses detailed geographic breakdowns and competitive profiles of the players shaping the future of decentralized computing. The report focuses on the intersection of edge technology with AI, 5G, and IoT, providing actionable insights for strategic decision-making in an increasingly connected world.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 18.00 Billion |
| Market Forecast in 2034 | USD 220.54 Billion |
| Growth Rate | 32.4% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Amazon Web Services (AWS), Microsoft Corporation, IBM Corporation, Cisco Systems Inc., Hewlett Packard Enterprise (HPE), Dell Technologies, Huawei Technologies, Schneider Electric SE, NVIDIA Corporation, Equinix Inc., Fastly Inc., Akamai Technologies, General Electric (GE), SAP SE, Vertiv Group Corp, Nokia Corporation, ADLINK Technology, Litmus Automation, FogHorn Systems, Siemens AG. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The edge computing market is segmented based on component, application, and vertical to provide a granular understanding of growth drivers. Currently, the hardware segment dominates as organizations build out the necessary physical infrastructure to support decentralized processing. However, as the infrastructure stabilizes, software and services are expected to gain a larger share of the total market value. The application of edge computing in the Industrial Internet of Things (IIoT) is particularly noteworthy, as it enables the real-time processing required for high-precision manufacturing and predictive maintenance.
- By Component: Hardware (including edge nodes, gateways, and servers), Software (edge computing platforms and security software), and Services (consulting, maintenance, and managed services).
- By Application: Smart Cities, Industrial IoT (IIoT), Remote Monitoring, Content Delivery Networks (CDN), AR/VR, Autonomous Vehicles, and Healthcare.
- By Organization Size: Large Enterprises and Small & Medium-sized Enterprises (SMEs).
- By Vertical: Manufacturing, Energy & Utilities, Government & Defense, Healthcare & Life Sciences, Retail & Consumer Goods, Transportation & Logistics, and IT & Telecommunications.
Regional Highlights
- North America: The largest market globally, characterized by high adoption rates of advanced technologies and significant investment from tech giants like AWS and Microsoft.
- Asia-Pacific: The fastest-growing region, driven by massive digital transformation in China, India, and Southeast Asia, alongside a strong manufacturing base.
- Europe: A significant market with a strong focus on data privacy (GDPR) and industrial automation, particularly in Germany and the UK.
- Middle East & Africa: Growing interest in smart city projects (e.g., NEOM) and modernization of the oil and gas sector through edge analytics.
- Latin America: Developing market with increasing focus on improving telecommunications infrastructure and agricultural technology (AgTech).

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Edge Computing Market.- Amazon Web Services (AWS)
- Microsoft Corporation
- IBM Corporation
- Cisco Systems, Inc.
- Hewlett Packard Enterprise (HPE)
- Dell Technologies
- Huawei Technologies Co., Ltd.
- Schneider Electric SE
- NVIDIA Corporation
- Equinix, Inc.
- Fastly, Inc.
- Akamai Technologies
- General Electric (GE Digital)
- SAP SE
- Vertiv Group Corp
- Nokia Corporation
- ADLINK Technology Inc.
- Litmus Automation
- FogHorn Systems (Johnson Controls)
- Siemens AG
Frequently Asked Questions
What is the primary difference between cloud computing and edge computing?
Cloud computing involves processing data in a centralized data center located far from the source, whereas edge computing processes data locally on devices or near-site gateways. This proximity reduces latency and bandwidth usage, making it ideal for real-time applications.
How does 5G impact the growth of the edge computing market?
5G acts as a critical enabler by providing the high-speed, low-latency connectivity required to handle the massive data flow between edge devices and the network. It allows for more complex and denser deployments of edge nodes in industrial and urban environments.
Which industries are adopting edge computing the fastest?
Manufacturing (IIoT), Healthcare (remote patient monitoring), and Energy (smart grids) are the leading sectors. Retail and Transportation are also seeing rapid adoption for inventory management and autonomous vehicle systems.
What are the main security risks associated with edge computing?
The main risks include a larger attack surface due to the distributed nature of the network, physical vulnerability of remote devices, and the difficulty of maintaining consistent security patches across thousands of disparate hardware nodes.
What is the projected market value of Edge Computing by 2034?
The global Edge Computing market is projected to reach approximately USD 220.54 Billion by 2034, growing at a CAGR of 32.4% from 2025.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
