Drug Device Combination Product Market
Drug Device Combination Product Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_709070 | Published On : October 06, 2026 |
Format : 


 | Author : Erika Grotto
Drug Device Combination Product Market Size
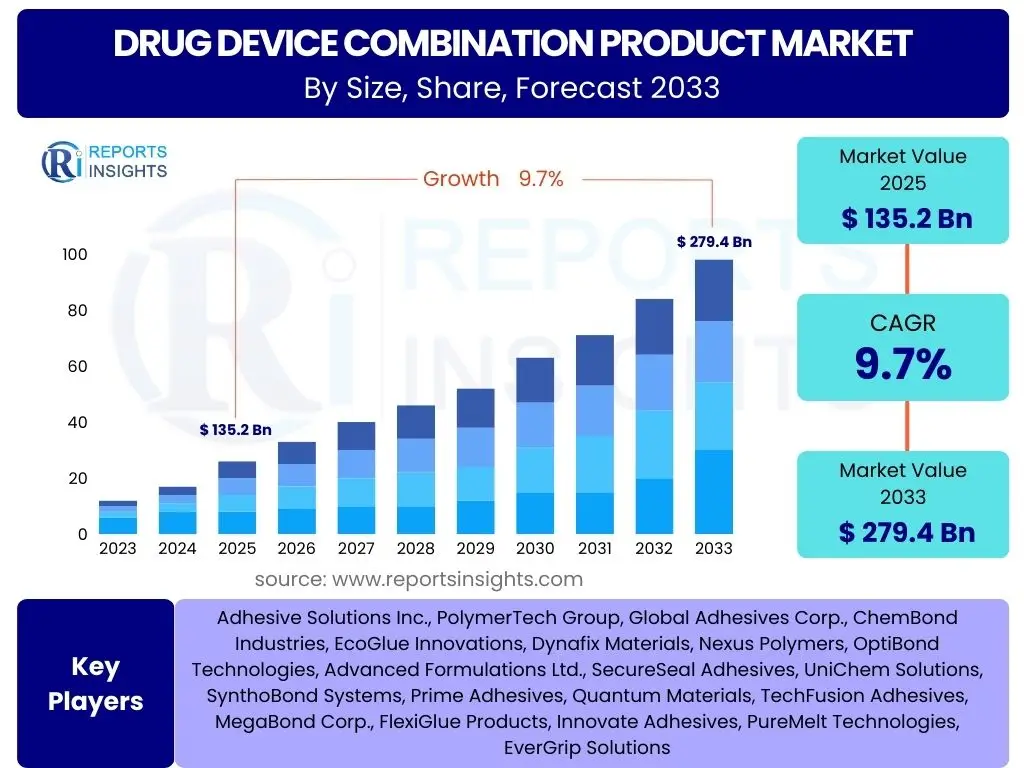
According to Reports Insights Consulting Pvt Ltd, The Drug Device Combination Product Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.9% between 2025 and 2034. The market is estimated at USD 156.42 Billion in 2026 and is projected to reach USD 308.75 Billion by the end of the forecast period in 2034.
The global Drug Device Combination Product market represents a sophisticated intersection of pharmacology and medical engineering, designed to enhance the therapeutic efficacy and safety of medical treatments. These products, which include prefilled syringes, drug-eluting stents, and inhalers, are increasingly favored due to their ability to provide targeted delivery and improved patient compliance. As the global healthcare landscape shifts toward personalized medicine and home-based care, the demand for integrated delivery systems that can be easily administered by patients or non-clinical caregivers has surged. This market is characterized by intense research and development activities, aimed at integrating smart technologies such as sensors and connectivity features to monitor adherence and physiological responses in real-time.
The growth trajectory is further supported by the rising prevalence of chronic conditions such as diabetes, cardiovascular diseases, and respiratory disorders, which require long-term and often complex medication regimens. In response, pharmaceutical and medical device companies are entering into strategic collaborations to streamline the regulatory approval processes, which are traditionally complex due to the dual nature of these products. Technological advancements in miniaturization and biocompatible materials are expanding the possibilities for implantable combination products, offering new hope for therapeutic areas like oncology and neurology. Consequently, the market is poised for significant expansion, driven by both clinical necessity and the continuous evolution of delivery technologies.
Key Drug Device Combination Product Market Trends & Insights
The Drug Device Combination Product market is undergoing a transformative phase characterized by the integration of digital health technologies and a pivot toward patient-centric designs. Analysts observe that the convergence of medical devices with advanced biologics is creating a new frontier for therapeutic interventions, particularly in the realm of autoimmune diseases and oncology. Large-scale investments are being directed toward smart inhalers and connected autoinjectors that sync with smartphone applications, providing patients and clinicians with actionable data. Furthermore, the regulatory environment is becoming more structured, with agencies like the FDA and EMA providing clearer pathways for constituent parts, which facilitates faster time-to-market for innovative products. Competitive benchmarking reveals that market leaders are focusing on differentiation through device ergonomics and sustainability, particularly in reducing the environmental footprint of disposable delivery systems.
- Largest Region: North America remains the dominant regional market, holding over 40% of the global share, driven by high healthcare expenditure and early adoption of advanced delivery technologies.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, fueled by expanding healthcare infrastructure and a massive patient pool in China and India.
- Largest Segment by Type: Transdermal and Transmucosal delivery systems currently hold the largest market share due to their non-invasive nature and high patient preference.
- Leading Application: The diabetes management segment represents the highest revenue generator, supported by the widespread use of insulin pens and pumps.
- Emerging Trend: The rise of bio-resorbable drug-eluting stents is a significant trend in the interventional cardiology sub-sector, reducing long-term complications.
Key Takeaways Drug Device Combination Product Market Size & Forecast
The global market for Drug Device Combination Product is entering a decade of sustained growth, underpinned by the necessity for precision dosing and the global rise of geriatric populations. Strategic analysis indicates that the shift from hospital-centric to home-centric care models is the primary catalyst for the adoption of self-administration devices. Industry stakeholders are increasingly prioritizing the development of platforms that can accommodate various drug formulations, thereby reducing the overhead costs associated with dedicated device development for every new drug. The forecast period will likely see a surge in M&A activities as pharmaceutical giants seek to acquire niche device manufacturers to secure their delivery pipelines and enhance their market position against biosimilar competition.
- Dominant Market Position: The United States continues to lead the global market in terms of value, supported by a robust reimbursement framework and a high concentration of key industry players.
- Therapeutic Growth: The oncology segment is expected to see the most rapid adoption of combination products for localized chemotherapy delivery, minimizing systemic side effects.
- Innovation Focus: Development of "Smart" combination products with IoT capabilities is becoming a standard requirement for next-generation product launches.
- Regulatory Synergy: Improved alignment between the Center for Drug Evaluation and Research (CDER) and the Center for Devices and Radiological Health (CDRH) is expected to shorten approval timelines.
- Economic Impact: The cost-effectiveness of combination products in reducing hospital readmission rates is a major factor driving procurement decisions in public health systems.
Drug Device Combination Product Market Drivers Analysis
The market is primarily driven by the escalating demand for minimally invasive drug delivery systems and the increasing complexity of modern biopharmaceuticals, which often require specialized devices for effective administration. The focus on improving patient adherence is a critical factor, as combination products simplify the administration process, particularly for elderly patients with multiple comorbidities.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Chronic Disease Prevalence | +2.4% | Global / Highly relevant in Emerging Markets | 2025 - 2034 |
| Advancements in Biologics and Large Molecule Delivery | +1.8% | North America and Europe | 2025 - 2030 |
| Shift Towards Home Healthcare and Self-Administration | +2.1% | Global / Developed Economies | 2026 - 2034 |
| Technological Integration (IoT & Sensors) | +1.5% | United States, Germany, Japan | 2027 - 2034 |
Drug Device Combination Product Market Restraints Analysis
Despite the growth, the market faces significant hurdles related to the stringent and often bifurcated regulatory pathways required for products that function as both a drug and a device. High development costs and the risk of product recalls due to mechanical failures or drug-device incompatibility also act as significant barriers for new entrants and mid-sized firms.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complex Regulatory Approval Frameworks | -1.2% | EU (MDR Regulations) and USA | 2025 - 2028 |
| High Initial R&D and Manufacturing Costs | -0.9% | Developing Nations | 2025 - 2034 |
| Safety Concerns and Product Recall Risks | -0.7% | Global | 2025 - 2034 |
Drug Device Combination Product Market Opportunities Analysis
The emergence of biosimilars presents a massive opportunity for device manufacturers to partner with pharmaceutical firms to create differentiated combination products that provide a competitive edge. Additionally, the expansion of healthcare access in the APAC and Latin American regions offers a fertile ground for the deployment of cost-effective, high-volume combination devices such as prefilled syringes and basic inhalers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion in Biosimilar Delivery Platforms | +2.5% | Europe and Asia-Pacific | 2026 - 2034 |
| Growth of Targeted Oncology Delivery Systems | +1.9% | Global | 2025 - 2034 |
| Personalized Medicine & Wearable Injectors | +2.2% | North America and Western Europe | 2028 - 2034 |
Drug Device Combination Product Market Challenges Impact Analysis
One of the primary challenges is maintaining the stability of the drug constituent within the device over the product's shelf life, as interactions between the drug and the device materials can lead to degradation. Furthermore, global supply chain disruptions for specialty plastics and electronic components for smart devices continue to pose a risk to production timelines and cost management.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Material Compatibility and Drug Stability Issues | -0.8% | Global | 2025 - 2034 |
| Supply Chain Volatility for Raw Materials | -0.6% | Global | 2025 - 2027 |
| Sustainability and Medical Waste Management | -0.5% | European Union | 2026 - 2034 |
Drug Device Combination Product Market - Updated Report Scope
This report provides an exhaustive analysis of the global Drug Device Combination Product market, covering all major product types, therapeutic applications, and geographic regions. It evaluates the impact of technological convergence, regulatory shifts, and economic factors on the market trajectory from 2025 to 2034. The scope includes a detailed assessment of the competitive landscape, identifying key strategies employed by top-tier players to maintain market leadership and capture emerging opportunities in high-growth segments.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 143.64 Billion |
| Market Forecast in 2034 | USD 308.75 Billion |
| Growth Rate | 8.9% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Abbott Laboratories, Medtronic plc, GlaxoSmithKline plc (GSK), Johnson & Johnson, Novartis AG, Becton, Dickinson and Company (BD), Boston Scientific Corporation, Terumo Corporation, Bayer AG, AstraZeneca, Sanofi S.A., Pfizer Inc., Amgen Inc., F. Hoffmann-La Roche Ltd, Teva Pharmaceutical Industries Ltd., Eli Lilly and Company, Novo Nordisk A/S, Boehringer Ingelheim International GmbH. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Drug Device Combination Product market reflects the diverse clinical requirements and the varied technological platforms used to deliver therapeutics. The injectables segment, particularly prefilled syringes and autoinjectors, is witnessing the fastest expansion due to the rapid growth of the biologics market. Inhalational products represent a mature yet innovating segment, with a focus on improving aerosolization and patient breathing coordination. Transdermal systems are evolving from simple patches to sophisticated microneedle arrays that can deliver larger molecules across the skin barrier. Therapeutic segmentation shows that diabetes and respiratory care remain the foundational pillars, while oncology and neurology are emerging as the next high-value frontiers for combination products.
- By Product Type:
- Transdermal: Microneedle patches, traditional drug-in-adhesive patches.
- Inhalational: Metered-dose inhalers (MDIs), Dry powder inhalers (DPIs), and advanced nebulizer systems.
- Injectable: Prefilled syringes (PFS), autoinjectors, wearable large-volume injectors, and needle-free injectors.
- Drug-Eluting Stents: Coronary and peripheral stents.
- Others: Ocular inserts, drug-coated balloons, and medicated dressings.
- By Application:
- Diabetes: Insulin delivery systems.
- Respiratory: Therapy for asthma, chronic obstructive pulmonary disease (COPD), and cystic fibrosis.
- Cardiovascular: Stents for atherosclerosis and infusion pumps for heart failure medications.
- Oncology: Targeted chemotherapy delivery and implantable ports.
- Neurology: Infusion pumps for Parkinson’s and spasticity management.
- By End-User:
- Hospitals: High-complexity implantable devices and emergency care delivery.
- Homecare: The primary growth driver for self-administration devices like pens and inhalers.
- Clinics: Specialized settings for chronic disease monitoring and outpatient procedures.
Regional Highlights
- North America: Currently the largest market by value. This dominance is attributed to a highly advanced healthcare system, favorable reimbursement policies (such as Medicare/Medicaid in the U.S.), and significant R&D spending by resident pharmaceutical giants.
- Europe: Represents a significant market share, characterized by stringent safety regulations and a strong emphasis on the adoption of biosimilars, which often utilize combination devices for differentiation.
- Asia-Pacific: Identified as the fastest-growing region. Rapid urbanization, increasing healthcare literacy, and government initiatives to improve medical infrastructure in China, India, and South Korea are driving demand for modern delivery systems.
- Latin America: Showing steady growth driven by the rising prevalence of metabolic disorders and the entry of global pharmaceutical players into Brazil and Mexico.
- Middle East & Africa: A growing market with increased focus on improving access to essential medicines and specialized treatments for chronic conditions in Gulf Cooperation Council (GCC) countries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Drug Device Combination Product Market.- Abbott Laboratories
- Medtronic plc
- GlaxoSmithKline plc (GSK)
- Johnson & Johnson
- Novartis AG
- Becton, Dickinson and Company (BD)
- Boston Scientific Corporation
- Terumo Corporation
- Bayer AG
- AstraZeneca
- Sanofi S.A.
- Pfizer Inc.
- Amgen Inc.
- F. Hoffmann-La Roche Ltd
- Teva Pharmaceutical Industries Ltd.
- Eli Lilly and Company
- Novo Nordisk A/S
- Boehringer Ingelheim International GmbH
- Sensile Medical (Gerresheimer AG)
- West Pharmaceutical Services, Inc.
Frequently Asked Questions
What are drug-device combination products?
Drug-device combination products are medical products that consist of two or more regulated components (a drug and a device, a biological product and a device, a drug and a biological product, or all three) that are physically, chemically, or otherwise combined as a single entity.
What is driving the growth of the drug-device combination products market?
The primary drivers include the rising prevalence of chronic diseases, the shift toward home-based healthcare and self-administration, advancements in biotechnology requiring specialized delivery, and the increasing need for patient adherence and safety.
Which product segment holds the largest share in the market?
The injectable products segment, specifically prefilled syringes and autoinjectors, currently holds a dominant share due to the proliferation of biologic therapies that require parenteral administration.
What are the regulatory challenges for these products?
Regulatory challenges stem from the need to satisfy requirements for both pharmaceutical and medical device standards. In the U.S., this involves coordination between the FDA's CDER and CDRH, while in the EU, it involves adherence to the Medical Device Regulation (MDR).
Which region is expected to grow the fastest through 2034?
The Asia-Pacific region is expected to be the fastest-growing market due to improving healthcare infrastructure, a large patient population, and increasing investments in the pharmaceutical and medical device sectors across China and India.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
