Distribution Transformer Market
Distribution Transformer Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711413 | Published On : October 31, 2026 |
Format : 


 | Author : Seema Bhateja
Distribution Transformer Market Size
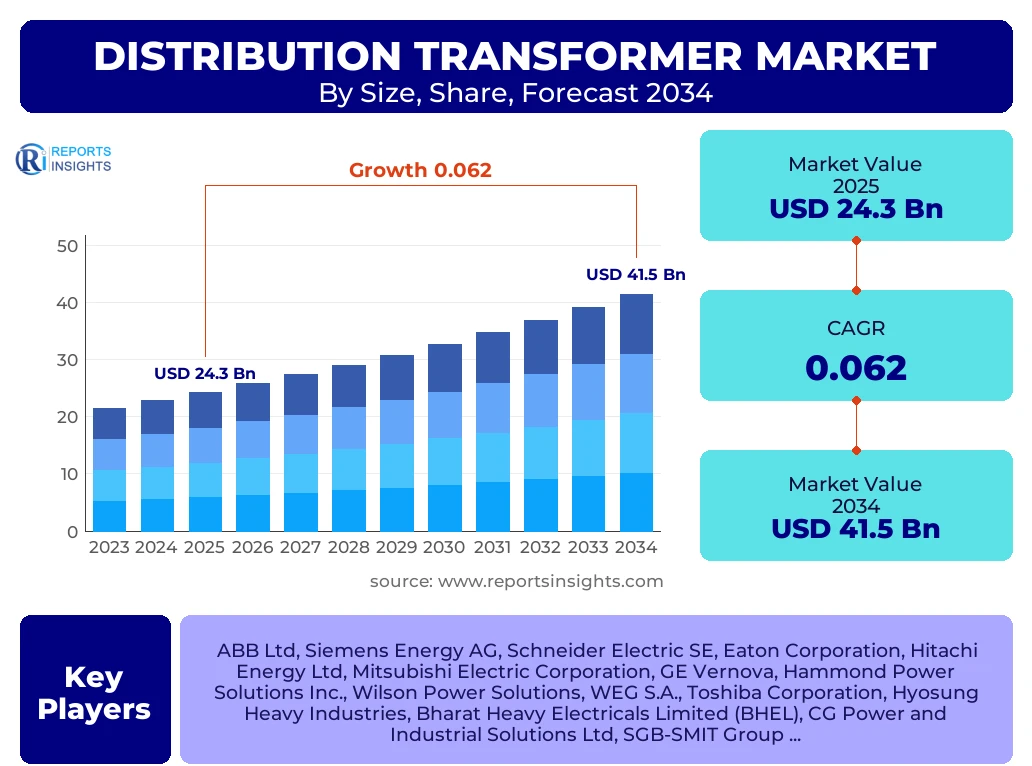
According to Reports Insights Consulting Pvt Ltd, The Distribution Transformer Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 25.8 Billion in 2026 and is projected to reach USD 41.5 Billion by the end of the forecast period in 2034.
Key Distribution Transformer Market Trends & Insights
The global energy landscape is undergoing a fundamental transformation characterized by the decentralization of power generation and the rapid integration of renewable energy sources. Distribution transformers, acting as the critical final stage in the power delivery chain, are being re-engineered to accommodate bidirectional power flows and high-frequency fluctuations associated with solar and wind inputs. Current market intelligence indicates a significant shift toward smart distribution transformers equipped with IoT sensors and real-time monitoring capabilities. These advancements allow utilities to optimize load management and reduce operational expenditures through predictive maintenance. Furthermore, the adoption of amorphous core transformers is gaining momentum due to their superior energy efficiency and lower no-load losses compared to traditional silicon steel variants, aligning with global decarbonization mandates and stringent energy performance standards.
- Asia Pacific remains the largest and fastest-growing region due to massive grid expansion projects in China and India.
- The Three-phase segment holds the largest market share, driven by industrial electrification and commercial infrastructure development.
- Pad-mounted transformers are witnessing the highest growth in the residential and commercial sectors due to their safety and aesthetic advantages in urban environments.
- Amorphous core technology is emerging as a critical trend to meet new minimum efficiency standards in North America and Europe.
- Digitalization of the grid is fostering the demand for solid-state distribution transformers (SST) in specialized smart-grid applications.
Key Takeaways Distribution Transformer Market Size & Forecast
The distribution transformer market is heavily influenced by the urgent need to modernize aging electrical infrastructure in developed economies and the necessity for new grid establishments in emerging nations. Analysis of the forecast period suggests that the transition toward electric mobility (EVs) will place unprecedented stress on local distribution networks, necessitating the replacement or upgrading of existing transformer fleets. Strategic investments in grid resiliency and the implementation of microgrids are serving as primary catalysts for market expansion. Moreover, the regulatory focus on reducing greenhouse gas emissions is pushing manufacturers to adopt biodegradable ester oils as insulation fluids instead of traditional mineral oils. This shift not only addresses environmental concerns but also enhances the fire safety profile of distribution units in densely populated areas.
- Utility applications represent the leading end-user segment, accounting for over 50% of the global market value.
- The United States and China are the primary revenue contributors, fueled by grid hardening initiatives and renewable energy integration targets.
- Replacement demand in Europe is accelerating as legacy systems reach the end of their 30-to-40-year operational lifecycles.
- Liquid-immersed transformers continue to dominate the market owing to their cost-effectiveness and superior cooling capabilities in high-voltage applications.
- Market players are increasingly focusing on modular designs to facilitate easier installation in remote or space-constrained locations.
Distribution Transformer Market Drivers Analysis
The primary engines of growth in the distribution transformer sector are centered on the global energy transition and the modernization of infrastructure. The surge in renewable energy capacity requires a more robust and flexible distribution network capable of handling intermittent loads. Additionally, the rapid urbanization in developing countries is creating a massive requirement for new power distribution nodes to support residential and commercial growth.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of Renewable Energy Sources | +1.8% | European Union and North America | 2025-2034 |
| Grid Modernization and Replacement of Aging Infrastructure | +1.5% | United States and Japan | 2025-2030 |
| Rising Demand for Electric Vehicle (EV) Charging Infrastructure | +1.2% | Global (Primarily Urban Centers) | 2026-2034 |
| Rapid Urbanization and Industrialization | +1.7% | India and Southeast Asia | 2025-2034 |
Distribution Transformer Market Restraints Analysis
Despite strong growth drivers, the market faces significant headwinds related to the volatility of raw material prices and the high initial capital investment required for high-efficiency units. Fluctuations in the cost of copper, aluminum, and electrical steel can severely impact the profit margins of manufacturers and delay large-scale utility procurement projects.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Prices of Raw Materials (Copper/Steel) | -0.8% | Global Manufacturers | Continuous |
| High Cost of Advanced Energy-Efficient Transformers | -0.5% | Emerging Economies | 2025-2028 |
| Strict Environmental Regulations for Mineral Oil Disposal | -0.3% | Europe and North America | 2025-2034 |
Distribution Transformer Market Opportunities Analysis
The evolution of smart cities and the deployment of microgrids present substantial opportunities for specialized distribution transformer solutions. As cities become more connected, the demand for transformers that can communicate with central grid management systems is expected to skyrocket. Additionally, the shift toward biodegradable insulation fluids offers a path for market differentiation and compliance with ESG (Environmental, Social, and Governance) goals.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Smart Grid Technologies | +2.1% | Global | 2026-2034 |
| Adoption of Amorphous Metal Core Transformers | +1.4% | China and India | 2025-2032 |
| Expansion of Rural Electrification Programs | +1.1% | Africa and Latin America | 2025-2034 |
Distribution Transformer Market Challenges Impact Analysis
The industry must navigate challenges related to supply chain disruptions and a shortage of skilled labor for installation and maintenance. Furthermore, the slow pace of regulatory approvals for new grid projects can lead to project backlogs, hindering the timely deployment of distribution assets in critical regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability for Electrical Components | -0.6% | Global | 2025-2027 |
| Cybersecurity Risks in Connected Smart Transformers | -0.4% | Developed Markets | 2026-2034 |
| Lengthy Permitting Processes for Infrastructure Projects | -0.7% | United Kingdom and United States | 2025-2030 |
Distribution Transformer Market - Updated Report Scope
This comprehensive market report provides an in-depth analysis of the global distribution transformer industry, covering technological advancements, regulatory frameworks, and competitive dynamics. The scope includes detailed volume and value forecasts, segment-specific insights, and an evaluation of the impact of global energy policies on market growth. By examining both the upstream supply of raw materials and downstream demand from utilities and industries, the report offers a 360-degree view of the market ecosystem.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 24.3 Billion |
| Market Forecast in 2034 | USD 41.5 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 254 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | ABB Ltd, Siemens Energy AG, Schneider Electric SE, Eaton Corporation, Hitachi Energy Ltd, Mitsubishi Electric Corporation, GE Vernova, Hammond Power Solutions Inc., Wilson Power Solutions, WEG S.A., Toshiba Corporation, Hyosung Heavy Industries, Bharat Heavy Electricals Limited (BHEL), CG Power and Industrial Solutions Ltd, SGB-SMIT Group, Ormazabal, Kirloskar Electric Company, Howard Industries, ERMCO (Electric Research and Manufacturing Cooperation) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The distribution transformer market is segmented based on mounting type, insulation medium, phase, power rating, and end-user application. The insulation segment is currently undergoing a significant transition as environmental regulations favor dry-type and ester-filled transformers over traditional mineral oil units. The power rating segment is dominated by units between 501 kVA and 2500 kVA, which are the standard for most commercial and light industrial applications. However, the demand for single-phase transformers remains robust in North American residential grids, whereas three-phase systems are the norm across Europe and Asia.
- Mounting: Pad-mounted transformers are the leading sub-segment due to their extensive use in underground power distribution systems in modern urban developments and commercial complexes.
- Insulation: Liquid-immersed transformers hold the majority share because of their superior cooling and longevity in outdoor environments, while dry-type units are preferred for indoor installations like hospitals and data centers.
- Phase: Three-phase transformers are experiencing higher growth rates due to the expansion of industrial manufacturing facilities and the modernization of distribution networks in developing countries.
- End-User: The utility sector is the primary consumer, driven by state-led electrification programs and the need to integrate localized renewable energy generation.
Regional Highlights
- Asia Pacific: Currently the largest market, accounting for over 40% of global share, driven by rapid urbanization in China and India, alongside significant investments in high-voltage distribution networks.
- North America: A mature yet high-growth market focused on the replacement of aging infrastructure and the integration of grid-edge technologies to support EV charging and residential solar.
- Europe: Leading the transition toward "Green Transformers," with strict Ecodesign Tier 2 requirements pushing the adoption of high-efficiency and low-noise units.
- Middle East and Africa: Experiencing substantial growth in utility-scale projects, particularly in Saudi Arabia and the UAE, as part of their economic diversification and infrastructure modernization goals.
- Latin America: Growth is primarily driven by renewable energy auctions and the expansion of the electrical grid into rural and previously underserved regions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Distribution Transformer Market.- ABB Ltd
- Siemens Energy AG
- Schneider Electric SE
- Eaton Corporation
- Hitachi Energy Ltd
- Mitsubishi Electric Corporation
- GE Vernova
- Hammond Power Solutions Inc.
- Wilson Power Solutions
- WEG S.A.
- Toshiba Corporation
- Hyosung Heavy Industries
- Bharat Heavy Electricals Limited (BHEL)
- CG Power and Industrial Solutions Ltd
- SGB-SMIT Group
- Ormazabal
- Kirloskar Electric Company
- Howard Industries
- ERMCO
- Jiangsu Huapeng Transformer Co., Ltd.
Frequently Asked Questions
What is the current size and projected growth of the Distribution Transformer Market?
The global distribution transformer market is valued at approximately USD 24.3 Billion in 2025 and is expected to grow at a CAGR of 6.2%, reaching an estimated USD 41.5 Billion by 2034.
Which factors are driving the demand for smart distribution transformers?
The primary drivers include the need for real-time grid monitoring, the integration of distributed renewable energy sources, and the modernization of electrical networks to support smart city initiatives and EV charging infrastructure.
What are the environmental advantages of using ester-filled transformers?
Ester fluids are biodegradable, have higher flash points than mineral oil, and offer improved fire safety, making them ideal for use in environmentally sensitive areas and densely populated urban centers.
Which region holds the largest market share in the distribution transformer industry?
Asia Pacific is the dominant region, fueled by massive investments in power infrastructure in China and India, as well as rapid industrialization across Southeast Asia.
What is the impact of amorphous metal core technology on transformer efficiency?
Amorphous metal cores significantly reduce no-load losses by up to 70% compared to traditional silicon steel cores, helping utilities meet stringent energy efficiency standards and reduce overall grid waste.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
