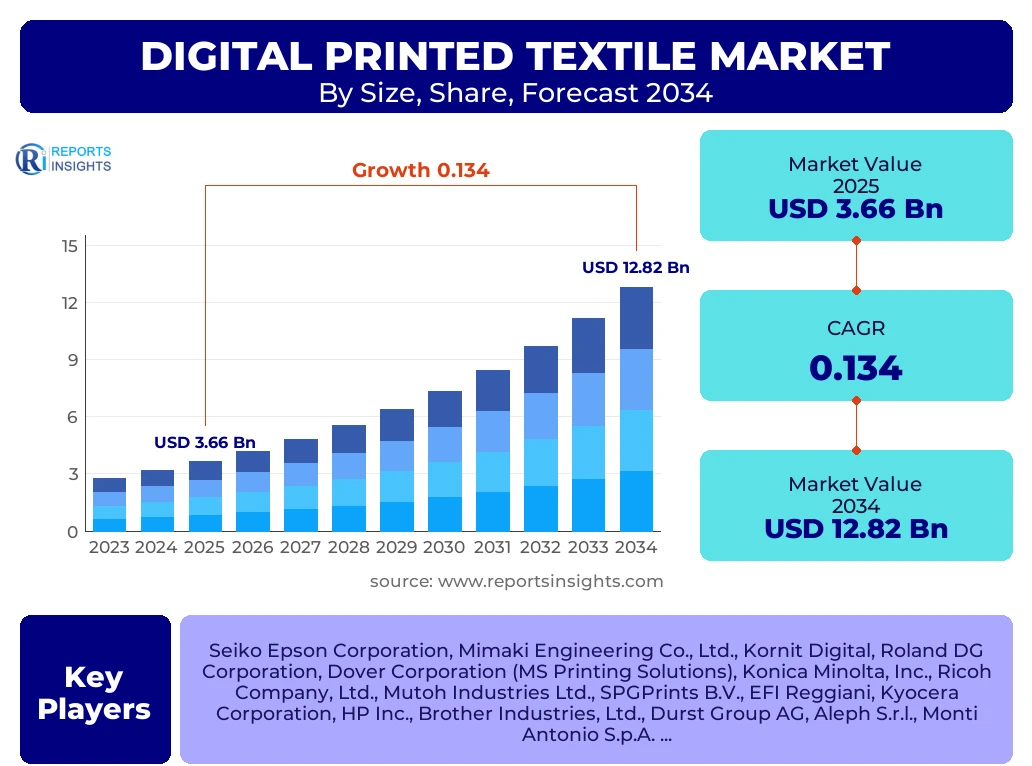
Digital Printed Textile Market
Digital Printed Textile Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711787 | Published On : November 16, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Digital Printed Textile Market Size
According to Reports Insights Consulting Pvt Ltd, The Digital Printed Textile Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.4% between 2025 and 2034. The market is estimated at USD 4.15 Billion in 2026 and is projected to reach USD 12.82 Billion by the end of the forecast period in 2034.
Key Digital Printed Textile Market Trends & Insights
The global digital printed textile sector is undergoing a profound structural transformation, driven by the convergence of high-speed inkjet technology and the escalating demand for sustainable manufacturing practices. Market intelligence indicates that the shift from traditional analog screen printing to digital alternatives is no longer merely a trend but a fundamental requirement for brands seeking to remain competitive in a fast-fashion ecosystem. Users frequently query the viability of digital printing for high-volume production; insights reveal that the introduction of single-pass printing machines has significantly closed the gap between digital agility and rotary screen speed. Furthermore, regional benchmarking shows a strong migration of production capabilities toward localized "micro-factories" in North America and Europe to reduce lead times and carbon footprints associated with long-distance logistics.
- Asia-Pacific remains the largest regional market, commanded by massive production hubs in China, India, and Vietnam that are rapidly upgrading to high-capacity digital systems.
- Europe is identified as the fastest-growing region in terms of high-value specialty printing and luxury fashion, with Italy serving as a global center for innovation in digital silk and high-end apparel.
- The Apparel and Fashion segment holds the largest market share, fueled by the demand for personalized clothing and the industry-wide move toward "on-demand" inventory models.
- Pigment ink technology is emerging as the fastest-growing ink segment due to its versatility across various fiber types and its reduced water consumption compared to reactive or acid dyes.
Key Takeaways Digital Printed Textile Market Size & Forecast
Analysis of market trajectories suggests that the Digital Printed Textile market is entering a phase of maturity regarding technological reliability while simultaneously expanding into new industrial applications. Stakeholders are increasingly concerned with the total cost of ownership (TCO) and the integration of digital workflows with existing Enterprise Resource Planning (ERP) systems. The forecast period highlights a significant shift toward circular economy principles, where digital printing facilitates the use of recycled polyester and organic cotton by providing precise application that minimizes chemical waste. This shift is expected to sustain high double-digit growth rates as regulatory pressures regarding water effluent in textile manufacturing intensify globally.
- The global market value is expected to triple over the next decade, reflecting a deeper penetration into the home decor and technical textile sectors.
- China and India are the primary volume drivers, while the United Kingdom and Italy lead in technological IP and high-margin fashion exports.
- Subscription-based models for ink and software are becoming standard among leading OEMs to ensure long-term serviceability and consistent output quality for end-users.
- Advancements in printhead longevity and drop-on-demand (DoD) precision are drastically reducing the maintenance downtime previously associated with digital textile equipment.
Digital Printed Textile Market Drivers Analysis
The primary catalyst for the digital printed textile market is the radical compression of the fashion cycle. Traditional retail models that relied on six-month lead times are being replaced by ultra-fast fashion cycles that require new designs to move from concept to consumer in as little as two weeks. Digital printing eliminates the need for screen preparation, allowing for immediate production of small batches, which reduces the risk of unsold inventory and enables brands to test designs in real-time. This agility is a critical competitive advantage in an era dominated by social media trends and influencer-driven consumer behavior.
Environmental sustainability serves as a secondary but equally potent driver. Conventional textile dyeing and printing are among the most water-intensive industrial processes globally. Digital inkjet printing utilizes significantly less water—often up to 90% less—and reduces energy consumption by eliminating the need for massive drying ovens used in screen printing. As ESG (Environmental, Social, and Governance) mandates become mandatory for global apparel brands, the transition to digital printing becomes a strategic necessity to meet carbon neutrality goals and water conservation targets.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demand for On-Demand Fashion & Customization | +4.2% | Global (High in North America & EU) | 2025-2034 |
| Sustainability & Stringent Water Regulations | +3.8% | China, India, Bangladesh | 2026-2034 |
| Technological Gains in Single-Pass Printing | +3.1% | Italy, Japan, Germany | 2025-2030 |
Digital Printed Textile Market Restraints Analysis
Despite the technological advancements, the high initial capital expenditure remains a significant barrier for small and medium-sized enterprises (SMEs). High-end digital textile printers, especially single-pass systems capable of industrial-scale output, require substantial investment that can be difficult to justify in markets with low labor costs and established analog infrastructure. Furthermore, the cost of specialized digital inks remains considerably higher than the bulk dyes used in traditional methods, which can skew the unit cost for very large production runs where the efficiency of digital printing begins to plateau.
Technical limitations regarding substrate compatibility also present a restraint. While digital printing on polyester (via sublimation) and cotton (via reactive or pigment) is well-established, achieving the same level of color fastness and vibrancy on certain synthetic blends or heavily textured fabrics can be challenging. The need for specific pre-treatment and post-treatment processes for different ink types adds complexity to the workflow, requiring specialized knowledge that is still developing in many traditional manufacturing regions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Investment & Maintenance Costs | -2.1% | Emerging Markets (SE Asia, Africa) | 2025-2028 |
| Higher Cost of Digital Inks vs. Traditional Dyes | -1.8% | Global | 2025-2034 |
Digital Printed Textile Market Opportunities Analysis
The expansion into the "Home Decor" and "Technical Textiles" sectors represents a massive untapped opportunity for digital printing. Digital technology allows for the creation of intricate, photographic-quality patterns on upholstery, curtains, and wallcoverings that were previously impossible or cost-prohibitive with screen printing. Additionally, the automotive and healthcare industries are increasingly looking toward digital printing for customized interior components and antimicrobial medical textiles, where precision and localized application are paramount.
Another significant opportunity lies in the development of AI-integrated design-to-print workflows. By leveraging artificial intelligence, manufacturers can optimize nesting patterns to reduce fabric waste and automatically adjust color profiles to ensure consistency across different batches and machines. This digital integration facilitates the "Connected Factory" concept, where printing machines communicate directly with e-commerce platforms, enabling a seamless "click-to-ship" model that bypasses traditional wholesale distribution networks.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Home Textiles & Decor | +2.9% | United States, Germany, Turkey | 2026-2034 |
| AI & IoT Integration in Smart Factories | +2.4% | Japan, South Korea, USA | 2027-2034 |
| Growth in Bio-based & Eco-friendly Inks | +1.7% | European Union | 2025-2034 |
Digital Printed Textile Market Challenges Impact Analysis
A primary challenge is the shortage of skilled labor capable of operating and maintaining sophisticated digital printing hardware and software. Unlike traditional printing, which relies on mechanical expertise, digital textile printing requires a blend of color science knowledge, digital file management, and chemical understanding of ink-substrate interactions. The rapid pace of hardware evolution often outstrips the training programs available to the workforce, leading to suboptimal machine utilization and increased downtime.
Supply chain volatility for specialty chemicals used in ink formulation also poses a persistent challenge. The reliance on specific photo-initiators and high-purity pigments means that disruptions in the global chemical supply chain can lead to sudden price spikes or shortages of digital inks. As the market scales, ensuring a stable and cost-effective supply of these critical consumables is essential for maintaining the growth momentum of the digital textile sector.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Skill Gap in Digital Workflow Management | -1.5% | Global (Especially India & Brazil) | 2025-2030 |
| Supply Chain Fragility for Specialty Inks | -1.2% | Global | 2025-2027 |
Digital Printed Textile Market - Updated Report Scope
The scope of this market research report encompasses a comprehensive analysis of the entire digital textile value chain, including hardware (printers), consumables (inks), and end-use applications. It evaluates the shift from scanning to single-pass technologies and assesses the impact of environmental regulations on the adoption of digital workflows across different geographic regions. The report provides a granular breakdown of market dynamics, focusing on the transition toward pigment-based printing and the rise of localized production hubs.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.66 Billion |
| Market Forecast in 2034 | USD 12.82 Billion |
| Growth Rate | 13.4% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Seiko Epson Corporation, Mimaki Engineering Co., Ltd., Kornit Digital, Roland DG Corporation, Dover Corporation (MS Printing Solutions), Konica Minolta, Inc., Ricoh Company, Ltd., Mutoh Industries Ltd., SPGPrints B.V., EFI Reggiani, Kyocera Corporation, HP Inc., Brother Industries, Ltd., Durst Group AG, Aleph S.r.l., Monti Antonio S.p.A., Aeoon Technologies GmbH. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The digital printed textile market is segmented based on technology, ink chemistry, substrate type, and end-user application. Each segment is experiencing unique growth trajectories influenced by technical feasibility and cost-efficiency. Sublimation printing remains the dominant force in the polyester-based apparel and signage markets due to its vibrant colors and durability. However, the pigment ink segment is seeing the most rapid adoption in the cotton and home textile sectors as it simplifies the production process by eliminating the need for intensive washing and steaming post-treatment. Direct-to-Garment (DTG) technology is also witnessing a surge, particularly among e-commerce retailers offering personalized apparel, while Direct-to-Fabric (DTF) remains the standard for industrial-scale roll-to-roll production.
- By Ink Type: Sublimation, Reactive, Acid, Pigment, Disperse
- By Substrate: Cotton, Silk, Polyester, Nylon, Rayon, Other Blends
- By Printing Technology: Direct-to-Fabric (DTF), Direct-to-Garment (DTG), Dye Sublimation Transfer
- By Application: Fashion & Apparel, Home Decor (Curtains, Upholstery), Soft Signage (Banners, Flags), Industrial/Technical Textiles
- By Machine Speed: Low-speed (Scanning), Medium-speed, High-speed (Single-pass)
Regional Highlights
- Asia-Pacific: The largest market globally, driven by China’s massive manufacturing base and India’s growing textile export sector. The region is the primary adopter of high-volume single-pass machines.
- Europe: The fastest-growing region for digital innovation, led by Italy and Germany. The focus here is on high-end fashion, luxury home decor, and sustainable production technologies.
- North America: Significant growth in the Direct-to-Garment (DTG) segment, fueled by a booming personalized e-commerce sector and the trend toward "re-shoring" textile production.
- Middle East & Africa: Turkey is a key player in this region, acting as a bridge between Asian production and European demand, with a high concentration of digital textile printing facilities for the apparel market.
- Latin America: Brazil is emerging as a regional hub for digital printing, particularly in the swimwear and athletic apparel segments, supported by a large domestic textile industry.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Digital Printed Textile Market.- Seiko Epson Corporation
- Mimaki Engineering Co., Ltd.
- Kornit Digital
- Roland DG Corporation
- Dover Corporation (MS Printing Solutions)
- Konica Minolta, Inc.
- Ricoh Company, Ltd.
- Mutoh Industries Ltd.
- SPGPrints B.V.
- EFI Reggiani
- Kyocera Corporation
- HP Inc.
- Brother Industries, Ltd.
- Durst Group AG
- Aleph S.r.l.
- Monti Antonio S.p.A.
- Aeoon Technologies GmbH
- Zimmer Austria
- Colorjet India Ltd.
- Dannaher Corporation
Frequently Asked Questions
What is the primary factor driving the growth of the digital printed textile market?
The primary driver is the shift toward "on-demand" production and fast fashion, which requires short lead times and the ability to produce small, customized batches economically. Additionally, the significant reduction in water and energy consumption compared to traditional printing makes it a preferred choice for sustainable manufacturing.
Which ink type is currently leading the market and why?
Sublimation inks currently hold a major share due to their widespread use in polyester-based sportswear and soft signage. However, pigment inks are the fastest-growing segment because they can be used on multiple fabric types (cotton, polyester, blends) with a simplified, water-saving process that does not require extensive post-processing.
How does digital printing compare to traditional screen printing in terms of cost?
For small to medium-sized runs, digital printing is more cost-effective as it eliminates the high setup costs of screen preparation. While traditional screen printing is still cheaper for very high-volume bulk production, digital technology (especially single-pass) is rapidly closing the cost gap for large-scale operations.
Which region is expected to dominate the digital printed textile market by 2034?
Asia-Pacific is expected to remain the dominant region in terms of volume and market share, driven by the textile manufacturing hubs in China and India. However, Europe will likely maintain its lead in technological innovation and high-margin luxury textile printing.
What are the main challenges facing the adoption of digital textile printing?
Key challenges include the high initial capital investment for industrial printers, the relatively high cost of specialized inks, and a significant shortage of skilled technicians who can manage the complex digital workflows and maintain high-precision equipment.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
