Diesel Particulate Filter Market
Diesel Particulate Filter Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711573 | Published On : November 06, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Diesel Particulate Filter Market Size
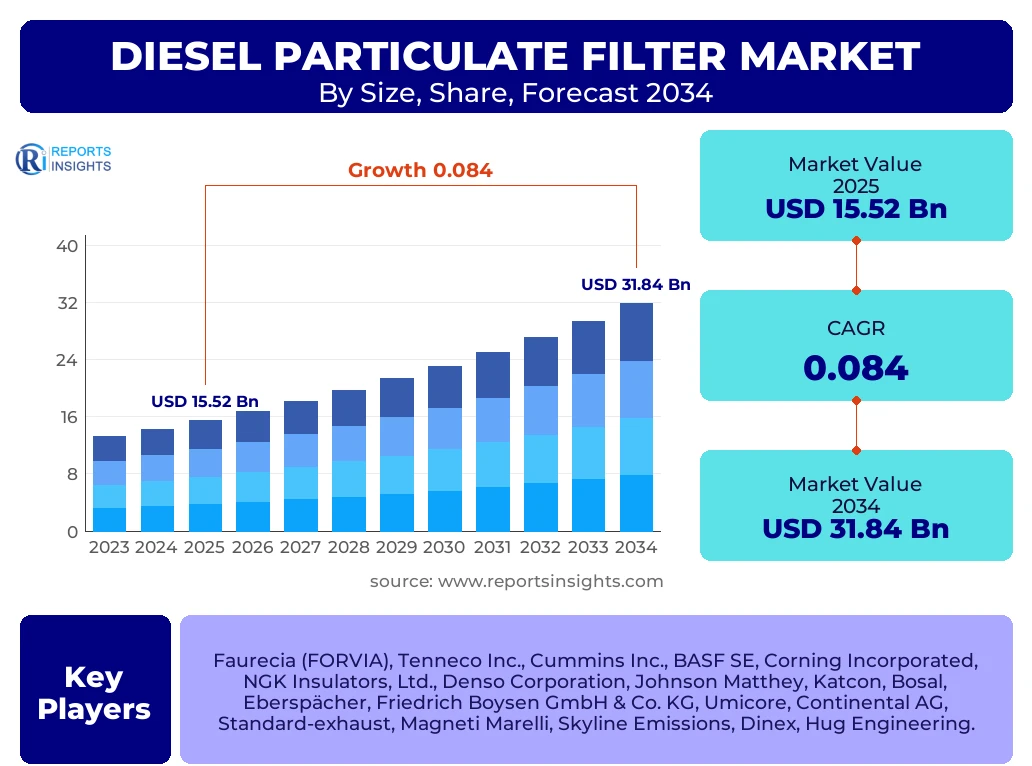
According to Reports Insights Consulting Pvt Ltd, The Diesel Particulate Filter Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 16.82 Billion in 2026 and is projected to reach USD 31.84 Billion by the end of the forecast period in 2034.
Key Diesel Particulate Filter Market Trends & Insights
The global automotive landscape is undergoing a significant transformation driven by the intersection of stringent environmental mandates and advancements in filtration technology. Diesel Particulate Filters (DPF) have transitioned from being optional components to mandatory integrated systems in modern diesel powertrains. Current market trends indicate a sharp focus on material innovation, specifically the transition from traditional cordierite to high-thermal-stability silicon carbide (SiC) substrates. Furthermore, the integration of DPF with Selective Catalytic Reduction (SCR) systems into a single brick—often referred to as SDPF—is gaining traction as manufacturers strive to reduce the weight and footprint of exhaust aftertreatment systems. Competitive benchmarking reveals that leading players are investing heavily in soot-sensing technology and predictive maintenance algorithms to prevent filter clogging, a primary pain point for end-users. Regional insights highlight a robust demand in the Asia-Pacific region, fueled by the adoption of Bharat Stage VI (BS-VI) in India and China VI standards, which necessitate ultra-fine particulate matter trapping.
- Largest Region: Europe remains the largest market due to early and stringent implementation of Euro 6/VI standards and high diesel vehicle density.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, driven by rapid industrialization and the tightening of emission norms in China and India.
- Largest Segment by Share: Silicon Carbide (SiC) filters currently lead the market share in the material category due to superior filtration efficiency and durability.
- Key Application Driver: Heavy Commercial Vehicles (HCVs) represent the highest value segment as long-haul logistics continue to rely on high-torque diesel engines.
- Emerging Trend: The development of "Passive-Active" hybrid regeneration systems to optimize fuel efficiency during the soot oxidation process.
Key Takeaways Diesel Particulate Filter Market Size & Forecast
The Diesel Particulate Filter market is positioned for sustained growth, underpinned by the global commitment to reducing carbon footprints and improving urban air quality. The forecast period highlights a steady trajectory where the replacement market (aftermarket) is expected to grow alongside original equipment manufacturer (OEM) installations. Users and stakeholders are increasingly concerned with the total cost of ownership, leading to a surge in demand for high-quality filters that offer longer service intervals and better fuel economy. The shift toward electrification poses a long-term challenge; however, the medium-term outlook remains bullish due to the continued dominance of diesel in the heavy-duty transport and off-road machinery sectors. Strategic partnerships between filter manufacturers and chemical companies for advanced coating technologies are becoming common as the industry moves toward near-zero emission targets.
- Leading Country: China is the dominant force in the APAC region, accounting for a massive share of both production and consumption of particulate filters.
- Forecast Milestone: The market is expected to cross the USD 25 billion mark by 2030, reflecting the intensity of global regulatory pressure.
- Technological Shift: Transition from wall-flow to partial-flow filters in specific low-emission zone applications.
- Market Stability: Demand is bolstered by the retrofit market in developing economies attempting to upgrade older fleets to meet current environmental standards.
- Investment Focus: R&D is heavily skewed toward reducing backpressure and improving the regeneration efficiency of filters in cold-start conditions.
Diesel Particulate Filter Market Drivers Analysis
The primary catalyst for the Diesel Particulate Filter market is the global convergence of emission standards. As countries adopt variations of the Euro VI norms, the installation of DPFs has become a non-negotiable requirement for diesel engine compliance. Additionally, the expansion of the global logistics and construction sectors has led to increased production of heavy-duty diesel engines, which require sophisticated filtration systems to meet PM2.5 and PM10 reduction targets. The rising awareness of respiratory health issues associated with diesel soot is also pushing local governments to mandate DPF retrofitting for older public transport and municipal fleets.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Emission Norms (Euro 7, EPA 2027) | +3.2% | European Union, North America | 2025-2034 |
| Growth in Heavy-Duty Logistics | +2.1% | Global, particularly APAC and North America | 2026-2030 |
| Retrofit Mandates for Urban Air Quality | +1.5% | India, Brazil, Southeast Asia | 2025-2029 |
| Advancements in SiC Substrate Technology | +1.6% | Germany, Japan, USA | 2027-2034 |
Diesel Particulate Filter Market Restraints Analysis
Despite strong growth, the market faces significant headwinds from the accelerating adoption of Battery Electric Vehicles (BEVs), particularly in the passenger vehicle segment. The long-term phase-out of internal combustion engines in various jurisdictions directly threatens the future volume of DPF installations. Furthermore, the high cost of specialized materials like silicon carbide and the technical complexities associated with filter regeneration failures—which can lead to expensive engine repairs—act as deterrents for some price-sensitive markets. Maintenance requirements and the periodic need for professional cleaning also increase the total cost of ownership for diesel vehicle operators.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Electrification of Passenger Vehicle Fleets | -2.8% | Europe, China, California (USA) | 2028-2034 |
| High Maintenance & Replacement Costs | -1.2% | Global | 2025-2034 |
| Technical Failures in Regeneration Cycles | -0.7% | Emerging Markets | 2025-2030 |
Diesel Particulate Filter Market Opportunities Analysis
The transition toward more complex emission systems creates a unique opportunity for high-value integrated solutions. The development of SDPF (SCR on DPF) systems is a high-growth area, as it offers a compact solution for tight engine compartments while maintaining high NOx and PM reduction. Additionally, the off-highway segment, including agricultural and mining machinery, remains a largely untapped market in many developing regions where emission norms are only now becoming strict. The aftermarket for DPF cleaning services and remanufactured filters also presents a lucrative recurring revenue stream for service providers and component manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of SDPF Integrated Systems | +2.4% | Germany, USA, South Korea | 2026-2034 |
| Expansion into Off-Highway/Mining Equipment | +1.8% | Australia, Canada, South Africa | 2025-2032 |
| Growth of DPF Remanufacturing & Service Industry | +1.3% | Europe, North America | 2025-2034 |
Diesel Particulate Filter Market Challenges Impact Analysis
The Diesel Particulate Filter industry must navigate challenges related to raw material supply chains and the increasing complexity of engine management systems. Fluctuations in the prices of precious metals used in washcoats can affect manufacturer margins. Additionally, the technical challenge of ensuring filter efficiency in short-trip, stop-and-go urban driving conditions remains a hurdle, as the exhaust temperature often fails to reach the levels required for passive regeneration. This leads to soot accumulation and potential filter failure, necessitating more frequent active regeneration cycles which can negatively impact fuel economy.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility (SiC, Cordierite) | -0.9% | Global | 2025-2028 |
| Inefficiency in Low-Temperature Urban Environments | -1.1% | Urban Centers Globally | 2025-2034 |
| Complexity of On-Board Diagnostic (OBD) Integration | -0.5% | OEM Manufacturers | 2026-2030 |
Diesel Particulate Filter Market - Updated Report Scope
This report provides an exhaustive analysis of the global Diesel Particulate Filter landscape, covering technical specifications, market dynamics, and competitive positioning. The scope encompasses the entire value chain from substrate material suppliers to exhaust system integrators and aftermarket service providers. It includes a detailed assessment of the impact of emerging emission standards across different vehicle classes including light, medium, and heavy-duty vehicles, as well as specialized off-road equipment. The analysis is built upon a foundation of primary and secondary research, ensuring that the market size and forecast data are validated by industry experts and reflect the latest macroeconomic shifts.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 15.52 Billion |
| Market Forecast in 2034 | USD 31.84 Billion |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Faurecia (FORVIA), Tenneco Inc., Cummins Inc., BASF SE, Corning Incorporated, NGK Insulators, Ltd., Denso Corporation, Johnson Matthey, Katcon, Bosal, Eberspächer, Friedrich Boysen GmbH & Co. KG, Umicore, Continental AG, Standard-exhaust, Magneti Marelli, Skyline Emissions, Dinex, Hug Engineering. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Diesel Particulate Filter market is segmented primarily by material, regeneration type, and vehicle application, each of which is influenced by distinct technological and economic factors. The substrate material segment is the most critical from a manufacturing perspective, as it determines the filter's ability to withstand thermal stress and its filtration efficiency. Silicon Carbide is increasingly favored for heavy-duty applications due to its higher melting point and better soot-holding capacity compared to Cordierite, which remains popular in budget-sensitive segments. The regeneration process is another vital differentiator; while passive regeneration is energy-efficient, active systems are necessary for vehicles operating in low-load or urban environments where exhaust temperatures do not naturally reach oxidation levels.
- By Substrate Material:
- Silicon Carbide (SiC): High durability and efficiency, leading in the HCV segment.
- Cordierite: Cost-effective, widely used in LCVs and older passenger models.
- Ceramic Fiber and Metallic: Niche applications in high-performance or specific industrial engines.
- By Regeneration Process:
- Active Regeneration: Dominant in modern vehicles to ensure reliability regardless of driving style.
- Passive Regeneration: Utilizes catalysts to oxidize soot at lower temperatures, often used in conjunction with active systems.
- By Vehicle Type:
- Heavy Commercial Vehicles (HCV): The largest value segment due to the size and complexity of the filters.
- Passenger Cars: Significant volume, though growth is tempered by electrification.
- Off-Highway Equipment: Rapidly growing segment as Stage V and Tier 4 Final norms are enforced globally.
- By Sales Channel:
- OEM (Original Equipment Manufacturer): High volume, driven by new vehicle production and regulatory compliance.
- Aftermarket: Stable growth driven by replacement cycles, cleaning services, and retrofitting projects.
Regional Highlights
- Europe: The established leader in the DPF market, Europe’s strict adherence to Euro 6d and the upcoming Euro 7 standards ensures high penetration. Germany, France, and the UK are key hubs for filtration technology R&D.
- Asia-Pacific: The fastest-growing region. China’s implementation of China VI standards and India’s BS-VI mandate have created a massive surge in demand. The presence of major automotive manufacturing hubs in Japan and South Korea further bolsters market growth.
- North America: A mature market focused on high-performance filters for heavy-duty trucks. EPA standards and the move toward more stringent 2027 emission rules are driving innovation in the region.
- Latin America: Countries like Brazil and Mexico are progressively tightening their emission standards (PROCONVE L-7/P-8), providing new opportunities for DPF manufacturers in the commercial vehicle space.
- Middle East & Africa: Growth is primarily driven by the mining sector and the gradual modernization of transportation fleets in countries like South Africa and Saudi Arabia.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Diesel Particulate Filter Market.- Faurecia (FORVIA)
- Tenneco Inc.
- Cummins Inc.
- BASF SE
- Corning Incorporated
- NGK Insulators, Ltd.
- Denso Corporation
- Johnson Matthey
- Katcon
- Bosal
- Eberspächer
- Friedrich Boysen GmbH & Co. KG
- Umicore
- Continental AG
- Standard-exhaust
- Magneti Marelli
- Skyline Emissions
- Dinex
- Hug Engineering
Frequently Asked Questions
What is the main function of a Diesel Particulate Filter (DPF)?
A Diesel Particulate Filter (DPF) is designed to capture and store exhaust soot (particulate matter) from diesel engines. By trapping these particles, the filter prevents them from being released into the atmosphere, significantly reducing the visible black smoke and harmful emissions associated with diesel combustion.
Why is the Silicon Carbide (SiC) segment growing faster than Cordierite?
Silicon Carbide offers significantly higher thermal conductivity and a higher melting point compared to Cordierite. This makes it more durable during the intense heat of the regeneration process, allowing for more efficient soot oxidation and a longer lifespan, which is critical for heavy-duty and high-performance diesel engines.
How does the shift to electric vehicles (EVs) affect the DPF market?
The rise of EVs poses a long-term challenge to the DPF market as electric motors do not require exhaust filtration. However, the market remains strong in the medium term due to the continued demand for diesel in heavy-duty shipping, construction, and long-haul trucking, where electrification is more difficult to implement.
What is the difference between active and passive DPF regeneration?
Passive regeneration occurs naturally during high-speed driving when exhaust temperatures are high enough to burn off soot. Active regeneration is triggered by the engine management system, which injects extra fuel or uses electric heaters to raise the exhaust temperature and burn off trapped soot when the filter reaches a certain limit, regardless of driving conditions.
Which region currently dominates the Diesel Particulate Filter market?
Europe currently dominates the market due to its early and rigorous adoption of diesel emission standards (Euro norms) and a high percentage of diesel vehicles in its total fleet. However, the Asia-Pacific region is catching up rapidly due to massive industrial growth and new environmental regulations in China and India.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
