Depyrogenated Sterile Empty Vials Market
Depyrogenated Sterile Empty Vials Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711461 | Published On : November 02, 2026 |
Format : 


 | Author : Erika Grotto
Depyrogenated Sterile Empty Vials Market Size
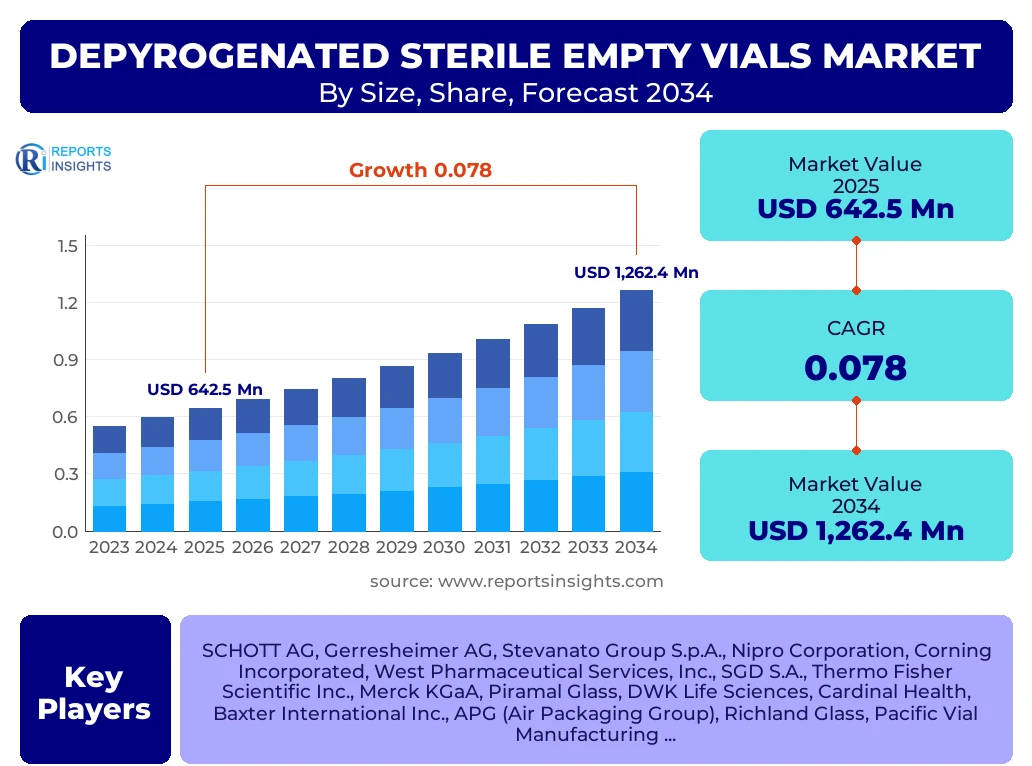
According to Reports Insights Consulting Pvt Ltd, The Depyrogenated Sterile Empty Vials Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2025 and 2034. The market is estimated at USD 642.5 Million in 2025 and is projected to reach USD 1,262.4 Million by the end of the forecast period in 2034.
Key Depyrogenated Sterile Empty Vials Market Trends & Insights
The depyrogenated sterile empty vials sector is undergoing a significant transformation driven by the rapid expansion of the biologics and biosimilars landscape. As pharmaceutical manufacturers pivot toward complex injectable therapies, the demand for high-purity primary packaging that eliminates the need for in-house washing and sterilization has surged. Current market trends indicate a move toward Ready-to-Use (RTU) solutions, which streamline fill-finish operations and reduce the risk of cross-contamination. Furthermore, the integration of advanced glass chemistry, such as aluminosilicate glass, is gaining traction to mitigate issues like delamination and ion leaching, ensuring the long-term stability of sensitive drug formulations. Regional insights suggest a robust shift in manufacturing bases toward the Asia-Pacific region, while North American markets maintain dominance through intensive research and development activities in personalized medicine.
- North America remains the largest region in terms of market share, driven by a high concentration of biopharmaceutical giants and advanced healthcare infrastructure.
- The Asia-Pacific region is the fastest-growing market, characterized by increasing pharmaceutical outsourcing and a growing domestic manufacturing sector in China and India.
- The Type I Borosilicate Glass segment holds the largest market share due to its superior chemical resistance and compatibility with a wide range of injectable drugs.
- Ready-to-Use (RTU) vials are emerging as the dominant format, significantly reducing capital expenditure for pharmaceutical companies by outsourcing the sterilization process.
Key Takeaways Depyrogenated Sterile Empty Vials Market Size & Forecast
The trajectory of the depyrogenated sterile empty vials market is intrinsically linked to the global vaccination programs and the rise of chronic disease treatments requiring frequent injections. Insights into consumer demand reveal a preference for smaller vial capacities (2ml to 5ml) for high-value specialty drugs. Forecasts suggest that the market will witness a steady incline as regulatory bodies like the FDA and EMA tighten standards for sterile packaging, forcing smaller players to adopt certified depyrogenated solutions. The transition from traditional bulk packaging to nested packaging formats is also a key takeaway, as it facilitates higher automation levels in fill-finish lines.
- The United States is the leading country globally, supported by the presence of major biotech innovators and high per capita healthcare spending.
- Germany leads the European market, serving as a central hub for pharmaceutical packaging technology and specialized glass manufacturing.
- The increasing prevalence of diabetes and cancer is a primary catalyst for the sustained demand for sterile vials used in insulin and oncology treatments.
- Sustainability is becoming a critical factor, with companies investing in recyclable glass and eco-friendly sterilization techniques such as E-beam and NO2.
Depyrogenated Sterile Empty Vials Market Drivers Analysis
The primary driver for the market is the global shift toward parenteral drug administration, particularly for biologics that cannot be administered orally. The rise of contract manufacturing organizations (CMOs) has further accelerated the demand for pre-processed vials to optimize operational efficiency.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Biopharmaceuticals and Biosimilars | +3.2% | Global | 2025 - 2034 |
| Shift to Outsourced Sterilization Services | +2.1% | Europe and North America | 2025 - 2030 |
| Stringent Regulatory Guidelines for Injectables | +1.5% | United States, EU | 2025 - 2034 |
Depyrogenated Sterile Empty Vials Market Restraints Analysis
Market growth is hindered by the high cost of advanced sterilization equipment and the volatile pricing of high-grade borosilicate glass. Additionally, the complex logistics involved in maintaining the sterility of empty vials during transport poses a significant challenge.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital for Cleanroom Infrastructure | -1.2% | Developing Economies (APAC, LATAM) | 2025 - 2028 |
| Fluctuations in Raw Glass Material Prices | -0.8% | Global | 2026 - 2034 |
Depyrogenated Sterile Empty Vials Market Opportunities Analysis
The rise of personalized medicine and cell and gene therapies presents a significant opportunity for customized, small-batch vial production. Technological advancements in coatings to prevent drug-container interaction also offer high-growth potential for premium vial segments.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Anti-Delamination Glass Technology | +2.4% | Japan, Germany, USA | 2026 - 2034 |
| Growth in Specialty Vaccine Pipelines | +1.9% | India, China, Brazil | 2025 - 2030 |
Depyrogenated Sterile Empty Vials Market Challenges Impact Analysis
Ensuring end-to-end supply chain integrity remains the most critical challenge, as any breach in the sterile seal renders the product unusable. Furthermore, the industry faces pressure to reduce the carbon footprint associated with intensive heat-based depyrogenation processes.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Vulnerability and Logistics | -1.1% | Global | 2025 - 2034 |
| Environmental Regulations on Energy Consumption | -0.6% | European Union | 2027 - 2034 |
Depyrogenated Sterile Empty Vials Market - Updated Report Scope
This report provides a comprehensive analysis of the global depyrogenated sterile empty vials landscape, covering material types, capacity ranges, and end-user applications across six major geographical regions. It evaluates the impact of technological innovations in glass chemistry and sterilization protocols on market dynamics through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 642.5 Million |
| Market Forecast in 2034 | USD 1,262.4 Million |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | SCHOTT AG, Gerresheimer AG, Stevanato Group S.p.A., Nipro Corporation, Corning Incorporated, West Pharmaceutical Services, Inc., SGD S.A., Thermo Fisher Scientific Inc., Merck KGaA, Piramal Glass, DWK Life Sciences, Cardinal Health, Baxter International Inc., APG (Air Packaging Group), Richland Glass, Pacific Vial Manufacturing, Kimble Chase Life Science and Research Products, LLC |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on material, capacity, and end-user to provide a granular view of the growth drivers in each category. The move toward plastic-based vials like Cyclic Olefin Polymer (COP) is a significant sub-trend for extremely sensitive or cold-chain drugs, although glass remains the industry standard for general injectables.
- By Material: The Type I Borosilicate Glass segment dominates due to its high thermal shock resistance and chemical durability.
- By Capacity: The 2ml to 10ml segment accounts for the highest volume, largely fueled by the packaging of vaccines and monoclonal antibodies.
- By Sterilization Method: Dry heat depyrogenation remains the most widely used method, though vaporized hydrogen peroxide (VHP) is gaining ground for plastic vials.
- By End-User: Pharmaceutical and Biopharmaceutical companies represent the largest share, while the CMO segment is growing at the fastest rate due to increased outsourcing.
Regional Highlights
- North America: The largest market globally, characterized by high adoption of RTU vials and a dominant presence in biotech innovation, particularly in the United States.
- Europe: A mature market with strong regulatory frameworks; Germany and Italy are key hubs for glass manufacturing and sterile packaging technology.
- Asia-Pacific: The fastest-growing region, with China, India, and South Korea becoming major players in vaccine manufacturing and biosimilar production.
- Latin America & MEA: Emerging markets with increasing healthcare investments and a growing focus on localizing pharmaceutical production to ensure supply security.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Depyrogenated Sterile Empty Vials Market.- SCHOTT AG
- Gerresheimer AG
- Stevanato Group S.p.A.
- Nipro Corporation
- Corning Incorporated
- West Pharmaceutical Services, Inc.
- SGD S.A.
- Thermo Fisher Scientific Inc.
- Merck KGaA
- Piramal Glass
- DWK Life Sciences
- Cardinal Health
- Baxter International Inc.
- APG (Air Packaging Group)
- Richland Glass
- Pacific Vial Manufacturing
- Kimble Chase Life Science and Research Products, LLC
Frequently Asked Questions
What is the current market size of the Depyrogenated Sterile Empty Vials industry?
The global market for depyrogenated sterile empty vials is estimated at USD 642.5 Million in 2025 and is projected to reach over USD 1.2 Billion by 2034.
Why are Ready-to-Use (RTU) vials becoming popular in pharmaceutical manufacturing?
RTU vials eliminate the need for pharmaceutical companies to invest in expensive washing and sterilization equipment, thereby reducing operational risks and speeding up the time-to-market for new drugs.
Which material type is most commonly used for sterile vials?
Type I Borosilicate Glass is the most commonly used material due to its exceptional chemical inertness and resistance to thermal expansion, making it ideal for parenteral drug storage.
What role do CMOs play in the growth of the depyrogenated vials market?
Contract Manufacturing Organizations (CMOs) are major drivers of growth as they prefer pre-sterilized, depyrogenated vials to maintain high-speed, flexible fill-finish lines for multiple clients.
What are the key sterilization methods used for these vials?
The most prevalent methods include dry heat depyrogenation for glass and specialized techniques like Ethylene Oxide (EtO) or E-beam for plastic-based vials.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
