Deep Learning Market
Deep Learning Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710896 | Published On : September 15, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Deep Learning Market Size
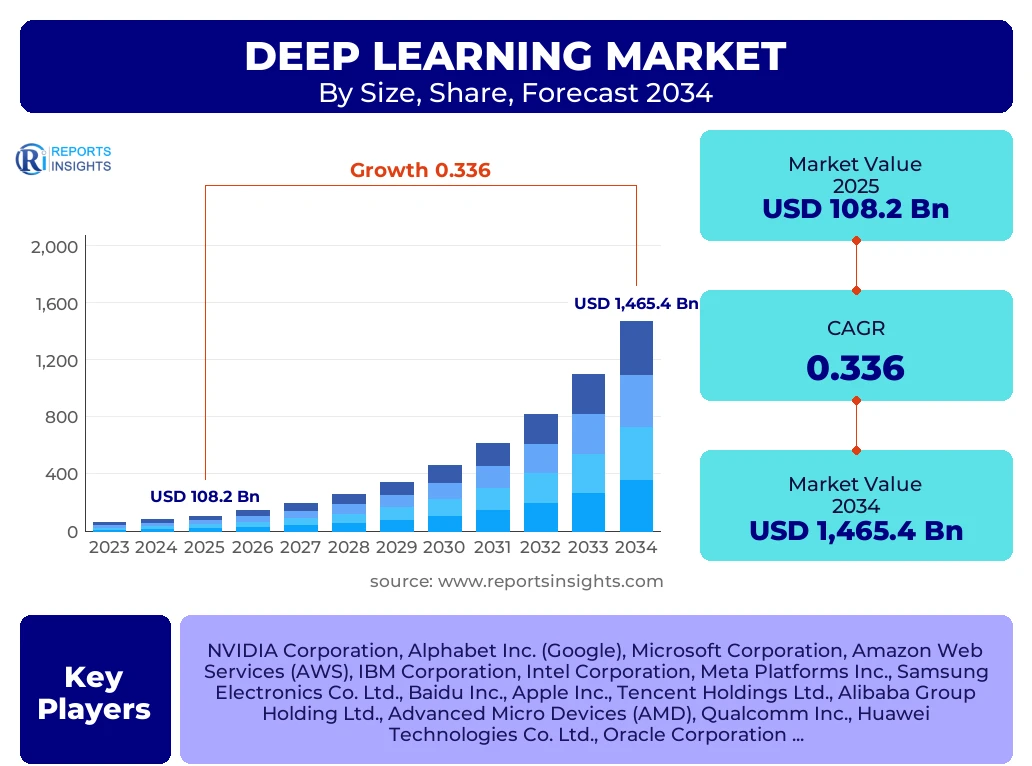
According to Reports Insights Consulting Pvt Ltd, The Deep Learning Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 33.6% between 2026 and 2034. The market is estimated at USD 144.5 Billion in 2026 and is projected to reach USD 1,465.4 Billion by the end of the forecast period in 2034.
Key Deep Learning Market Trends & Insights
The global deep learning landscape is currently undergoing a transformative phase driven by the convergence of massive datasets, specialized hardware acceleration, and the proliferation of Generative AI. Enterprise stakeholders are increasingly prioritizing the integration of Large Language Models (LLMs) and computer vision systems to automate complex decision-making processes. Strategic benchmarking reveals that companies are shifting from general-purpose cloud computing to tailored on-premise and edge-based AI infrastructure to mitigate latency and enhance data security. Furthermore, the rise of "AI-as-a-Service" (AIaaS) is democratizing access to deep learning capabilities, allowing small and medium enterprises to leverage sophisticated neural networks without significant capital expenditure. Regional insights indicate a surge in sovereign AI initiatives, particularly in Europe and Asia, where governments are investing in domestic compute clusters to ensure technological autonomy.
- Largest Region: North America remains the dominant market share holder, driven by the presence of major technology pioneers and high R&D investment in Silicon Valley.
- Fastest Growing Region: Asia-Pacific is anticipated to exhibit the highest CAGR, fueled by rapid digitalization in China, India, and South Korea, alongside massive government support for AI infrastructure.
- Largest Segment by Component: Hardware currently holds the largest share due to the intensive demand for high-performance GPUs, TPUs, and ASICs required for model training.
- Largest Segment by Application: Image Recognition and Computer Vision lead the market, largely due to their critical role in autonomous vehicles, medical imaging, and security surveillance.
- Emerging Trend: The shift toward Edge AI is accelerating, moving deep learning inference from centralized data centers to localized devices for real-time processing.
Key Takeaways Deep Learning Market Size & Forecast
The trajectory of the deep learning market suggests an exponential expansion as industries transition from experimental AI pilots to full-scale production deployments. Market forecasts indicate that the healthcare and automotive sectors will be the primary catalysts for long-term growth, as deep learning becomes indispensable for drug discovery and Level 4/5 autonomous driving. Financial institutions are also heavily adopting deep learning for real-time fraud detection and high-frequency trading algorithms. The market is characterized by a high degree of vertical integration, with hardware manufacturers developing proprietary software frameworks to lock in ecosystem participants. Stakeholders should anticipate a period of intense consolidation as major cloud providers acquire specialized AI startups to bolster their native deep learning offerings.
- Market Leadership: The United States and China are the primary contenders for global deep learning supremacy, accounting for over 60% of total market value.
- Investment Focus: Venture capital is increasingly flowing toward "Explainable AI" (XAI) and "Green AI" to address the growing concerns regarding neural network transparency and energy consumption.
- Strategic Imperative: Integration of deep learning with the Internet of Things (IoT) is expected to create a trillion-dollar opportunity in industrial automation and smart city infrastructure.
- Adoption Barrier: The scarcity of high-quality, labeled datasets remains a significant hurdle for training accurate deep learning models in niche industrial applications.
- Hardware Evolution: The transition from 5nm to 3nm and 2nm process technologies in semiconductor manufacturing will be a critical enabler for the next generation of deep learning performance.
Deep Learning Market Drivers Analysis
The acceleration of the deep learning market is fundamentally propelled by the exponential growth of unstructured data and the concurrent advancement in high-performance computing (HPC). As organizations across all verticals seek to extract actionable insights from video, audio, and sensor data, traditional machine learning techniques are proving insufficient, necessitating the multi-layered architectural approach of deep learning. Additionally, the rapid commercialization of self-driving technology and personalized medicine is creating a non-discretionary demand for sophisticated neural networks capable of real-time pattern recognition and predictive modeling.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Proliferation of Big Data and Unstructured Datasets | +8.5% | Global | 2025-2034 |
| Advancements in GPU and TPU Hardware Acceleration | +7.2% | North America and East Asia | 2025-2030 |
| Rising Demand for Generative AI and LLMs | +9.4% | United States and Western Europe | 2025-2034 |
| Expansion of Autonomous Systems in Logistics | +5.8% | Germany, China, and USA | 2027-2034 |
Deep Learning Market Restraints Analysis
Despite the optimistic growth projections, the deep learning market faces significant headwinds related to the "black box" nature of neural networks and the extreme computational costs associated with training state-of-the-art models. Regulatory scrutiny regarding data privacy, specifically under frameworks like GDPR and the EU AI Act, is forcing companies to invest heavily in compliance, which can slow down innovation cycles. Furthermore, the global shortage of specialized AI talent—including data scientists and machine learning engineers—limits the ability of non-tech enterprises to implement deep learning solutions effectively.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Computational and Energy Requirements | -4.2% | Global | 2025-2034 |
| Data Privacy and Ethical Constraints | -3.5% | European Union and North America | 2025-2034 |
| Shortage of Skilled AI Professionals | -5.1% | Emerging Economies and MEA | 2025-2029 |
| Model Interpretability and Transparency Issues | -2.8% | Regulated Industries (Healthcare/BFSI) | 2025-2034 |
Deep Learning Market Opportunities Analysis
The maturation of deep learning creates significant opportunities for innovation in Edge AI and federated learning, where data stays on the device to maintain privacy while the model improves collectively. The integration of deep learning with quantum computing also represents a frontier that could potentially solve optimization problems currently beyond the reach of classical silicon-based processors. Furthermore, there is a massive untapped market for deep learning applications in traditional sectors such as agriculture for precision farming and manufacturing for predictive maintenance, where efficiency gains can translate directly into substantial cost savings.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growth of Edge AI for Real-time Inference | +6.5% | Asia-Pacific and North America | 2026-2034 |
| Deep Learning in Drug Discovery and Genomics | +5.2% | Switzerland, UK, and USA | 2025-2034 |
| Sovereign AI Infrastructure Development | +4.8% | Middle East (UAE/KSA) and India | 2026-2032 |
| AI for Environmental Sustainability and Climate Modeling | +3.9% | Global | 2028-2034 |
Deep Learning Market Challenges Impact Analysis
The primary challenges facing the deep learning market include the volatility of the semiconductor supply chain and the increasing difficulty of obtaining diverse, unbiased datasets for model training. As models grow in complexity, the carbon footprint of data centers becomes a major corporate social responsibility (CSR) challenge, potentially leading to carbon taxes on AI training. Additionally, the threat of adversarial attacks—where small perturbations in input data can cause deep learning models to fail—presents a critical security risk for applications in defense and autonomous infrastructure.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Semiconductor Supply Chain Dependencies | -3.8% | Taiwan, South Korea, and USA | 2025-2028 |
| Algorithmic Bias and Social Fairness | -2.5% | Global | 2025-2034 |
| Adversarial Attacks and Cybersecurity Vulnerabilities | -4.0% | Global (Defense Sector) | 2026-2034 |
| Hardware-Software Interoperability Hurdles | -2.2% | Industrial IoT Sectors | 2025-2030 |
Deep Learning Market - Updated Report Scope
This market research report provides a granular analysis of the global deep learning ecosystem, covering the full value chain from hardware components and software frameworks to end-user applications. The scope includes an evaluation of Convolutional Neural Networks (CNNs), Recurrent Neural Networks (RNNs), and Transformers across diverse verticals such as Healthcare, BFSI, Retail, and Automotive. It provides a detailed roadmap of the technological shifts expected over the next decade, with a focus on regional regulatory environments and competitive benchmarking of the top 20 industry leaders.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 108.2 Billion |
| Market Forecast in 2034 | USD 1,465.4 Billion |
| Growth Rate | 33.6% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | NVIDIA Corporation, Alphabet Inc. (Google), Microsoft Corporation, Amazon Web Services (AWS), IBM Corporation, Intel Corporation, Meta Platforms Inc., Samsung Electronics Co. Ltd., Baidu Inc., Apple Inc., Tencent Holdings Ltd., Alibaba Group Holding Ltd., Advanced Micro Devices (AMD), Qualcomm Inc., Huawei Technologies Co. Ltd., Oracle Corporation, Hewlett Packard Enterprise (HPE), Tesla Inc., Adobe Inc., SAP SE |
| Regions Covered | North America (USA, Canada), Europe (Germany, UK, France, Italy, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Rest of APAC), Latin America (Brazil, Mexico), Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The deep learning market is segmented primarily by component, application, and end-user vertical. The hardware segment remains the largest by value, as the industry enters a "compute arms race" to build the world’s most powerful AI supercomputers. Within hardware, GPUs continue to dominate, though ASICs and TPUs are gaining traction for specific inference tasks due to their superior energy efficiency. On the software front, frameworks like PyTorch and TensorFlow are the de facto standards, but there is a growing market for automated machine learning (AutoML) platforms that simplify model development for non-experts.
- By Component: Includes Hardware (GPUs, TPUs, ASICs, CPUs, FPGAs), Software (Deep Learning Frameworks, Software Development Kits, Cloud Solutions), and Services (Consulting, Integration, Maintenance).
- By Architecture Type: Convolutional Neural Networks (CNN), Recurrent Neural Networks (RNN), Generative Adversarial Networks (GAN), Transformers, and Deep Belief Networks.
- By Application: Image Recognition, Signal Recognition, Data Mining, Natural Language Processing (NLP), Recommendation Engines, and Predictive Analytics.
- By Vertical: Healthcare (Medical Imaging, Drug Discovery), Automotive (Self-Driving Cars), BFSI (Risk Management, Fraud Analysis), Retail (Personalized Marketing), and Manufacturing (Defect Detection).
Regional Highlights
North America currently leads the global market, accounting for a significant share of the total revenue. This dominance is attributed to the presence of technology giants, a robust venture capital ecosystem, and early adoption of AI across federal and commercial sectors. However, the Asia-Pacific region is set to be the engine of future growth. China’s "New Generation Artificial Intelligence Development Plan" aims to make the country the world’s primary AI innovation center by 2030, resulting in massive investments in smart cities and surveillance infrastructure. In Europe, the focus is heavily weighted toward ethical AI and industrial applications (Industry 4.0), with Germany and the UK leading in AI research and automotive integration. The Middle East is emerging as a strategic hub, with nations like Saudi Arabia and the UAE investing oil revenues into high-tech diversification and large-scale AI data centers.
- North America: Largest market value, dominated by Silicon Valley ecosystem and hyperscale cloud providers.
- Asia-Pacific: Fastest growing region, driven by Chinese government initiatives and high smartphone/IoT penetration in India and SE Asia.
- Europe: Leading in regulatory frameworks and industrial AI applications within the manufacturing and automotive sectors.
- Middle East: Rapidly growing investment in "Sovereign AI" and national-level computing clusters.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Deep Learning Market.- NVIDIA Corporation
- Alphabet Inc. (Google)
- Microsoft Corporation
- Amazon Web Services (AWS)
- IBM Corporation
- Intel Corporation
- Meta Platforms Inc.
- Samsung Electronics Co. Ltd.
- Baidu Inc.
- Apple Inc.
- Tencent Holdings Ltd.
- Alibaba Group Holding Ltd.
- Advanced Micro Devices (AMD)
- Qualcomm Inc.
- Huawei Technologies Co. Ltd.
- Oracle Corporation
- Hewlett Packard Enterprise (HPE)
- Tesla Inc.
- Adobe Inc.
- SAP SE
Frequently Asked Questions
What is the projected market size of the Deep Learning market by 2034?
The global deep learning market is projected to reach approximately USD 1,465.4 Billion by 2034, growing at a CAGR of 33.6% from 2025.
Which region is expected to witness the fastest growth in the Deep Learning market?
Asia-Pacific is expected to be the fastest-growing region, driven by rapid industrialization, government-backed AI initiatives, and the expansion of the digital economy in China and India.
What are the primary drivers for the expansion of Deep Learning technology?
Key drivers include the massive increase in unstructured data, the surge in demand for Generative AI/LLMs, and significant advancements in high-performance computing hardware like GPUs and TPUs.
Which application segment holds the largest share in the Deep Learning market?
Image Recognition and Computer Vision currently hold the largest market share due to their widespread use in autonomous vehicles, security systems, and medical diagnostics.
Who are the leading players in the Deep Learning market?
The market is led by major technology firms including NVIDIA, Alphabet (Google), Microsoft, Amazon (AWS), IBM, Intel, and Meta, alongside specialized hardware and software providers.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted