Dark Fiber Network Market
Dark Fiber Network Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711890 | Published On : November 20, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Dark Fiber Network Market Size
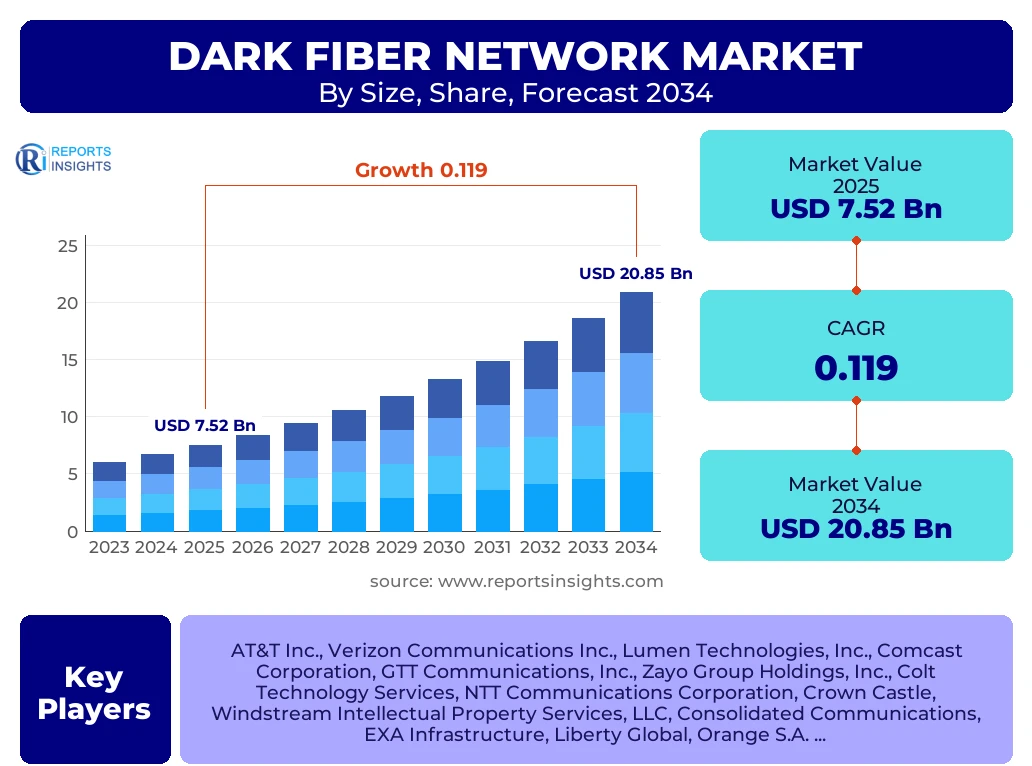
According to Reports Insights Consulting Pvt Ltd, The Dark Fiber Network Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 11.9% between 2025 and 2034. The market is estimated at USD 8.41 Billion in 2026 and is projected to reach USD 20.85 Billion by the end of the forecast period in 2034.
Key Dark Fiber Network Market Trends & Insights
The global dark fiber network market is currently navigating a transformative phase characterized by the massive decentralization of data processing and the aggressive rollout of next-generation telecommunications infrastructure. Stakeholders are increasingly prioritizing high-capacity, low-latency connections to support artificial intelligence (AI) workloads and edge computing architectures. Market intelligence suggests that the convergence of 5G densification and the proliferation of private LTE/5G networks for industrial applications is a primary catalyst for dark fiber adoption. Organizations are shifting away from lit fiber services toward dark fiber to gain absolute control over their network hardware and scaling capabilities, effectively future-proofing their digital foundations against exponential data growth. Competitive benchmarking reveals that industry leaders are focusing on strategic acquisitions of regional fiber providers to expand their footprint in Tier 2 and Tier 3 cities, where digital transformation is accelerating.
- Largest Region: North America remains the dominant market shareholder, driven by the presence of major hyperscale data centers and early 5G adoption.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR due to rapid urbanization, government-led digital initiatives in India and Southeast Asia, and massive investments in telecommunications infrastructure in China.
- Largest Segment by Type: Single-mode fiber holds the majority share owing to its superior performance in long-haul transmission and lower attenuation rates.
- Leading End-User: The IT and Telecommunications sector continues to lead, fueled by the demand for backhaul capacity and the expansion of internet service provider (ISP) networks.
Key Takeaways Dark Fiber Network Market Size & Forecast
The market trajectory for dark fiber is intrinsically linked to the global surge in bandwidth consumption and the institutional move toward data sovereignty. As enterprises across the BFSI and healthcare sectors seek to minimize latency while maximizing security, the appeal of dedicated, unlit fiber strands becomes undeniable. Research indicates that the forecast period will witness a significant shift in investment patterns, with a notable increase in "middle-mile" infrastructure development to bridge the gap between core data centers and local edge nodes. Furthermore, the rising integration of Smart City projects globally is expected to create a steady demand for dark fiber to connect millions of IoT sensors and municipal surveillance systems, ensuring the market maintains a robust double-digit growth rate through 2034.
- Strategic Infrastructure Control: Major tech giants are increasingly bypassing traditional carriers to build or lease private dark fiber loops, ensuring total management of their data transport layers.
- Hyperscale Data Center Influence: The expansion of cloud service providers (CSPs) like AWS, Azure, and Google Cloud is the single most significant factor driving long-haul dark fiber demand.
- Latency-Critical Applications: High-frequency trading and telemedicine are emerging as niche but high-value segments requiring dedicated fiber paths to eliminate jitter and packet loss.
- Regulatory Tailwinds: Government subsidies in the European Union and the United States aimed at rural broadband expansion are indirectly fueling dark fiber backbone growth.
Dark Fiber Network Market Drivers Analysis
The primary engines of growth in the dark fiber market include the unrelenting demand for high-speed internet, the evolution of 5G ecosystems, and the structural shift toward cloud-native enterprise environments. As data volumes explode, traditional lit services often become cost-prohibitive for high-capacity users, making the fixed-cost model of dark fiber highly attractive for long-term operational efficiency.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| 5G Network Densification | +3.5% | Global (Mainly US, China, South Korea) | 2025 - 2030 |
| Hyperscale Cloud Expansion | +2.8% | North America & Northern Europe | 2025 - 2034 |
| Edge Computing Deployment | +2.2% | Asia Pacific & Western Europe | 2027 - 2034 |
| Demand for Data Security/Sovereignty | +1.4% | European Union (GDPR compliance) | 2025 - 2029 |
Dark Fiber Network Market Restraints Analysis
Despite the positive outlook, the market faces significant hurdles, including the high capital expenditure (CAPEX) required for physical installation and the complex regulatory landscape regarding right-of-way (ROW) permits. These factors can deter smaller enterprises and delay project timelines in densely populated or strictly regulated urban zones.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial CAPEX | -1.8% | Developing Nations (LATAM, MEA) | Ongoing |
| Complex Regulatory Approvals | -1.2% | India, Brazil, Southeast Asia | 2025 - 2030 |
| Technical Maintenance Costs | -0.7% | Global | 2025 - 2034 |
Dark Fiber Network Market Opportunities Analysis
The emergence of AI-driven data centers and the potential for quantum networking represent significant frontiers for the dark fiber market. Additionally, the replacement of aging copper infrastructure in emerging economies provides a massive opportunity for greenfield dark fiber installations that can support multi-generational technology leaps.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
| AI-Centric Interconnects | +4.1% | US (Silicon Valley), China (Shenzhen) | 2026 - 2034 |
| Quantum Key Distribution (QKD) Networks | +1.5% | EU, North America | 2028 - 2034 |
| Smart City Integration | +2.4% | GCC Countries, SE Asia | 2027 - 2034 |
Dark Fiber Network Market Challenges Impact Analysis
Physical security and environmental factors pose a constant challenge to the integrity of fiber networks. Furthermore, the lack of standardized pricing models for dark fiber leases across different jurisdictions can create market inefficiencies and complicate the procurement process for multi-national corporations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Physical Network Security & Sabotage | -0.9% | Conflict Zones & Remote Areas | Ongoing |
| Geopolitical Tensions Affecting Hardware | -1.1% | US-China Trade Relations | 2025 - 2028 |
| Workforce Skill Shortage | -0.5% | Global (Technical Installers) | 2025 - 2030 |
Dark Fiber Network Market - Updated Report Scope
The scope of this report encompasses a granular analysis of the dark fiber infrastructure, focusing on leasing models, ownership structures, and technical specifications across diverse industrial verticals. It covers the entire value chain from fiber optic cable manufacturers to network integrators and end-users, providing a holistic view of the market dynamics. The study evaluates the impact of technological advancements such as hollow-core fiber and dense wavelength division multiplexing (DWDM) on the future of dark fiber utilization.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 7.52 Billion |
| Market Forecast in 2034 | USD 20.85 Billion |
| Growth Rate | 11.9% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | AT&T Inc., Verizon Communications Inc., Lumen Technologies, Inc., Comcast Corporation, GTT Communications, Inc., Zayo Group Holdings, Inc., Colt Technology Services, NTT Communications Corporation, Crown Castle, Windstream Intellectual Property Services, LLC, Consolidated Communications, EXA Infrastructure, Liberty Global, Orange S.A., Tata Communications, Cogent Communications, Inc., Unite Private Networks, FirstLight, NexGen Networks, Segra. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The dark fiber network market is segmented based on fiber type, network configuration, and end-user vertical. Single-mode fiber remains the gold standard for high-bandwidth applications over long distances due to its ability to maintain signal integrity without the need for frequent amplification. In contrast, multi-mode fiber is utilized in localized environments like campus networks or specific data center inter-rack connections, though its market share is gradually being squeezed by the falling costs of single-mode solutions.
- By Fiber Type:
- Single-mode Fiber: Dominates the market due to its core diameter and low attenuation, ideal for distances exceeding 10km.
- Multi-mode Fiber: Used for short-range communications, offering high bandwidth at lower costs for distances under 2km.
- By Network Type:
- Metro Dark Fiber: Focuses on connecting urban centers, business districts, and data center clusters within a city.
- Long-haul Dark Fiber: Connects cities and regions, often spanning thousands of miles to provide the backbone for national and international data traffic.
- By End-User:
- IT & Telecommunications: The primary driver of demand, utilizing dark fiber for mobile backhaul and ISP capacity.
- BFSI: Focuses on low-latency connections for high-frequency trading and secure data mirroring.
- Government & Education: High demand for secure, high-capacity research networks and municipal infrastructure.
- Content Providers/OTT: Hyperscalers leasing dark fiber to manage their massive content delivery networks (CDNs).
Regional Highlights
- North America: The largest market globally, characterized by high concentration of tech giants, advanced 5G infrastructure, and significant private investment in fiber backbones. The United States leads in dark fiber adoption for cloud connectivity.
- Asia Pacific: The fastest-growing region. China and India are seeing unprecedented growth in internet subscribers and mobile data consumption, necessitating massive dark fiber expansions. Government initiatives like "Digital India" and China's "Broadband China" strategy are key catalysts.
- Europe: Driven by strict data privacy laws (GDPR) and the push for digital sovereignty. Germany, the UK, and the Netherlands are major hubs for carrier-neutral fiber providers.
- Middle East & Africa: Emerging as a high-potential zone due to the landing of new subsea cables and the subsequent need for terrestrial dark fiber to move data inland.
- Latin America: Focused on upgrading legacy infrastructure in Brazil and Mexico to support growing e-commerce and fintech sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Dark Fiber Network Market.- AT&T Inc.
- Verizon Communications Inc.
- Lumen Technologies, Inc. (formerly CenturyLink)
- Comcast Corporation
- GTT Communications, Inc.
- Zayo Group Holdings, Inc.
- Colt Technology Services
- NTT Communications Corporation
- Crown Castle
- Windstream Intellectual Property Services, LLC
- Consolidated Communications
- EXA Infrastructure
- Liberty Global
- Orange S.A.
- Tata Communications
- Cogent Communications, Inc.
- Unite Private Networks
- FirstLight
- NexGen Networks
- Segra
Frequently Asked Questions
What is the primary difference between lit fiber and dark fiber?
Lit fiber is a service where the provider manages the electronics and provides a specific bandwidth capacity. Dark fiber consists of unlit optical strands, allowing the leaseholder to provide their own equipment and manage the network capacity and protocol entirely, offering virtually unlimited bandwidth scalability.
Why are enterprises increasingly choosing dark fiber over traditional managed services?
Enterprises choose dark fiber to achieve lower latency, better data security, and long-term cost predictability. By controlling the lighting equipment, organizations can upgrade their speeds without renegotiating contracts with service providers.
How does the 5G rollout impact the dark fiber network market?
5G requires a significantly denser network of small cells compared to 4G. These small cells need high-capacity backhaul connections to the core network, and dark fiber is the most efficient and scalable solution to handle the massive data throughput generated by 5G devices.
Which region is expected to lead the dark fiber market in terms of growth rate?
The Asia Pacific region is expected to lead in growth rate due to rapid digital transformation, increasing smartphone penetration, and massive investments in telecommunications infrastructure by both private and public sectors.
What are the main technical challenges in deploying dark fiber?
The main challenges include the physical installation hurdles such as obtaining right-of-way permits, the cost of trenching in urban areas, and the need for specialized technical expertise to maintain and troubleshoot the fiber infrastructure.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
